


 |
市場調查報告書
商品編碼
2045772
清潔標籤殺菌劑市場機會、成長要素、產業趨勢分析及2026-2035年預測Clean Label Mold Inhibitors Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

2025 年全球清潔標籤殺菌劑市場價值 31 億美元,預計到 2035 年將以 6.6% 的複合年成長率成長至 58 億美元。
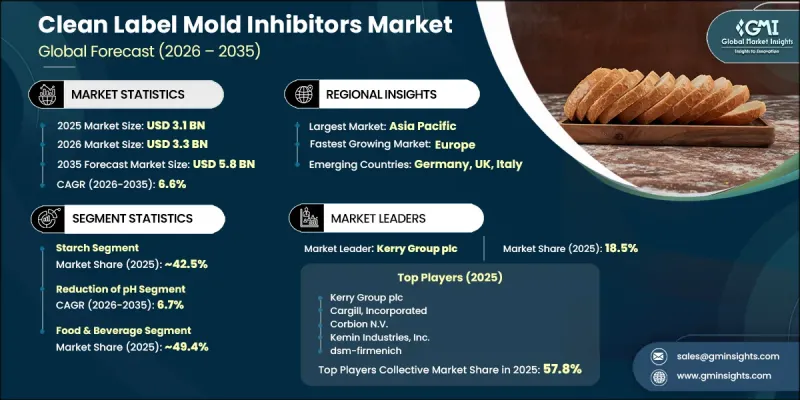
隨著消費者對天然、來源透明的食品需求日益成長,清潔標籤黴菌抑制劑產業正經歷強勁成長。消費者對更健康消費模式的轉變促使製造商用天然替代品取代合成防腐劑,以確保食品安全和品質。這些抑制劑在抑制微生物生長方面發揮著至關重要的作用,從而維持食品品質、延長保存期限並減少整個供應鏈中的食品廢棄物。由於它們能夠在滿足嚴格監管標準的同時保持產品新鮮度,因此在眾多行業中備受青睞。除了食品飲料產業外,這些解決方案也被應用於需要抑制微生物生長和維持產品穩定性的領域。持續創新推動了更有效配方的開發,從而在性能和清潔標籤要求之間取得平衡。隨著消費者意識的提高和法律規範的日益嚴格,對安全、天然防腐解決方案的需求更加強勁,預計全球市場將持續穩定成長。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 31億美元 |
| 預測市場規模 | 58億美元 |
| 複合年成長率 | 6.6% |
預計到2025年,澱粉類產品將佔據42.5%的市場佔有率,並在2035年之前以6.7%的複合年成長率成長。該領域因其天然來源、可生物分解性和與多種配方的兼容性而備受關注。持續的技術進步提高了澱粉基溶液的抗菌效率,在延長保存期限的同時,也符合清潔標籤標準。該領域的廣泛應用持續推動其在各類產品類型中的普及。
預計到2025年,pH值降低技術將佔據74%的市場佔有率,並在2026年至2035年間以6.7%的複合年成長率成長。此方法在創造不適合微生物生長的環境方面仍然非常有效,從而確保產品的安全性和穩定性。透過將天然酸化技術與源自各種原料的生物活性化合物結合,可以在維持產品品質的同時增強抗真菌效果。這種機制具有廣泛的適用性,並符合市場對天然防腐技術日益成長的需求。
預計到2025年,北美清潔標籤黴菌抑制劑市場將佔據19.3%的市場佔有率,反映出該地區強勁的需求和快速成長。由於消費者越來越偏好加工最少、天然來源的產品,市場持續擴張。嚴格的監管標準和日益增強的食品安全意識正促使製造商採用清潔標籤解決方案。持續的創新和行業的積極參與進一步推動了市場發展,同時,各行業對高品質天然防腐系統的需求也在不斷成長。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章 行業洞察
- 產業生態系分析
- 供應商情況
- 利潤率
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 產業潛在風險與挑戰
- 市場機遇
- 成長潛力分析
- 監理情勢
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 波特的分析
- PESTLE分析
- 價格趨勢
- 按地區
- 按類型
- 未來市場趨勢
- 技術與創新展望
- 最新科技趨勢
- 新興技術
- 專利趨勢
- 貿易統計
- 主要進口國
- 主要出口國
- 永續性和環境方面
- 永續計劃
- 減少廢棄物策略
- 生產中的能源效率
- 具有環保意識的舉措
- 考慮碳足跡
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 北美洲
- 歐洲
- 亞太地區
- LATAM
- 中東和非洲
- 按地區
- 企業矩陣分析
- 主要市場公司的競爭分析
- 競爭定位矩陣
- 主要進展
- 併購
- 夥伴關係和聯盟
- 新產品發布
- 業務拓展計劃
第5章 市場估計與預測:依類型分類,2022-2035年
- 澱粉
- 醋
- 發酵麵粉
- 乳清
- 其他
第6章 市場估計與預測:依功能分類,2022-2035年
- pH值下降
- 黴菌細胞膜的破壞
第7章 市場估計與預測:依應用領域分類,2022-2035年
- 食品/飲料
- 烘焙產品
- 糖果甜點
- 乳製品和乳製品替代品
- 飲料
- 肉類和家禽產品
- 零食和已調理食品
- 醬汁、調味料和佐料
- 製藥
- 口服製劑
- 外用製劑
- 營養保健品和膳食補充劑
- 動物飼料
- 家禽飼料
- 反芻動物飼料
- 水產飼料
- 寵物食品
- 個人護理和化妝品
- 護膚品
- 護髮產品
- 口腔護理產品
- 彩妝
- 其他
第8章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 其他亞太國家
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 其他拉丁美洲國家
- 中東和非洲
- 沙烏地阿拉伯
- 南非
- UAE
- 其他中東和非洲國家
第9章:公司簡介
- Archer Daniels Midland Company(ADM)
- BASF SE
- Brenntag AG
- Cargill, Incorporated
- Corbion NV
- dsm-firmenich
- Ingredion Incorporated
- Kemin Industries, Inc.
- Kerry Group plc
- Lallemand Inc.
- Puratos Group
- Tate &Lyle PLC
The Global Clean Label Mold Inhibitors Market was valued at USD 3.1 billion in 2025 and is estimated to grow at a CAGR of 6.6% to reach USD 5.8 billion by 2035.
The clean label mold inhibitors industry is gaining strong momentum as consumers increasingly demand food products made with natural, recognizable, and transparent ingredients. The shift toward healthier consumption patterns is encouraging manufacturers to replace synthetic preservatives with naturally derived alternatives that maintain both safety and product integrity. These inhibitors play a critical role in preventing microbial growth, thereby preserving quality, extending shelf life, and reducing food waste across supply chains. Their ability to meet strict regulatory standards while maintaining product freshness makes them highly valuable across multiple industries. Beyond food and beverages, these solutions are also being adopted in applications requiring microbial control and product stability. Continuous innovation is enabling the development of more effective formulations that balance performance with clean label expectations. As consumer awareness grows and regulatory frameworks tighten, the demand for safe, natural preservation solutions continues to strengthen, positioning the market for sustained and consistent expansion globally.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $3.1 Billion |
| Forecast Value | $5.8 Billion |
| CAGR | 6.6% |
The starch segment held a 42.5% share in 2025 and is expected to grow at a CAGR of 6.7% through 2035. This segment is gaining traction due to its natural origin, biodegradability, and compatibility with a wide range of formulations. Ongoing advancements are improving the antimicrobial efficiency of starch-based solutions, enabling enhanced preservation performance while maintaining clean label standards. The versatility of this segment continues to support its widespread adoption across various product categories.
The pH reduction segment held a 74% share in 2025 and is projected to grow at a CAGR of 6.7% between 2026 and 2035. This approach remains highly effective as it creates an unfavorable environment for microbial growth, ensuring product safety and stability. Natural acidification methods, combined with bioactive compounds derived from various sources, enhance antifungal effectiveness while maintaining product integrity. This mechanism supports broad applicability and aligns well with the increasing demand for natural preservation techniques.
North America Clean Label Mold Inhibitors Market held 19.3% share in 2025, reflecting strong regional demand and rapid growth. The region continues to expand due to increasing consumer preference for minimally processed and naturally derived products. Strict regulatory standards and heightened awareness around food safety are encouraging manufacturers to adopt clean label solutions. Ongoing innovation and strong industry participation are further supporting market development, while the demand for high-quality, natural preservation systems continues to rise across multiple sectors.
Key companies operating in the Global Clean Label Mold Inhibitors Market include Cargill, Incorporated, Archer Daniels Midland Company (ADM), BASF SE, Brenntag AG, Corbion N.V., DSM-Firmenich, Ingredion Incorporated, Kemin Industries, Inc., Kerry Group plc, Lallemand Inc., Puratos Group, and Tate & Lyle PLC. Companies in the clean label mold inhibitors market are adopting strategic initiatives to strengthen their market position and expand their global footprint. Organizations are investing in advanced research and development to create innovative, high-performance natural preservation solutions that meet evolving consumer expectations. Product portfolio diversification is a key focus, enabling companies to cater to a wider range of applications and industries. Strategic partnerships and collaborations are being leveraged to enhance technological capabilities and accelerate innovation. Companies are also prioritizing sustainable sourcing and environmentally responsible production practices to align with regulatory requirements and market trends.
Table of Contents
Chapter 1 Methodology & Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Type
- 2.2.3 Function
- 2.2.4 Application
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
- 2.4.1 Executive decision points
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin
- 3.1.3 Value addition at each stage
- 3.1.4 Factor affecting the value chain
- 3.1.5 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.2 Industry pitfalls and challenges
- 3.2.3 Market opportunities
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter's analysis
- 3.6 PESTEL analysis
- 3.7 Price trends
- 3.7.1 By region
- 3.7.2 By type
- 3.8 Future market trends
- 3.9 Technology and Innovation landscape
- 3.9.1 Current technological trends
- 3.9.2 Emerging technologies
- 3.10 Patent Landscape
- 3.11 Trade statistics (HS code)
- 3.11.1 Major importing countries
- 3.11.2 Major exporting countries
- 3.12 Sustainability and environmental aspects
- 3.12.1 Sustainable practices
- 3.12.2 Waste reduction strategies
- 3.12.3 Energy efficiency in production
- 3.12.4 Eco-friendly initiatives
- 3.13 Carbon footprint consideration
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 LATAM
- 4.2.1.5 MEA
- 4.2.1 By region
- 4.3 Company matrix analysis
- 4.4 Competitive analysis of major market players
- 4.5 Competitive positioning matrix
- 4.6 Key developments
- 4.6.1 Mergers & acquisitions
- 4.6.2 Partnerships & collaborations
- 4.6.3 New Product Launches
- 4.6.4 Expansion Plans
Chapter 5 Market Estimates and Forecast, By Type, 2022-2035 (USD Billion) (Kilo Tons)
- 5.1 Key trends
- 5.2 Starch
- 5.3 Vinegar
- 5.4 Cultured flour
- 5.5 Whey
- 5.6 Others
Chapter 6 Market Estimates and Forecast, By Function, 2022-2035 (USD Billion) (Kilo Tons)
- 6.1 Key trends
- 6.2 Reduction of pH
- 6.3 Disruption of mold cellular membranes
Chapter 7 Market Estimates and Forecast, By Application, 2022-2035 (USD Billion) (Kilo Tons)
- 7.1 Key trends
- 7.2 Food & beverages
- 7.2.1 Bakery products
- 7.2.2 Confectionery
- 7.2.3 Dairy & dairy alternatives
- 7.2.4 Beverages
- 7.2.5 Meat & poultry products
- 7.2.6 Snacks & prepared foods
- 7.2.7 Sauces, dressings & condiments
- 7.2.8 Pharmaceuticals
- 7.2.9 Oral formulations
- 7.2.10 Topical formulations
- 7.2.11 Nutraceuticals & dietary supplements
- 7.3 Animal feed
- 7.3.1 Poultry feed
- 7.3.2 Ruminant feed
- 7.3.3 Aquaculture feed
- 7.3.4 Pet food
- 7.4 Personal care & cosmetics
- 7.4.1 Skincare products
- 7.4.2 Haircare products
- 7.4.3 Oral care products
- 7.4.4 Color cosmetics
- 7.5 Others
Chapter 8 Market Estimates and Forecast, By Region, 2022-2035 (USD Billion) (Kilo Tons)
- 8.1 Key trends
- 8.2 North America
- 8.2.1 U.S.
- 8.2.2 Canada
- 8.3 Europe
- 8.3.1 Germany
- 8.3.2 UK
- 8.3.3 France
- 8.3.4 Spain
- 8.3.5 Italy
- 8.3.6 Rest of Europe
- 8.4 Asia Pacific
- 8.4.1 China
- 8.4.2 India
- 8.4.3 Japan
- 8.4.4 Australia
- 8.4.5 South Korea
- 8.4.6 Rest of Asia Pacific
- 8.5 Latin America
- 8.5.1 Brazil
- 8.5.2 Mexico
- 8.5.3 Argentina
- 8.5.4 Rest of Latin America
- 8.6 Middle East and Africa
- 8.6.1 Saudi Arabia
- 8.6.2 South Africa
- 8.6.3 UAE
- 8.6.4 Rest of Middle East and Africa
Chapter 9 Company Profiles
- 9.1 Archer Daniels Midland Company (ADM)
- 9.2 BASF SE
- 9.3 Brenntag AG
- 9.4 Cargill, Incorporated
- 9.5 Corbion N. V.
- 9.6 dsm-firmenich
- 9.7 Ingredion Incorporated
- 9.8 Kemin Industries, Inc.
- 9.9 Kerry Group plc
- 9.10 Lallemand Inc.
- 9.11 Puratos Group
- 9.12 Tate & Lyle PLC

 美國壁材及牆面裝飾:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)
 黴菌清除服務市場:按表面類型、黴菌類型、服務類型、應用和地區分類
 2026年全球潔淨標示黴菌抑制劑市場報告
 殺菌劑市場:按類型、劑型、功能和應用分類-2026-2032年全球預測防霧塗料市場按產品類型、技術、最終用途和分銷管道分類-全球預測,2026-2032年
 全球潔淨標示殺菌劑市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 殺菌劑市場規模、佔有率和成長分析(按類型、特性、應用和地區分類)-2026-2033年產業預測
 全球除黴服務市場全球潔淨標示殺菌劑市場
 全球 B2B殺菌劑市場(2025 年)