

 |
市場調查報告書
商品編碼
2038372
高速資料轉換器市場機會、成長要素、產業趨勢分析及2026-2035年預測High-Speed Data Converter Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

2025年全球高速數據轉換器市值為39億美元,預計2035年將以7.8%的複合年成長率成長至83億美元。
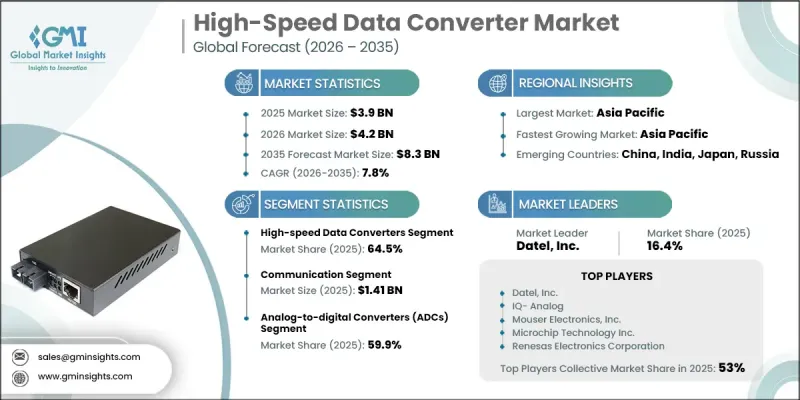
隨著工業領域在通訊、運算和感測等應用中對高速即時數據處理的依賴日益加深,市場正經歷強勁擴張。數位化進程的推進和資料密集型生態系統的持續成長,推動了對先進訊號轉換技術的需求。數位基礎設施的擴展和對更高頻寬能力日益成長的需求,進一步強化了對高效能類比數位轉換器 (A/D) 和數位類比轉換器 (D/A) 的需求。半導體設計和製造技術的快速發展,提高了轉換器的效率、精度和處理速度。智慧系統在互聯環境中的日益整合,也促進了市場擴張。現代電子系統日益複雜,由此產生的對精確高速資料處理的需求,進一步推動了市場需求。轉換器架構的持續創新,提升了多個終端應用產業的效能。朝向即時分析、邊緣運算和高頻訊號處理的轉變,加速了高速資料轉換器的應用,使其成為下一代電子系統的關鍵元件。
| 市場範圍 | |
|---|---|
| 開始年份 | 2025 |
| 預測期 | 2026-2035 |
| 上市時的市場規模 | 39億美元 |
| 預測市場規模 | 83億美元 |
| 複合年成長率 | 7.8% |
市場成長主要受先進無線通訊網路(包括需要低延遲和高頻寬效能的下一代連接平台)快速部署的強勁驅動。無線基礎設施的擴展、感測和雷達技術的日益普及以及先進汽車電子產品的整合進一步推動了市場需求。雲端和邊緣環境中資料中心應用的日益廣泛也促進了市場成長。此外,自主和無人系統的擴展為高效能資料轉換技術創造了新的機會。半導體架構的不斷改進提高了系統效率,改善了訊號質量,並擴展了跨行業的應用範圍。
預計到2025年,高速資料轉換器市場佔有率將達到64.5%,這主要得益於其在通訊系統、雷達應用、航太技術和高效能運算平台等領域的廣泛應用。這些轉換器對於需要高速訊號處理、高頻寬處理和即時資料精度的應用至關重要。它們能夠在保持精度的同時支援大規模複雜處理,使其成為先進電子系統的核心組件。關鍵產業對高速處理的日益成長的需求也進一步推動了對該領域產品的需求。
受高精度、高速訊號分析需求不斷成長的推動,測試與測量領域預計將在2026年至2035年間以8.9%的複合年成長率成長。電子系統日益複雜,對精確、即時測量的需求不斷成長,推動了該技術在科學研究、半導體評估和國防應用領域的普及。先進技術對高解析度測試解決方案的需求,進一步加速了高速資料轉換器在該領域的應用。
預計到2025年,北美高速數據轉換器市場佔有率將達到29.1%,主要得益於強大的數位基礎設施建設和技術的快速普及。該地區高頻寬通訊網路的部署和資料中心基礎設施的擴張持續推進。先進連接技術的早期應用進一步推動了對高速資料轉換器的需求。除了成熟的半導體生態系統外,該地區在國防和航太領域的強大實力也持續支撐著市場成長和技術進步。
目錄
第1章:調查方法和範圍
第2章執行摘要
第3章業界考察
- 生態系分析
- 供應商情況
- 利潤率
- 成本結構
- 每個階段增加的價值
- 影響價值鏈的因素
- 中斷
- 影響產業的因素
- 促進因素
- 快速部署5G和下一代無線通訊基礎設施
- 對高效能資料擷取系統的需求日益成長
- 雲端運算和資料中心中以資料為中心的應用程式不斷擴展
- 高速轉換器在雷達、成像和國防系統中的應用正在不斷推進。
- 先進汽車電子產品和自動駕駛系統的應用日益普及
- 產業潛在風險與挑戰
- 高速轉換器的高功耗和溫度控管限制
- 高頻系統的設計複雜性與整合挑戰
- 市場機遇
- 航太和航太電子領域對高速轉換器的需求日益成長。
- 高速轉換器在醫學影像和診斷領域的應用日益廣泛。
- 促進因素
- 成長潛力分析
- 監理情勢
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 波特五力分析
- PESTEL 分析
- 科技與創新趨勢
- 當前技術趨勢
- 新興技術
- 價格趨勢
- 按地區
- 依產品
- 定價策略
- 新興經營模式
- 合規要求
- 專利和智慧財產權分析
- 地緣政治和貿易趨勢
第4章 競爭情勢
- 介紹
- 企業市佔率分析
- 按地區
- 北美洲
- 歐洲
- 亞太地區
- 拉丁美洲
- 中東和非洲
- 市場集中度分析
- 按地區
- 主要公司的競爭標竿分析
- 財務績效比較
- 銷售量
- 利潤率
- 研究與開發
- 產品系列比較
- 產品線寬度
- 科技
- 創新
- 區域擴張比較
- 全球擴張分析
- 服務網路覆蓋
- 按地區分類的市場滲透率
- 競爭定位矩陣
- 領導者
- 挑戰者
- 追蹤者
- 小眾玩家
- 戰略展望矩陣
- 財務績效比較
- 主要進展
- 併購
- 夥伴關係和聯盟
- 技術進步
- 業務拓展與投資策略
- 數位轉型計劃
- 新興/新創競爭對手的發展趨勢
第5章 市場估計與預測:依類型分類,2022-2035年
- 類比數位轉換器(ADC)
- 航空電子設備用數位類比轉換器(DAC)軟體。
第6章 市場估計與預測:依抽樣率分類,2022-2035年
- 高速資料轉換器
- 通用資料轉換器
第7章 市場估計與預測:依解析度分類,2022-2035年
- Line-Fit(OEM)
- 售後市場(改裝和維護、維修和大修)
- 800萬像素或更高
- 8 位元
- 10 位元
- 12 位元
- 16 位元
- 24 位元或更高
第8章 市場估計與預測:依應用領域分類,2022-2035年
- 車
- 溝通
- 工業自動化
- 測試與管理
- 其他
第9章 市場估計與預測:依地區分類,2022-2035年
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 英國
- 法國
- 西班牙
- 義大利
- 俄羅斯
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 拉丁美洲
- 巴西
- 墨西哥
- 阿根廷
- 中東和非洲
- 南非
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
第10章:公司簡介
- 全球主要公司
- Datel, Inc.
- IQ-Analog
- Mouser Electronics, Inc.
- Microchip Technology Inc.
- Renesas Electronics Corporation
- 按地區分類的主要公司
- 北美洲
- Analog Devices, Inc.
- Broadcom Inc.
- Cirrus Logic, Inc.
- ON Semiconductor
- Qualcomm Technologies, Inc.
- Skyworks Solutions, Inc.
- Texas Instruments
- Xilinx, Inc.
- 歐洲
- Infineon Technologies AG
- NXP Semiconductors
- STMicroelectronics
- ROHM Semiconductor
- 亞太地區
- Asahi Kasei Microdevices Corporation
- MediaTek Inc.
- Realtek Semiconductor Corp.
- Samsung Electronics Co., Ltd.
- Avia Semiconductor Ltd.
- 北美洲
The Global High-Speed Data Converter Market was valued at USD 3.9 billion in 2025 and is estimated to grow at a CAGR of 7.8% to reach USD 8.3 billion by 2035.
The market is witnessing strong expansion as industries increasingly rely on high-speed and real-time data processing across communication, computing, and sensing applications. Rising digitalization and the continuous growth of data-intensive ecosystems are increasing the need for advanced signal conversion technologies. Expanding digital infrastructure and the growing requirement for higher bandwidth capabilities are further strengthening demand for high-performance analog-to-digital and digital-to-analog converters. Rapid advancements in semiconductor design and fabrication technologies are improving converter efficiency, accuracy, and processing speed. The increasing integration of intelligent systems in connected environments is also contributing to market expansion. Demand is further reinforced by the growing complexity of modern electronic systems, which require precise and high-speed data handling. Continuous innovation in converter architectures is enhancing performance across multiple end-use industries. The shift toward real-time analytics, edge computing, and high-frequency signal processing is accelerating adoption, making high-speed data converters a critical component in next-generation electronic systems.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $3.9 Billion |
| Forecast Value | $8.3 Billion |
| CAGR | 7.8% |
The growth of the market is strongly supported by the rapid rollout of advanced wireless communication networks, including next-generation connectivity platforms that require low latency and high bandwidth performance. Expanding wireless infrastructure, increasing deployment of sensing and radar technologies, and rising integration of advanced automotive electronics are further driving demand. The increasing use of data-centric applications across cloud and edge environments is also contributing to market growth. In addition, the expansion of autonomous and unmanned systems is creating new opportunities for high-performance data conversion technologies. Continuous improvements in semiconductor architectures are enabling better system efficiency, improved signal integrity, and broader application scope across industries.
The high-speed data converters segment accounted for a 64.5% share in 2025 owing to its extensive use across communication systems, radar applications, aerospace technologies, and high-performance computing platforms. These converters are essential for applications requiring rapid signal processing, high bandwidth handling, and real-time data accuracy. Their ability to support large-scale and complex operations while maintaining precision makes them a core component in advanced electronic systems. The growing reliance on high-speed processing across critical industries continues to strengthen demand for this segment.
The test and measurement segment is projected to grow at a CAGR of 8.9% during 2026-2035, driven by increasing demand for high-precision and high-speed signal analysis. Rising complexity in electronic systems and the need for accurate real-time measurement are supporting adoption across scientific research, semiconductor evaluation, and defense applications. The requirement for high-resolution testing solutions in advanced technologies is further accelerating the use of high-speed data converters in this segment.
North America High-Speed Data Converter Market held a share of 29.1% in 2025, supported by strong digital infrastructure development and rapid technological adoption. The region continues to witness increased deployment of high-bandwidth communication networks and expansion of data center infrastructure. Early adoption of advanced connectivity technologies is further driving demand for high-speed data converters. A well-established semiconductor ecosystem, combined with strong capabilities in defense and aerospace industries, continues to support regional market growth and technological advancement.
Major players in the Global High-Speed Data Converter Market include Analog Devices, Inc., Broadcom Inc., Cirrus Logic, Inc., Asahi Kasei Microdevices Corporation, Avia Semiconductor Ltd., Infineon Technologies AG, Datel, Inc., IQ-Analog, Mouser Electronics, Inc., MediaTek Inc., Microchip Technology Inc., NXP Semiconductors, ON Semiconductor, Qualcomm Technologies, Inc., Realtek Semiconductor Corp., Renesas Electronics Corporation, ROHM Semiconductor, Samsung Electronics Co., Ltd., Skyworks Solutions, Inc., STMicroelectronics, Texas Instruments, and Xilinx, Inc. Companies operating in the Global High-Speed Data Converter Market are focusing on advanced semiconductor innovation, product miniaturization, and performance optimization to strengthen their competitive position. They are investing in research and development to enhance signal accuracy, increase processing speed, and improve energy efficiency. Strategic collaborations and partnerships are being used to accelerate technological advancement and expand market reach. Firms are also diversifying product portfolios to address the growing demand across communication, automotive, and industrial sectors. Emphasis on integration with AI-driven systems and edge computing platforms is supporting next-generation applications.
Table of Contents
Chapter 1 Methodology and Scope
- 1.1 Market scope and definition
- 1.2 Research design
- 1.2.1 Research approach
- 1.2.2 Data collection methods
- 1.3 Data mining sources
- 1.3.1 Global
- 1.3.2 Regional/Country
- 1.4 Base estimates and calculations
- 1.4.1 Base year calculation
- 1.4.2 Key trends for market estimation
- 1.5 Primary research and validation
- 1.5.1 Primary sources
- 1.6 Forecast model
- 1.7 Research assumptions and limitations
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis, 2022 - 2035
- 2.2 Key market trends
- 2.2.1 Type trends
- 2.2.2 Sampling rate trends
- 2.2.3 Resolution trends
- 2.2.4 Application trends
- 2.2.5 Regional trends
- 2.3 TAM Analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
- 2.4.1 Executive decision points
- 2.4.2 critical success factors
- 2.5 Future outlook and strategic recommendations
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier Landscape
- 3.1.2 Profit Margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Rapid adoption of 5G and next-generation wireless communication infrastructure
- 3.2.1.2 Increasing demand for high-performance data acquisition systems
- 3.2.1.3 Expansion of data-centric applications in cloud computing and data centers
- 3.2.1.4 Growing integration of high-speed converters in radar, imaging, and defense systems
- 3.2.1.5 Rising adoption of advanced automotive electronics and autonomous systems
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 High power consumption and thermal management constraints in high-speed converters
- 3.2.2.2 Design complexity and integration challenges in high-frequency systems
- 3.2.3 Market opportunities
- 3.2.3.1 Rising demand for high-speed converters in aerospace and space electronics
- 3.2.3.2 Increasing adoption of high-speed converters in medical imaging and diagnostics
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Regulatory landscape
- 3.4.1 North America
- 3.4.2 Europe
- 3.4.3 Asia Pacific
- 3.4.4 Latin America
- 3.4.5 Middle East & Africa
- 3.5 Porter's analysis
- 3.6 PESTEL analysis
- 3.7 Technology and Innovation landscape
- 3.7.1 Current technological trends
- 3.7.2 Emerging technologies
- 3.8 Price trends
- 3.8.1 By region
- 3.8.2 By product
- 3.9 Pricing Strategies
- 3.10 Emerging Business Models
- 3.11 Compliance Requirements
- 3.12 Patent and IP analysis
- 3.13 Geopolitical and trade dynamics
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 By region
- 4.2.1.1 North America
- 4.2.1.2 Europe
- 4.2.1.3 Asia Pacific
- 4.2.1.4 Latin America
- 4.2.1.5 Middle East & Africa
- 4.2.2 Market concentration analysis
- 4.2.1 By region
- 4.3 Competitive benchmarking of key players
- 4.3.1 Financial performance comparison
- 4.3.1.1 Revenue
- 4.3.1.2 Profit margin
- 4.3.1.3 R&D
- 4.3.2 Product portfolio comparison
- 4.3.2.1 Product range breadth
- 4.3.2.2 Technology
- 4.3.2.3 Innovation
- 4.3.3 Geographic presence comparison
- 4.3.3.1 Global footprint analysis
- 4.3.3.2 Service network coverage
- 4.3.3.3 Market penetration by region
- 4.3.4 Competitive positioning matrix
- 4.3.4.1 Leaders
- 4.3.4.2 Challengers
- 4.3.4.3 Followers
- 4.3.4.4 Niche players
- 4.3.5 Strategic outlook matrix
- 4.3.1 Financial performance comparison
- 4.4 Key developments
- 4.4.1 Mergers and acquisitions
- 4.4.2 Partnerships and collaborations
- 4.4.3 Technological advancements
- 4.4.4 Expansion and investment strategies
- 4.4.5 Digital transformation initiatives
- 4.5 Emerging/ startup competitors landscape
Chapter 5 Market Estimates and Forecast, By Type, 2022 - 2035
- 5.1 Key trends
- 5.2 Analog-to-digital converters (ADCs)
- 5.3 Digital-to-analog converters (DACs)avionics software
Chapter 6 Market Estimates and Forecast, By Sampling Rate, 2022 - 2035
- 6.1 Key trends
- 6.2 High-speed data converters
- 6.3 General-purpose data converters
Chapter 7 Market Estimates and Forecast, By Resolution, 2022 - 2035
- 7.1 Key trends
- 7.2 Line Fit (OEM)
- 7.3 Aftermarket (retrofit & MRO)
- 7.4 Above 8MP
- 7.5 8-bit
- 7.6 10-bit
- 7.7 12-bit
- 7.8 16-bit
- 7.9 24-bit and above
Chapter 8 Market Estimates and Forecast, By Application, 2022 - 2035
- 8.1 Key trends
- 8.2 Automotive
- 8.3 Communication
- 8.4 Industrial automation
- 8.5 Test & management
- 8.6 Others
Chapter 9 Market Estimates and Forecast, By Region, 2022 - 2035
- 9.1 Key trends
- 9.2 North America
- 9.2.1 U.S.
- 9.2.2 Canada
- 9.3 Europe
- 9.3.1 Germany
- 9.3.2 UK
- 9.3.3 France
- 9.3.4 Spain
- 9.3.5 Italy
- 9.3.6 Russia
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 India
- 9.4.3 Japan
- 9.4.4 Australia
- 9.4.5 South Korea
- 9.5 Latin America
- 9.5.1 Brazil
- 9.5.2 Mexico
- 9.5.3 Argentina
- 9.6 Middle East and Africa
- 9.6.1 South Africa
- 9.6.2 Saudi Arabia
- 9.6.3 UAE
Chapter 10 Company Profiles
- 10.1 Global Key Players
- 10.1.1 Datel, Inc.
- 10.1.2 IQ- Analog
- 10.1.3 Mouser Electronics, Inc.
- 10.1.4 Microchip Technology Inc.
- 10.1.5 Renesas Electronics Corporation
- 10.2 Regional key players
- 10.2.1 North America
- 10.2.1.1 Analog Devices, Inc.
- 10.2.1.2 Broadcom Inc.
- 10.2.1.3 Cirrus Logic, Inc.
- 10.2.1.4 ON Semiconductor
- 10.2.1.5 Qualcomm Technologies, Inc.
- 10.2.1.6 Skyworks Solutions, Inc.
- 10.2.1.7 Texas Instruments
- 10.2.1.8 Xilinx, Inc.
- 10.2.2 Europe
- 10.2.2.1 Infineon Technologies AG
- 10.2.2.2 NXP Semiconductors
- 10.2.2.3 STMicroelectronics
- 10.2.2.4 ROHM Semiconductor
- 10.2.3 Asia Pacific
- 10.2.3.1 Asahi Kasei Microdevices Corporation
- 10.2.3.2 MediaTek Inc.
- 10.2.3.3 Realtek Semiconductor Corp.
- 10.2.3.4 Samsung Electronics Co., Ltd.
- 10.2.3.5 Avia Semiconductor Ltd.
- 10.2.1 North America

 資料轉換器:市場佔有率分析、產業趨勢與統計資料、成長預測(2026-2031)
 資料轉換器市場:2026-2032年全球市場預測(按轉換器類型、裝置類型、作業系統、最終用戶、分銷管道和應用分類)
 2026年全球資料轉換器積體電路(IC)市場報告
 類比數位轉換器市場報告:按產品類型、解析度、應用和地區分類,2026-2034年
 數據轉換器市場:按類型、應用和地區分類類比數位轉換器市場:按類型、解析度、通道和應用分類-2026-2032年全球市場預測
 全球高速數據轉換器市場規模、佔有率、趨勢和成長分析報告(2026-2034)高速資料轉換器市場:2026年至2032年全球市場預測(依產品類型、解析度、取樣率、架構、介面類型、封裝與應用分類)2026年全球數據轉換器市場報告資料轉換器市場規模、佔有率、趨勢和預測:按類型、取樣率、應用和地區分類(2026-2034 年)