


 |
市場調查報告書
商品編碼
2107347
自願性碳權市場:按項目、交易類型、應用領域、最終用戶和地區分類-趨勢與預測至2035年Voluntary Carbon Credit Market by Project, Type of Transaction, Application Area, End User, and Geographical Regions - Trends and Forecast Till 2035 |
||||||

自願性碳權市場:概述
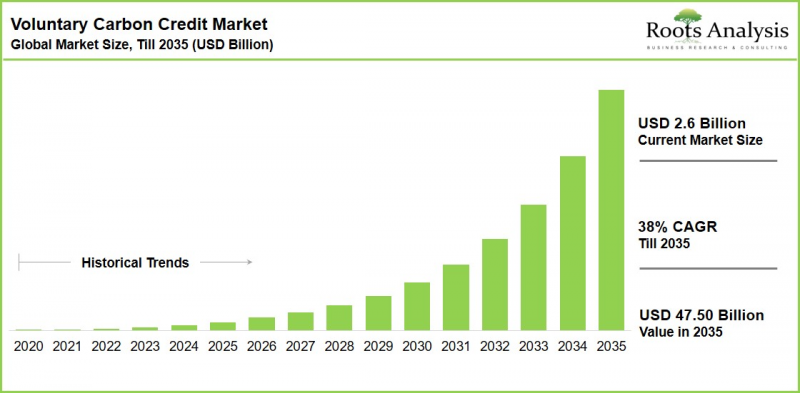
全球自願性碳權市場預計在預測期(至 2035 年)將以驚人的 38% 的複合年成長率成長,從今年的 26 億美元成長到 2035 年的 475 億美元。
自願性碳權市場:成長與趨勢
自願性碳權額度是指透過氣候變遷減緩計畫產生的檢驗的溫室氣體減排或消除量。與政府強制執行的總量管制與交易體系下的合規市場不同,自願碳權額度允許相關人員根據公司的永續發展努力自願追求減排目標。
市場成長的驅動力來自公共和私營部門為減少碳足跡和向永續性轉型所做的持續努力。計畫開發商正在實施一系列舉措,包括植樹造林、重新造林、藍碳、清潔烹飪、清潔用水、森林保護、土地保護和可再生能源計畫。這些努力有助於各組織減少溫室氣體淨排放,同時也有助於生物多樣性保護和實現更廣泛的永續目標(SDGs)。
越來越多的公司將環境、社會和管治(ESG) 目標融入其業務策略,以管理風險、提升企業聲譽並滿足投資者、監管機構和客戶日益成長的期望。此外,包括微軟和亞馬遜在內的許多大型企業正在投資排碳權,以抵消剩餘排放並支持其淨零排放承諾。隨著更多公司推行長期脫碳策略,預計這一趨勢將進一步加劇。
推動成長的因素:促進全球自願性碳權市場擴張的因素
影響市場格局的關鍵趨勢之一是高品質、以自然為基礎的信用額度供應緊張。能夠帶來檢驗的生物多樣性及其附帶效益(例如植樹造林和生態系統修復)的項目,日益受到可用土地有限的限制。此外,更長的開發週期和更嚴格的一致性標準正在擴大供需缺口,這對處於有利地位的開發商和仲介業者無疑是利好。
碳移除信用額度正蓬勃發展,並開始超越傳統的「規避」抵銷機制。直接空氣捕獲(DAC)、生物炭和強化礦化等技術因其永久性和實現淨零排放的高可靠性而獲得溢價。這反映出買家偏好已從「規避」轉向「移除」。
市場挑戰:阻礙進展的主要障礙
儘管市場成長勢頭強勁,但仍面臨結構性挑戰。碳權定價缺乏透明度,加上專案層面的資訊揭露不足,使得買家難以自信地評估其價值和風險。此外,評估和檢驗框架的不完全也引發了人們對特定碳計畫的有效性和完整性的質疑,尤其是其對生物多樣性和當地社區的影響。
供應限制、公眾日益嚴格的審查以及與「綠色清洗」指控相關的法律訴訟,導致一些相關人員即使項目本身可信,也對參與市場猶豫不決。透過標準化的檢驗流程和獨立的監督來解決這些擔憂,對於在未來十年內維持買家信心至關重要。
自願性碳權市場:主要發現
本報告檢驗了自願碳權市場的現狀,並指出了該行業湧現的新機會。主要發現包括:
- 政策基礎設施正在擴展:最近,新加坡政府和世界銀行集團共同啟動了“新加坡碳市場計劃”,旨在建立可靠的全球碳市場基礎設施,並改善開發中國家推出氣候變遷融資的途徑。
- 監管標準日益成熟:歐盟委員會近期通過了全球首個永久性碳移除自願性標準-《碳移除與碳農業條例》(CRCF條例)。這對於提升碳移除信用的公信力而言,是一個重要的里程碑。
- 企業需求正在上升:微軟最近宣布與Indigo Ag達成一項為期12年的協議,購買285萬個土壤碳清除額度。這凸顯了企業為抵銷剩餘排放(包括人工智慧和資料中心營運所產生的排放)所做的努力規模。
- 區域基礎設施正在推動市場擴張:總部位於印度的排碳權平台RenewCred在種子輪資金籌措中籌集了4,250萬印度盧比。這筆資金將用於建立基於數位和科學的註冊系統和標準,反映出新興經濟體對市場基礎設施投資的增加。
- 策略整合正在加速發展:Carbon Direct 收購 Pachama 表明,策略參與者正在加強其端到端能力,以增強其碳移除聲明的可信度和擴充性。
- 新的風險與機會:定價和檢驗的透明度在市場上仍然存在差異。相關人員應密切注意數位化MRV系統的採用情況,將其作為衡量哪些平台和標準正在獲得持續認可的領先指標。
自願性碳權市場細分
市場規模和機會分析是根據以下參數進行細分的:
2020年1月24日 英文:“然後就是‘我會來回倒退’這件事。”
- 可再生能源項目
- 能源效率項目
- 林業和土地利用項目
- 甲烷捕獲與銷毀項目
- 其他項目
按交易類型
- 碳去除
- 碳減排
- 混合交易
按應用程式字段
- 工業部門
- 家庭部門
- 能源領域
- 農業部門
- 其他
最終用戶
- 政府機構和組織
- 非營利組織
- 私人公司
- 個人
按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 法國
- 德國
- 義大利
- 西班牙
- 英國
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 紐西蘭
- 亞太其他地區
- 中東和非洲
- 埃及
- 伊朗
- 伊拉克
- 以色列
- 沙烏地阿拉伯
- 南非
- 阿拉伯聯合大公國
- 拉丁美洲
- 阿根廷
- 巴西
- 其他拉丁美洲
自願性碳權市場:關鍵市場細分洞察
可再生能源項目正在推動市場發展。
根據我們的市場評估,可再生能源項目預計將佔據自願性碳權市場最大的佔有率。其主導地位主要歸功於其測量和檢驗的複雜性較低、前期週期較短以及資金籌措潛力高於基於自然或人工的碳清除方式。成熟的基準調查方法和持續測量降低了檢驗時間和審計成本,從而縮短了從專案運作到發放碳權的時間。
另一方面,林業和土地利用項目領域預計在預測期內將錄得最高的複合年成長率。這主要是由於森林管理在透過遏制森林砍伐和森林劣化來增加碳固存方面發揮的作用,以及其在緩解氣候變遷和生物多樣性喪失方面所做出的貢獻。
混合交易板塊佔比最大。
我們的預測表明,將碳移除信用額度和碳減排信用額度整合於單一投資組合中的混合交易將佔據最大的市場佔有率。此優點源自於其能夠同時滿足企業淨零排放策略中「短期減排」與「長期消除剩餘排放」的雙重需求。此外,混合交易還能降低採購複雜性並縮短實質審查週期。
預計在預測期內,碳移除交易將以相對較高的複合年成長率成長。這一成長主要得益於企業淨零排放承諾的增加、有利的監管政策調整,以及對植樹造林、生物炭和捕碳封存(CCS)生質能源等碳移除額度投資的增加。
產業部門佔比最大。
我們的市場分析表明,產業部門細分市場佔據最大的市場佔有率,預計在整個預測期內將保持其主導地位。這一最大佔有率主要歸因於該行業持續依賴高能耗運營,以及為降低監管風險而不斷增加對碳抵消的投資。在電氣化和氫能等替代方案尚無法大規模解決製程排放問題的領域,這一趨勢尤其顯著。
未來幾年,能源子產業預計將在預測期內實現最高的複合年成長率。這一最高成長主要得益於該行業龐大的範圍1、2和3剩餘排放量,以及其作為主要排放源和專案開發商的雙重角色。
北美市佔率最大。
我們的市場預測顯示,北美將繼續保持在全球自願性碳權市場收入的最大佔有率。該地區,尤其是美國,擁有完善的金融基礎設施和多個大規模碳交易市場,推動了活躍的交易。此外,企業對永續性和淨零排放目標的日益重視,也帶動了投資的成長,這是該地區佔最大佔有率的主要原因。
亞太地區蘊藏著長期的發展機會。
我們的市場預測顯示,亞太地區在預測期內可望維持較高的複合年成長率。這一可觀的成長得益於中國、印度和其他亞洲國家廣泛的可再生能源項目、大規模的森林砍伐治理舉措以及企業在永續發展方面日益增強的投入。此外,有利的政策框架和區域間合作也進一步促進了市場整合和跨境貿易。
自願性碳權市場主要參與者的例子
- 3Degrees
- Climate Impact Partners
- ClimateSeed
- Cool Effect
- Earthly
- Ecologi Impact Funds
- EKI Energy Services
- First Climate
- Green Wedge
- Greenfleet
- natureOffice
- Solaxy Group
- South Pole
- The Carbon Collective Company
專家訪談與業界考察
本研究提出的觀點和見解是基於與該領域多位相關人員的討論。這份自願性碳權市場報告包含了與以下相關人員的詳細訪談記錄:
- 創辦人,小型企業,阿拉伯聯合大公國
- 波蘭,中小企業,執行董事
- 瑞士,大型企業,全球自然解決方案資深總監
- 某德國中型公司國際銷售團隊負責人
- 英國領先的小規模企業,企業創新
- 負責法國中小企業的國際業務拓展和策略業務夥伴關係。
- 澳洲小規模企業夥伴關係協調員
此外,本市場報告還包含以下第三方討論的會議記錄:
- 美國企業碳定價與市場資深首席分析師
- 英國中小企業政策與合作總監
- 英國某中型公司高階策略市場編輯(碳排放領域)
- 某英國中小企業的首席評級官
- 瑞士一家大型公司全球環境產品部門負責人
- 瑞士某大型企業氣候政策、金融與碳市場總監
- 美國一家領先公司的執行董事兼碳市場主管
自願性碳權市場:研究範圍
- 市場規模和機會分析:本報告對自願性碳權市場進行了詳細分析,重點關注項目、交易模式、應用領域、最終用戶和地區等關鍵市場細分。
- 自願性碳權市場狀況:這是對市場狀況的詳細評估,包括項目類型、信用標準、檢驗調查方法、與註冊機構的隸屬關係等參數信息,以及根據成立年份、公司規模和總部所在地對市場參與者的分析。
- 公司簡介:提供自願碳權額度的領先公司的詳細簡介,包括其成立年份、總部所在地、公司規模、投資組合和主要舉措等資訊。
- 資金籌措和投資分析:這是對該領域資金和投資的詳細分析,基於幾個相關參數,例如資金籌措年份、資金籌措資金籌措、投資金額、資金籌措用途、地區、最活躍的參與企業和主要投資者。
- 大型製藥企業的舉措:詳細分析排碳權在製藥行業中的作用,以及Astra Zeneca、拜耳、葛蘭素史克、諾華、輝瑞和武田製藥等領先公司正在實施的策略、投資和碳抵消措施。
- 市場影響分析:本報告分析了影響市場成長的各種因素,包括促進因素、阻礙因素、機會和挑戰。
- 波特五力分析:該分析定性地考察了該領域的五種競爭力量:新進入者的威脅、買方的議價能力、供應商的議價能力、替代品的威脅以及現有競爭對手之間的競爭。
目錄
第1章 背景
第2章:調查方法
第3章 市場動態
第4章 宏觀經濟指標
第5章執行摘要
第6章:引言
第7章 市場狀況
第8章:企業競爭力分析
第9章:公司簡介
- 章節概要
- 自願性碳權市場的主要參與者
- EKI Energy Services
- 3Degrees
- Climate Impact Partners
- Cool Effect
- Ecologi Impact Funds
- natureOffice
- Solaxy Group
- ClimateSeed
- Earthly
- First Climate
- Green Wedge
- Greenfleet
- South Pole
- The Carbon Collective Company
第10章:資金籌措與投資
第11章:案例研究:一家大型製藥公司的舉措
第12章 市場影響分析
第13章:波特五力模型分析
第14章:全球自願性碳權市場
第15章:自願碳權市場(依項目分類)
第16章:自願碳權市場(依交易類型分類)
第17章 自願性碳權市場(依應用領域分類)
第18章:自願性碳權市場(最終用戶參與)
第19章 自願碳權市場(依地區分類)
第20章 自願性碳權市場機會分析:北美
第21章 自願碳權市場機會分析:歐洲
第22章 自願性碳權市場機會分析:亞太地區
第23章 自願性碳權市場機會分析:拉丁美洲
第24章 自願碳權市場機會分析:中東和北非
第25章 結論
第26章:高階主管洞察
第27章附錄一:表格形式數據
第28章 附錄二:公司與組織列表
VOLUNTARY CARBON CREDIT MARKET: OVERVIEW
As per Roots Analysis, the global voluntary carbon credit market is estimated to grow from USD 2.6 billion in the current year to USD 47.5 billion by 2035, at an impressive CAGR of 38%, during the forecast period, till 2035.
Voluntary Carbon Credit Market: Growth and Trends
Voluntary carbon credits are verified reductions or removals of greenhouse gas emissions generated through climate mitigation projects. Unlike compliance markets, which operate under government-mandated cap-and-trade schemes, this segment allows stakeholders to voluntarily pursue emission reduction goals in line with corporate sustainability commitments.
Growth in the market is being driven by sustained efforts to reduce carbon footprints and transition toward sustainability across both public and private sectors. Project developers are implementing a wide range of climate mitigation initiatives, including afforestation, reforestation, blue carbon, clean cooking, clean water access, forest conservation, land protection, and renewable energy projects. These initiatives help organizations reduce their net greenhouse gas emissions while contributing to biodiversity conservation and broader sustainable development goals.
A growing number of companies are integrating environmental, social, and governance (ESG) goals into their business strategies to manage risk, enhance corporate reputation, and meet the rising expectations of investors, regulators, and customers. In addition, many large organizations, including Microsoft and Amazon, are investing in carbon credits to offset residual emissions and support their net-zero commitments. This trend is expected to strengthen as more companies advance their long-term decarbonization strategies.
Growth Drivers: Factors Fueling Expansion of the Global Voluntary Carbon Credit Market
A key trend shaping the market is the tightening supply of high-quality, nature-based credits. Projects offering verifiable biodiversity and co-benefits, such as afforestation and ecosystem restoration, face growing constraints from limited land availability. Further, extended development timelines and stricter integrity standards are resulting in a widening demand-supply gap that favors well-positioned developers and intermediaries.
Carbon removal credits are gaining momentum and beginning to outpace traditional avoidance-based offsets. Approaches such as direct air capture, biochar, and enhanced mineralization are commanding premium valuations owing to their permanence and higher credibility within net-zero pathways. This reflects a clear shift in buyer preference from avoidance toward removal.
Market Challenges: Critical Barriers Hindering Progress
Despite strong growth momentum, the market continues to face structural challenges. Limited transparency in carbon credit pricing, combined with insufficient project-level disclosure, makes it difficult for buyers to assess value and risk with confidence. Inadequate evaluation and verification frameworks have also raised doubts regarding the efficacy and integrity of certain carbon projects, particularly with respect to their impact on biodiversity and local communities.
Supply constraints, mounting public scrutiny, and legal action related to greenwashing claims are discouraging some stakeholders from participating in the market, even where the underlying projects are credible. Addressing these concerns through standardized verification protocols and independent oversight will be essential to sustaining buyer confidence over the coming decade.
Voluntary Carbon Credit Market: Key Insights
The report examines the current state of the voluntary carbon credit market and identifies emerging opportunities within the industry. Some of the key findings include:
- Policy infrastructure is Scaling Up: Recently, the Singapore government and the World Bank Group jointly launched the Singapore Carbon Markets Program to build high-integrity global carbon market infrastructure and improve developing countries' access to climate finance.
- Regulatory Standards are Maturing: Recently, the European Commission adopted the world's first voluntary standard for permanent carbon removals under the Carbon Removals and Carbon Farming (CRCF) Regulation, marking a significant milestone for removal-credit integrity.
- Corporate Demand is Increasing: Recently, Microsoft announced a 12-year agreement for 2.85 million soil carbon removal credits from Indigo Ag, underscoring the scale of corporate commitments being made to offset residual emissions, including those tied to AI and data center operations.
- Regional Infrastructure is Supporting Market Expansion: RenewCred, an India-based carbon credit platform, raised INR 42.5 million in seed funding round. The fund will be utilized to build a digital, science-based registry and standard, reflecting growing investment in market infrastructure across emerging economies.
- Strategic Consolidation is Gaining Momentum: Carbon Direct's acquisition of Pachama illustrates how strategic players are strengthening end-to-end capabilities to improve the integrity and scalability of carbon removal claims.
- Emerging Risk and Opportunity: Transparency in pricing and verification remains uneven across the market. Stakeholders should track the adoption of digital MRV systems as a leading indicator of which platforms and standards achieve durable credibility.
Voluntary Carbon Credit Market Segments
The market sizing and opportunity analysis has been segmented across the following parameters:
By Project
- Renewable Energy Projects
- Energy Efficiency Projects
- Forestry and Land Use Projects
- Methane Capture and Destruction Projects
- Other Projects
By Type of Transaction
- Carbon Removal
- Carbon Reduction
- Mixed Transactions
By Application Area
- Industrial Sector
- Household Sector
- Energy Sector
- Agriculture Sector
- Other Application Areas
By End User
- Government Agencies / Organizations
- Non-Profit Organizations
- Private Companies
- Individuals
By Geographical Regions
- North America
- US
- Canada
- Mexico
- Europe
- France
- Germany
- Italy
- Spain
- UK
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- Egypt
- Iran
- Iraq
- Israel
- Saudi Arabia
- South Africa
- United Arab Emirates
- Latin America
- Argentina
- Brazil
- Rest of Latin America
Voluntary Carbon Credit Market: Key Segmentation Insights
Renewable Energy Projects Lead the Market
Based on our market assessment, the renewable energy projects segment is expected to account for the highest share of the voluntary carbon credit market. This leadership is primarily driven by lower measurement and verification complexity, faster delivery timelines, and greater bankability relative to nature-based and engineered removal approaches. Established baseline methodologies and continuous metering reduce verification time and audit costs, shortening the interval between project commissioning and credit issuance.
On the other hand, the forestry and land use projects segment is projected to witness the highest CAGR during the forecast period. This is primarily attributed to the role of forest management in increasing carbon absorption through the control of deforestation and forest degradation, alongside its contribution to mitigating climate change and biodiversity loss.
Mixed Transactions Segment Holds Highest Share
According to our projections, mixed transactions, which combine carbon removal and carbon reduction credits within a single portfolio, hold the highest share of the market. This dominance is due to their ability to address the dual requirements of corporate net-zero strategies, namely near-term emissions avoidance and long-term residual emissions removal. Moreover, mixed transactions also reduce procurement complexity and shorten due diligence cycles.
Carbon removal transactions are likely to grow at a relatively higher CAGR during the forecast period. This growth is driven by rising corporate net-zero pledges, favorable regulatory alignment, and growing investment in removal-based credits such as afforestation, biochar, and bioenergy with carbon capture and storage.
Industrial Sector Segment Holds Highest Share
Based on our market analysis, the industrial sector sub-segment occupies the highest share of the market and is likely to remain dominant during the forecast period. This highest share is attributed to the sector's continued reliance on energy-intensive operations and its growing investments in carbon offset initiatives to mitigate regulatory risk, particularly where alternatives such as electrification or hydrogen cannot yet address process emissions at scale.
In the coming years, the energy sector sub-segment is expected to grow at a higher CAGR during the forecast period. This highest growth is driven by its massive residual Scope 1, 2, and 3 emissions and its dual role as both a major emitter and project developer.
North America Holds the Highest Share
According to our market projections, North America is expected to retain highest share of the global voluntary carbon credit market revenue. The region's advanced financial infrastructure and several large-scale carbon marketplaces, particularly in the US, facilitate active trading. Further, increasing investment, supported by growing corporate commitments to sustainability and net-zero targets are the key reasons for highest share of this region.
Asia-Pacific Offers Long-Term Opportunity
According to our market projections, Asia-Pacific is expected to grow at a higher CAGR during the forecast period. This lucrative growth is driven by extensive renewable energy projects, large-scale reforestation initiatives, and increasing corporate sustainability commitments across China, India, and other Asian countries. Supportive policy frameworks and regional collaborations are further reinforcing market integration and cross-border trading.
Example Players in Voluntary Carbon Credit Market
- 3Degrees
- Climate Impact Partners
- ClimateSeed
- Cool Effect
- Earthly
- Ecologi Impact Funds
- EKI Energy Services
- First Climate
- Green Wedge
- Greenfleet
- natureOffice
- Solaxy Group
- South Pole
- The Carbon Collective Company
Expert Interview and Industry Insights
The opinions and insights presented in this study were influenced by discussions conducted with multiple stakeholders in this domain. The voluntary carbon credit market report features detailed transcripts of interviews conducted with the following individuals:
- Founder, Small Company, UAE
- Managing Director, Small Company, Poland
- Global Senior Director of Nature Based Solutions, Very Large Company, Switzerland
- Team Lead Sales International, Mid-sized Company, Germany
- Enterprise Innovation Lead, Small Company, UK
- International Business Development and Strategic Business Partnerships, Small Company, France
- Partnerships Coordinator, Small Company, Australia
In addition, the market report includes transcripts of the following other third-party discussions:
- Senior Principal Analyst, Carbon Pricing and Markets, Large Company, US
- Director of Policy and Partnerships, Small Company, UK
- Senior Strategic Market Editor - Carbon, Mid-sized Company, UK
- Chief Ratings Officer, Small Company, UK
- Global Head of Environmental Products, Large Company, Switzerland
- Director, Climate Policy, Finance & Carbon Markets, Large Company, Switzerland
- Managing Director and Head of Carbon Markets, Large Company, US
Voluntary Carbon Credit MARKET: RESEARCH COVERAGE
- Market Sizing and Opportunity Analysis: The report features an in-depth analysis of the voluntary carbon credit market, focusing on key market segments, including project, type of transaction, application area, end user, and geographical regions.
- Voluntary Carbon Credit Landscape: A detailed assessment of the overall market landscape, featuring information on parameters such as project type, credit standard, verification methodology, and registry affiliation, along with an analysis of market players based on year of establishment, company size, and location of headquarters.
- Company Profiles: In-depth profiles of prominent players engaged in offering voluntary carbon credits, featuring information on their year of establishment, location of headquarters, company size, portfolio, and key initiatives.
- Funding and Investments Analysis: A detailed analysis of the funding and investments made in this domain, based on several relevant parameters, such as year of funding, type of funding, amount invested, purpose of funding, geography, most active players and leading investors.
- Big Pharma Initiatives: A detailed analysis of carbon credits role in the pharmaceutical industry, strategies, investments, and carbon offset initiatives undertaken by major players, including AstraZeneca, Bayer, GSK, Novartis, Pfizer, and Takeda Pharmaceutical.
- Market Impact Analysis: The report analyzes various factors such as drivers, restraints, opportunities, and challenges affecting market growth.
- Porter's Five Forces Analysis: A qualitative analysis of five competitive forces in this domain, namely, threats of new entrants, bargaining power of buyers, bargaining power of providers, threat of substitute products, and rivalry among existing competitors.
Key Questions Answered in this Report
- Which are the leading companies in the voluntary carbon credit market?
- Which region dominates the voluntary carbon credit market?
- What are the key trends observed in the voluntary carbon credit market?
- What factors are likely to influence the evolution of this market?
- What are the primary challenges faced by voluntary carbon credit developers?
- What is the current and future market size?
- What is the CAGR of this market?
- How is the current and future market opportunity likely to be distributed across key market segments?
Reasons to Buy this Report
- The report provides a comprehensive market analysis, offering detailed revenue projections of the overall market and its specific sub-segments. This information is valuable to both established market leaders and emerging entrants.
- The report offers stakeholders a comprehensive overview of the market, including key drivers, barriers, opportunities, and challenges. This information empowers stakeholders to stay abreast of market trends and make data-driven decisions to capitalize on growth prospects.
- The report can aid businesses in identifying future opportunities in any sector. It also helps in understanding if those opportunities are worth pursuing.
- The report helps in identifying customer demand by understanding the needs, preferences, and behavior of the target audience in order to tailor products or services effectively.
- The report equips new entrants with requisite information regarding a particular market to help them build successful business strategies.
- The report allows for more effective communication with the audience and in building strong business relations.
Additional Benefits
- Complementary Excel Data Packs for all Analytical Modules in the Report
- 15% Free Content Customization
- Detailed Report Walkthrough Session with Research Team
- Free Updated report if the report is 6-12 months old or older
TABLE OF CONTENTS
1. BACKGROUND
- 1.1. Context
- 1.2. Project Objectives
2. RESEARCH METHODOLOGY
- 2.1. Chapter Overview
- 2.2. Research Assumptions
- 2.2.1. Market Landscape and Market Trends
- 2.2.2. Market Forecast and Opportunity Analysis
- 2.2.3. Comparative Analysis
- 2.3. Database Building
- 2.3.1. Data Collection
- 2.3.2. Data Validation
- 2.3.3. Data Analysis
- 2.4. Project Methodology
- 2.4.1. Secondary Research
- 2.4.1.1. Annual Reports
- 2.4.1.2. Academic Research Papers
- 2.4.1.3. Company Websites
- 2.4.1.4. Investor Presentations
- 2.4.1.5. Regulatory Filings
- 2.4.1.6. White Papers
- 2.4.1.7. Industry Publications
- 2.4.1.8. Conferences and Seminars
- 2.4.1.9. Government Portals
- 2.4.1.10. Media and Press Releases
- 2.4.1.11. Newsletters
- 2.4.1.12. Industry Databases
- 2.4.1.13. Roots Proprietary Databases
- 2.4.1.14. Paid Databases and Sources
- 2.4.1.15. Social Media Portals
- 2.4.1.16. Other Secondary Sources
- 2.4.2. Primary Research
- 2.4.2.1. Types of Primary Research
- 2.4.2.1.1. Qualitative Research
- 2.4.2.1.2. Quantitative Research
- 2.4.2.1.3. Hybrid Approach
- 2.4.2.2. Advantages of Primary Research
- 2.4.2.3. Techniques for Primary Research
- 2.4.2.3.1. Interviews
- 2.4.2.3.2. Surveys
- 2.4.2.3.3. Focus Groups
- 2.4.2.3.4. Observational Research
- 2.4.2.3.5. Social Media Interactions
- 2.4.2.4. Key Opinion Leaders Considered in Primary Research
- 2.4.2.4.1. Company Executives (CXOs)
- 2.4.2.4.2. Board of Directors
- 2.4.2.4.3. Company Presidents and Vice Presidents
- 2.4.2.4.4. Research and Development Heads
- 2.4.2.4.5. Technical Experts
- 2.4.2.4.6. Subject Matter Experts
- 2.4.2.4.7. Scientists
- 2.4.2.4.8. Doctors and Other Healthcare Providers
- 2.4.2.5. Ethics and Integrity
- 2.4.2.5.1. Research Ethics
- 2.4.2.5.2. Data Integrity
- 2.4.2.1. Types of Primary Research
- 2.4.3. Analytical Tools and Databases
- 2.4.1. Secondary Research
- 2.5. Robust Quality Control
3. MARKET DYNAMICS
- 3.1. Chapter Overview
- 3.2. Forecast Methodology
- 3.2.1. Top-down Approach
- 3.2.2. Bottom-up Approach
- 3.2.3. Hybrid Approach
- 3.3. Market Assessment Framework
- 3.3.1. Total Addressable Market (TAM)
- 3.3.2. Serviceable Addressable Market (SAM)
- 3.3.3. Serviceable Obtainable Market (SOM)
- 3.3.4. Currently Acquired Market (CAM)
- 3.4. Forecasting Tools and Techniques
- 3.4.1. Qualitative Forecasting
- 3.4.2. Correlation
- 3.4.3. Regression
- 3.4.4. Extrapolation
- 3.4.5. Convergence
- 3.4.6. Sensitivity Analysis
- 3.4.7. Scenario Planning
- 3.4.8. Data Visualization
- 3.4.9. Time Series Analysis
- 3.4.10. Forecast Error Analysis
- 3.5. Key Considerations
- 3.5.1. Demographics
- 3.5.2. Government Regulations
- 3.5.3. Reimbursement Scenarios
- 3.5.4. Market Access
- 3.5.5. Supply Chain
- 3.5.6. Industry Consolidation
- 3.5.7. Pandemic / Unforeseen Disruptions Impact
- 3.6. Limitations
4. MACRO-ECONOMIC INDICATORS
- 4.1. Chapter Overview
- 4.2. Market Dynamics
- 4.2.1. Time Period
- 4.2.1.1. Historical Trends
- 4.2.1.2. Current and Forecasted Estimates
- 4.2.2. Currency Coverage
- 4.2.2.1. Major Currencies Affecting the Market
- 4.2.2.2. Factors Affecting Currency Fluctuations
- 4.2.2.3. Impact of Currency Fluctuations on the Industry
- 4.2.3. Foreign Currency Exchange Rate
- 4.2.3.1. Impact of Foreign Exchange Rate Volatility on the Market
- 4.2.3.2. Strategies for Mitigating Foreign Exchange Risk
- 4.2.4. Recession
- 4.2.4.1. Assessment of Current Economic Conditions and Potential Impact on the Market
- 4.2.4.2. Historical Analysis of Past Recessions and Lessons Learnt
- 4.2.5. Inflation
- 4.2.5.1. Measurement and Analysis of Inflationary Pressures in the Economy
- 4.2.5.2. Potential Impact of Inflation on the Market Evolution
- 4.2.6. Interest Rates
- 4.2.6.1. Interest Rates and Their Impact on the Market
- 4.2.6.2. Strategies for Managing Interest Rate Risk
- 4.2.7. Commodity Flow Analysis
- 4.2.7.1. Type of Commodity
- 4.2.7.2. Origins and Destinations
- 4.2.7.3. Values and Weights
- 4.2.7.4. Modes of Transportation
- 4.2.8. Global Trade Dynamics
- 4.2.8.1. Import Scenario
- 4.2.8.2. Export Scenario
- 4.2.8.3. Trade Policies
- 4.2.8.4. Strategies for Mitigating the Risks Associated with Trade Barriers
- 4.2.8.5. Impact of Trade Barriers on the Market
- 4.2.9. War Impact Analysis
- 4.2.9.1. Russian-Ukraine War
- 4.2.9.2. Israel-Hamas War
- 4.2.10. COVID Impact / Related Factors
- 4.2.10.1. Global Economic Impact
- 4.2.10.2. Industry-specific Impact
- 4.2.10.3. Government Response and Stimulus Measures
- 4.2.10.4. Future Outlook and Adaptation Strategies
- 4.2.11. Other Indicators
- 4.2.11.1. Fiscal Policy
- 4.2.11.2. Consumer Spending
- 4.2.11.3. Gross Domestic Product
- 4.2.11.4. Employment
- 4.2.11.5. Taxes
- 4.2.11.6. Stock Market Performance
- 4.2.11.7. Cross Border Dynamics
- 4.2.1. Time Period
- 4.3. Conclusion
5. EXECUTIVE SUMMARY
- 5.1. Executive Summary: Market Landscape
- 5.2. Executive Summary: Market Trends
- 5.3. Executive Summary: Market Forecast and Opportunity Analysis
6. INTRODUCTION
- 6.1. Overview of Carbon Credits
- 6.2. Carbon Credits Issuers
- 6.3. Types of Carbon Credits
- 6.4. Introduction to voluntary carbon credit Market
- 6.5. Factors Impacting the Pricing of Voluntary Carbon Projects
- 6.6. Advantages of Voluntary Carbon
- 6.7. Future Perspectives
7. MARKET LANDSCAPE
- 7.1. Methodology and Key Parameters
- 7.2. Voluntary Carbon Credit Providers: Overall Landscape
- 7.2.1. Analysis by Year of Establishment
- 7.2.2. Analysis by Company Size
- 7.2.3. Analysis by Location of Headquarters (Region)
- 7.2.4. Analysis by Location of Headquarters (Country)
- 7.3. Voluntary Carbon Credit Market: Overall Landscape
- 7.3.1. Analysis by Type of Credit
- 7.3.2. Analysis by Health and Livelihood Credits
- 7.3.3. Analysis by Nature-based Solution Credits
- 7.3.4. Analysis by Sustainable Infrastructure Credits
- 7.3.5. Analysis by End-user
8. COMPANY COMPETITIVENESS ANALYSIS
- 8.1. Chapter Overview
- 8.2. Methodology and Key Parameters
- 8.3. Scoring Criteria
- 8.4. Overview of Peer Groups
- 8.5. Voluntary Carbon Credit Providers: Company Competitiveness Analysis
- 8.5.1. Voluntary Carbon Credit Providers based in North America (Peer Group I)
- 8.5.2. Voluntary Carbon Credit Providers based in Europe (Peer Group II)
- 8.5.3. Voluntary Carbon Credit Providers based in Asia-Pacific and Rest of the World (Peer Group III)
9. COMPANY PROFILES
- 9.1. Chapter Overview
- 9.2. Leading Voluntary Carbon Credit Providers
- 9.2.1. EKI Energy Services
- 9.2.1.1. Company Overview
- 9.2.1.2. Management Team
- 9.2.1.3. Carbon Credit Portfolio
- 9.2.1.4. Financial Information
- 9.2.1.5. Recent Developments and Future Outlook
- 9.2.2. 3Degrees
- 9.2.3. Climate Impact Partners
- 9.2.4. Cool Effect
- 9.2.5. Ecologi Impact Funds
- 9.2.6. natureOffice
- 9.2.7. Solaxy Group
- 9.2.8. ClimateSeed
- 9.2.9. Earthly
- 9.2.10. First Climate
- 9.2.11. Green Wedge
- 9.2.12. Greenfleet
- 9.2.13. South Pole
- 9.2.14. The Carbon Collective Company
- 9.2.1. EKI Energy Services
10. FUNDING AND INVESTMENTS
- 10.1. Chapter Overview
- 10.2. Funding Models
- 10.3. Voluntary Carbon Credit Providers: List of Funding and Investments
- 10.3.1. Analysis of Funding Instances by Year of Funding
- 10.3.2. Analysis of Amount Invested by Year of Funding
- 10.3.3. Analysis by Type of Funding
- 10.3.4. Analysis by Year and Type of Funding
- 10.3.5. Analysis by Amount Invested and Type of Funding
- 10.3.6. Analysis by Purpose of Funding
- 10.3.7. Analysis by Geography
- 10.3.8. Most Active Players: Analysis by Number of Instances
- 10.3.9. Most Active Players: Analysis by Amount Invested
- 10.3.10. Leading Investors: Analysis by Number of Instances
- 10.3.11. Funding and Investment Summary
11. USE CASE STUDY: BIG PHARMA INITIATIVES
- 11.1. Chapter Overview
- 11.2. Role of Carbon Credits in Pharma
- 11.3. Big Pharma Players: Initiatives in Voluntary Carbon Credit Domain
- 11.3.1. AstraZeneca
- 11.3.2. Bayer
- 11.3.3. GSK
- 11.3.4. Novartis
- 11.3.5. Pfizer
- 11.3.6. Takeda Pharmaceutical
12. MARKET IMPACT ANALYSIS
- 12.1. Market Drivers
- 12.2. Market Restraints
- 12.3. Market Opportunities
- 12.4. Market Challenges
13. PORTER'S FIVE FORCES ANALYSIS
- 13.1. Threats of New Entrants
- 13.2. Bargaining Power of Buyers
- 13.3. Bargaining Power of Suppliers
- 13.4. Threats of Substitute Products
- 13.5. Rivalry Among Existing Companies
14. GLOBAL VOLUNTARY CARBON CREDIT MARKET
- 14.1. Assumptions and Methodology
- 14.2. Global Voluntary Carbon Credit Market, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 14.2.1. Roots Analysis Perspective on Market Growth
- 14.2.2. Scenario Analysis
- 14.2.2.1. Conservative Scenario
- 14.2.2.2. Optimistic Scenario
- 14.3. Key Market Segmentations
15. VOLUNTARY CARBON CREDIT MARKET, BY PROJECT
- 15.1. Key Assumptions and Methodology
- 15.2. Voluntary Carbon Credit Market: Distribution by Project
- 15.2.1. Voluntary Carbon Credit Market for Renewable Energy Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 15.2.2. Voluntary Carbon Credit Market for Energy Efficiency Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 15.2.3. Voluntary Carbon Credit Market for Forestry and Land Use Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 15.2.4. Voluntary Carbon Credit Market for Methane Capture and Destruction Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 15.2.5. Voluntary Carbon Credit Market for Other Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 15.3. Data Triangulation and Validation
- 15.3.1. Secondary Sources
- 15.3.2. Primary Sources
16. VOLUNTARY CARBON CREDIT MARKET, BY TYPE OF TRANSACTION
- 16.1. Key Assumptions and Methodology
- 16.2. Voluntary Carbon Credit Market: Distribution by Type of Transaction
- 16.2.1. Voluntary Carbon Credit Market for Carbon Removal, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 16.2.2. Voluntary Carbon Credit Market for Carbon Reduction, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 16.2.3. Voluntary Carbon Credit Market for Mixed Transaction, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 16.3. Data Triangulation and Validation
- 16.3.1. Secondary Sources
- 16.3.2. Primary Sources
17. VOLUNTARY CARBON CREDIT MARKET, BY APPLICATION AREA
- 17.1. Key Assumptions and Methodology
- 17.2. Voluntary Carbon Credit Market: Distribution by Application Area
- 17.2.1. Voluntary Carbon Credit Market for Industrial Sector, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 17.2.2. Voluntary Carbon Credit Market for Household Sector, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 17.2.3. Voluntary Carbon Credit Market for Energy Sector, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 17.2.4. Voluntary Carbon Credit Market for Agriculture Sector, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 17.2.5. Voluntary Carbon Credit Market for Other Application Area, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 17.3. Data Triangulation and Validation
- 17.3.1. Secondary Sources
- 17.3.2. Primary Sources
18. VOLUNTARY CARBON CREDIT MARKET, BY END-USER
- 18.1. Key Assumptions and Methodology
- 18.2. Voluntary Carbon Credit Market: Distribution by End-user
- 18.2.1. Voluntary Carbon Credit Market for Government Agencies / Organizations, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 18.2.2. Voluntary Carbon Credit Market for Non-Profit Organizations, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 18.2.3. Voluntary Carbon Credit Market for Private Companies, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 18.2.4. Voluntary Carbon Credit Market for Individuals, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 18.3. Data Triangulation and Validation
- 18.3.1. Secondary Sources
- 18.3.2. Primary Sources
19. VOLUNTARY CARBON CREDIT MARKET, BY GEOGRAPHICAL REGION
- 19.1. Key Assumptions and Methodology
- 19.2. Voluntary Carbon Credit Market: Distribution by Geographical Regions
- 19.2.1. Voluntary Carbon Credit Market in North America, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.1.1. Voluntary Carbon Credit Market in the US, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.1.2. Voluntary Carbon Credit Market in Canada, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.2. Voluntary Carbon Credit Market in Europe, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.2.1. Voluntary Carbon Credit Market in Germany, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.2.2. Voluntary Carbon Credit Market in France, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.2.3. Voluntary Carbon Credit Market in Italy, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.2.4. Voluntary Carbon Credit Market in Belgium, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.2.5. Voluntary Carbon Credit Market in Austria, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.2.6. Voluntary Carbon Credit Market in Spain, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.2.7. Voluntary Carbon Credit Market in Netherlands, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.2.8. Voluntary Carbon Credit Market in the UK, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.2.9. Voluntary Carbon Credit Market in Rest of the Europe, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.3. Voluntary Carbon Credit Market in Asia-Pacific, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.3.1. Voluntary Carbon Credit Market in China, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.3.2. Voluntary Carbon Credit Market in India, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.3.3. Voluntary Carbon Credit Market in Japan, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.3.4. Voluntary Carbon Credit Market in Indonesia, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.3.5. Voluntary Carbon Credit Market in South Korea, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.3.6. Voluntary Carbon Credit Market in Australia, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.3.7. Voluntary Carbon Credit Market in Rest of the Asia-Pacific, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.4. Voluntary Carbon Credit Market in Latin America, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.4.1. Voluntary Carbon Credit Market in Argentina, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.4.2. Voluntary Carbon Credit Market in Brazil, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.4.3. Voluntary Carbon Credit Market in Mexico, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.4.4. Voluntary Carbon Credit Market in Rest of Latin America, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.5. Voluntary Carbon Credit Market in Middle East and Africa, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.5.1. Voluntary Carbon Credit Market in Iran, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.5.2. Voluntary Carbon Credit Market in Saudi Arabia, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.5.3. Voluntary Carbon Credit Market in UAE, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.5.4. Voluntary Carbon Credit Market in Israel, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.5.5. Voluntary Carbon Credit Market in South Africa, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.5.6. Voluntary Carbon Credit Market in Kuwait, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.5.7. Voluntary Carbon Credit Market in Oman, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.5.8. Voluntary Carbon Credit Market in Rest of the Middle East and Africa, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.2.1. Voluntary Carbon Credit Market in North America, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 19.3. Voluntary Carbon Credit Market, By Geographical Regions: Market Dynamics Assessment
- 19.3.1. Penetration-Growth (P-G) Matrix
- 19.3.2. Market Movement Analysis
- 19.4. Data Triangulation and Validation
- 19.4.1. Secondary Sources
- 19.4.2. Primary Sources
20. VOLUNTARY CARBON CREDIT MARKET OPPORTUNITY ANALYSIS: NORTH AMERICA
- 20.1. Voluntary Carbon Credit Market in North America: Distribution by Project
- 20.1.1. Voluntary Carbon Credit Market in North America for Renewable Energy Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 20.1.2. Voluntary Carbon Credit Market in North America for Energy Efficiency Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 20.1.3. Voluntary Carbon Credit Market in North America for Forestry and Land Use Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 20.1.4. Voluntary Carbon Credit Market in North America for Methane Capture and Destruction Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 20.1.5. Voluntary Carbon Credit Market in North America for Other Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 20.2. Voluntary Carbon Credit Market in North America: Distribution by Type of Transaction
- 20.2.1. Voluntary Carbon Credit Market in North America for Carbon Removal, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 20.2.2. Voluntary Carbon Credit Market in North America for Carbon Reduction, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 20.2.3. Voluntary Carbon Credit Market in North America for Mixed Transaction, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 20.3. Voluntary Carbon Credit Market in North America: Distribution by Application Area
- 20.3.1. Voluntary Carbon Credit Market in North America for Industrial Sector, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 20.3.2. Voluntary Carbon Credit Market in North America for Household Sector, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 20.3.3. Voluntary Carbon Credit Market in North America for Energy Sector, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 20.3.4. Voluntary Carbon Credit Market in North America for Agriculture Sector, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 20.3.5. Voluntary Carbon Credit Market in North America for Other Application Area, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 20.4. Voluntary Carbon Credit Market in North America: Distribution by End-user
- 20.4.1. Voluntary Carbon Credit Market in North America for Government Agencies / Organizations, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 20.4.2. Voluntary Carbon Credit Market in North America for Non-Profit Organizations, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 20.4.3. Voluntary Carbon Credit Market in North America for Private Companies, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 20.4.4. Voluntary Carbon Credit Market in North America for Individuals, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
21. VOLUNTARY CARBON CREDIT MARKET OPPORTUNITY ANALYSIS: EUROPE
- 21.1. Voluntary Carbon Credit Market in Europe: Distribution by Project
- 21.1.1. Voluntary Carbon Credit Market in Europe for Renewable Energy Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 21.1.2. Voluntary Carbon Credit Market in Europe for Energy Efficiency Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 21.1.3. Voluntary Carbon Credit Market in Europe for Forestry and Land Use Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 21.1.4. Voluntary Carbon Credit Market in Europe for Methane Capture and Destruction Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 21.1.5. Voluntary Carbon Credit Market in Europe for Other Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 21.2. Voluntary Carbon Credit Market in Europe: Distribution by Type of Transaction
- 21.2.1. Voluntary Carbon Credit Market in Europe for Carbon Removal, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 21.2.2. Voluntary Carbon Credit Market in Europe for Carbon Reduction, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 21.2.3. Voluntary Carbon Credit Market in Europe for Mixed Transaction, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 21.3. Voluntary Carbon Credit Market in Europe: Distribution by Application Area
- 21.3.1. Voluntary Carbon Credit Market in Europe for Industrial Sector, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 21.3.2. Voluntary Carbon Credit Market in Europe for Household Sector, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 21.3.3. Voluntary Carbon Credit Market in Europe for Energy Sector, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 21.3.4. Voluntary Carbon Credit Market in Europe for Agriculture Sector, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 21.3.5. Voluntary Carbon Credit Market in Europe for Other Application Area, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 21.4. Voluntary Carbon Credit Market in Europe: Distribution by End-user
- 21.4.1. Voluntary Carbon Credit Market in Europe for Government Agencies / Organizations, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 21.4.2. Voluntary Carbon Credit Market in Europe for Non-Profit Organizations, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 21.4.3. Voluntary Carbon Credit Market in Europe for Private Companies, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 21.4.4. Voluntary Carbon Credit Market in Europe for Individuals, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
22. VOLUNTARY CARBON CREDIT MARKET OPPORTUNITY ANALYSIS: ASIA-PACIFIC
- 22.1. Voluntary Carbon Credit Market in Asia-Pacific: Distribution by Project
- 22.1.1. Voluntary Carbon Credit Market in Asia-Pacific for Renewable Energy Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 22.1.2. Voluntary Carbon Credit Market in Asia-Pacific for Energy Efficiency Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 22.1.3. Voluntary Carbon Credit Market in Asia-Pacific for Forestry and Land Use Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 22.1.4. Voluntary Carbon Credit Market in Asia-Pacific for Methane Capture and Destruction Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 22.1.5. Voluntary Carbon Credit Market in Asia-Pacific for Other Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 22.2. Voluntary Carbon Credit Market in Asia-Pacific: Distribution by Type of Transaction
- 22.2.1. Voluntary Carbon Credit Market in Asia-Pacific for Carbon Removal, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 22.2.2. Voluntary Carbon Credit Market in Asia-Pacific for Carbon Reduction, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 22.2.3. Voluntary Carbon Credit Market in Asia-Pacific for Mixed Transaction, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 22.3.1. Voluntary Carbon Credit Market in Asia-Pacific for Industrial Sector, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 22.3.2. Voluntary Carbon Credit Market in Asia-Pacific for Household Sector, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 22.3.3. Voluntary Carbon Credit Market in Asia-Pacific for Energy Sector, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 22.3.4. Voluntary Carbon Credit Market in Asia-Pacific for Agriculture Sector, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 22.3.5. Voluntary Carbon Credit Market in Asia-Pacific for Other Application Area, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 22.4. Voluntary Carbon Credit Market in Asia-Pacific: Distribution by End-user
- 22.4.1. Voluntary Carbon Credit Market in Asia-Pacific for Government Agencies / Organizations, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 22.4.2. Voluntary Carbon Credit Market in Asia-Pacific for Non-Profit Organizations, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 22.4.3. Voluntary Carbon Credit Market in Asia-Pacific for Private Companies, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 22.4.4. Voluntary Carbon Credit Market in Asia-Pacific for Individuals, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
23. VOLUNTARY CARBON CREDIT MARKET OPPORTUNITY ANALYSIS: LATIN AMERICA
- 23.1. Voluntary Carbon Credit Market in Latin America: Distribution by Project
- 23.1.1. Voluntary Carbon Credit Market in Latin America for Renewable Energy Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 23.1.2. Voluntary Carbon Credit Market in Latin America for Energy Efficiency Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 23.1.3. Voluntary Carbon Credit Market in Latin America for Forestry and Land Use Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 23.1.4. Voluntary Carbon Credit Market in Latin America for Methane Capture and Destruction Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 23.1.5. Voluntary Carbon Credit Market in Latin America for Other Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 23.2. Voluntary Carbon Credit Market in Latin America: Distribution by Type of Transaction
- 23.2.1. Voluntary Carbon Credit Market in Latin America for Carbon Removal, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 23.2.2. Voluntary Carbon Credit Market in Latin America for Carbon Reduction, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 23.2.3. Voluntary Carbon Credit Market in Latin America for Mixed Transaction, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 23.3. Voluntary Carbon Credit Market in Latin America: Distribution by Application Area
- 23.3.1. Voluntary Carbon Credit Market in Latin America for Industrial Sector, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 23.3.2. Voluntary Carbon Credit Market in Latin America for Household Sector, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 23.3.3. Voluntary Carbon Credit Market in Latin America for Energy Sector, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 23.3.4. Voluntary Carbon Credit Market in Latin America for Agriculture Sector, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 23.3.5. Voluntary Carbon Credit Market in Latin America for Other Application Area, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 23.4. Voluntary Carbon Credit Market in Latin America: Distribution by End-user
- 23.4.1. Voluntary Carbon Credit Market in Latin America for Government Agencies / Organizations, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 23.4.2. Voluntary Carbon Credit Market in Latin America for Non-Profit Organizations, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 23.4.3. Voluntary Carbon Credit Market in Latin America for Private Companies, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 23.4.4. Voluntary Carbon Credit Market in Latin America for Individuals, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
24. VOLUNTARY CARBON CREDIT MARKET OPPORTUNITY ANALYSIS: MIDDLE EAST AND NORTH AFRICA
- 24.1. Voluntary Carbon Credit Market in Middle East and North Africa: Distribution by Project
- 24.1.1. Voluntary Carbon Credit Market in Middle East and North Africa for Renewable Energy Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 24.1.2. Voluntary Carbon Credit Market in Middle East and North Africa for Energy Efficiency Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 24.1.3. Voluntary Carbon Credit Market in Middle East and North Africa for Forestry and Land Use Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 24.1.4. Voluntary Carbon Credit Market in Middle East and North Africa for Methane Capture and Destruction Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 24.1.5. Voluntary Carbon Credit Market in Middle East and North Africa for Other Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 24.2. Voluntary Carbon Credit Market in Middle East and North Africa: Distribution by Type of Transaction
- 24.2.1. Voluntary Carbon Credit Market in Middle East and North Africa for Carbon Removal, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 24.2.2. Voluntary Carbon Credit Market in Middle East and North Africa for Carbon Reduction, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 24.2.3. Voluntary Carbon Credit Market in Middle East and North Africa for Mixed Transaction, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 24.3. Voluntary Carbon Credit Market in Middle East and North Africa: Distribution by Application Area
- 24.3.1. Voluntary Carbon Credit Market in Middle East and North Africa for Industrial Sector, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 24.3.2. Voluntary Carbon Credit Market in Middle East and North Africa for Household Sector, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 24.3.3. Voluntary Carbon Credit Market in Middle East and North Africa for Energy Sector, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 24.3.4. Voluntary Carbon Credit Market in Middle East and North Africa for Agriculture Sector, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 24.3.5. Voluntary Carbon Credit Market in Middle East and North Africa for Other Application Area, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 24.4. Voluntary Carbon Credit Market in Middle East and North Africa: Distribution by End-user
- 24.4.1. Voluntary Carbon Credit Market in Middle East and North Africa for Government Agencies / Organizations, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 24.4.2. Voluntary Carbon Credit Market in Middle East and North Africa for Non-Profit Organizations, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 24.4.3. Voluntary Carbon Credit Market in Middle East and North Africa for Private Companies, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
- 24.4.4. Voluntary Carbon Credit Market in Middle East and North Africa for Individuals, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035)
25. CONCLUDING REMARKS
26. EXECUTIVE INSIGHTS
27. APPENDIX I: TABULATED DATA
28. APPENDIX II: LIST OF COMPANIES AND ORGANIZATIONS
List of Tables
- Table 7.1 List of Voluntary Carbon Credit Providers
- Table 7.2 List of Voluntary Carbon Credit Providers: Information on Type of Credit
- Table 7.3 List of Voluntary Carbon Credit Providers: Information on Location of Project (Region) and End-users
- Table 9.1 EKI Energy Services: Carbon Credit Portfolio
- Table 9.2 EKI Energy Services: Recent Developments and Future Outlook
- Table 9.3 3Degrees: Carbon Credit Portfolio
- Table 9.4 3Degrees: Recent Developments and Future Outlook
- Table 9.5 Climate Impact Partners: Carbon Credit Portfolio
- Table 9.6 Climate Impact Partners: Recent Developments and Future Outlook
- Table 9.7 Cool Effect: Carbon Credit Portfolio
- Table 9.8 Cool Effect: Recent Developments and Future Outlook
- Table 9.9 Ecologi Impact Funds: Carbon Credit Portfolio
- Table 9.10 Ecologi Impact Funds: Recent Developments and Future Outlook
- Table 9.11 natureOffice: Carbon Credit Portfolio
- Table 9.12 natureOffice: Recent Developments and Future Outlook
- Table 9.13 Solaxy Group: Carbon Credit Portfolio
- Table 9.14 Solaxy Group: Recent Developments and Future Outlook
- Table 9.15 ClimateSeed: Carbon Credit Portfolio
- Table 9.16 Earthly: Carbon Credit Portfolio
- Table 9.17 First Climate: Carbon Credit Portfolio
- Table 9.18 Green Wedge: Carbon Credit Portfolio
- Table 9.19 Greenfleet: Carbon Credit Portfolio
- Table 9.20 South Pole: Carbon Credit Portfolio
- Table 9.21 The Carbon Collective Company: Carbon Credit Portfolio
- Table 10.1 Voluntary Carbon Credit Market: List of Funding and Investments, Since 2020
- Table 34.1 Voluntary Carbon Credit Providers: Distribution by Year of Establishment
- Table 34.2 Voluntary Carbon Credit Providers: Distribution by Company Size
- Table 34.3 Voluntary Carbon Credit Providers: Distribution by Location of Headquarters (Region)
- Table 34.4 Voluntary Carbon Credit Providers: Distribution by Location of Headquarters (Country)
- Table 34.5 Voluntary Carbon Credit: Distribution by Type of Credit
- Table 34.6 Voluntary Carbon Credit: Distribution by Health and Livelihood Credits
- Table 34.7 Voluntary Carbon Credit: Distribution by Nature-based Solution Credits
- Table 34.8 Voluntary Carbon Credit: Distribution by Sustainable Infrastructure Credits
- Table 34.9 Voluntary Carbon Credit: Distribution by End-user
- Table 34.10 EKI Energy Services: Annual Revenues, Since FY 2021 (INR Crore)
- Table 34.11 3Degrees: Annual Revenues, Since FY 2021 (USD Billion)
- Table 34.12 Climate Impact Partners: Annual Revenues, Since FY 2021 (EUR Billion)
- Table 34.13 Cool Effect: Annual Revenues, Since FY 2021 (USD Billion)
- Table 34.14 Ecologi Impact Funds: Annual Revenues, Since FY 2021 (EUR Billion)
- Table 34.15 natureOffice: Annual Revenues, Since FY 2021 (EUR Billion)
- Table 34.16 Solaxy Group: Annual Revenues, Since FY 2021 (USD Billion)
- Table 34.17 Funding and Investments: Cumulative Year-wise Distribution of Funding Instances, Since 2021
- Table 34.18 Funding and Investments: Cumulative Year-wise Distribution of Amount Invested (USD Million), Since 2021
- Table 34.19 Funding and Investments: Distribution by Year of Funding and Amount Invested (USD Million), Since 2021
- Table 34.20 Funding and Investments: Distribution by Type of Funding
- Table 34.21 Funding and Investments: Distribution by Year and Type of Funding, Since 2021
- Table 34.22 Funding and Investments: Distribution by Amount Invested and Type of Funding
- Table 34.23 Funding and Investments: Distribution by Purpose of Funding
- Table 34.24 Funding and Investments: Distribution by Geography
- Table 34.25 Most Active Players: Distribution by Number of Instances
- Table 34.26 Most Active Players: Distribution by Amount Invested (USD Million)
- Table 34.27 Leading Investors: Distribution by Number of Funding Instances
- Table 34.28 Voluntary Carbon Credit Market, Historical Trends (Since 2020) and Forecasted Estimated (Till 2035) (USD Billion)
- Table 34.29 Voluntary Carbon Credit Market, Forecasted Estimated (Till 2035): Conservative Scenario (USD Billion)
- Table 34.30 Voluntary Carbon Credit Market, Forecasted Estimated (Till 2035): Optimistic Scenario (USD Billion)
- Table 34.31 Voluntary Carbon Credit Market: Distribution by Project, 2020, Current Year and 2035
- Table 34.32 Voluntary Carbon Credit Market for Renewable Energy Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.33 Voluntary Carbon Credit Market for Energy Efficiency Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.34 Voluntary Carbon Credit Market for Forestry and Land Use Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.35 Voluntary Carbon Credit Market for Methane Capture and Destruction Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.36 Voluntary Carbon Credit Market for Other Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.37 Voluntary Carbon Credit Market: Distribution by Type of Transaction, 2020, Current Year and 2035
- Table 34.38 Voluntary Carbon Credit Market for Carbon Removal, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.39 Voluntary Carbon Credit Market for Carbon Reduction, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.40 Voluntary Carbon Credit Market for Mixed Transaction, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.41 Voluntary Carbon Credit Market: Distribution by Application Area, 2020, Current Year and 2035
- Table 34.42 Voluntary Carbon Credit Market for Industrial Sector, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.43 Voluntary Carbon Credit Market for Household Sector, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.44 Voluntary Carbon Credit Market for Energy Sector, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.45 Voluntary Carbon Credit Market for Agriculture Sector, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.46 Voluntary Carbon Credit Market for Other Application Area, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.47 Voluntary Carbon Credit Market: Distribution by End-user, 2020, Current Year and 2035
- Table 34.48 Voluntary Carbon Credit Market for Government Agencies / Organizations, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.49 Voluntary Carbon Credit Market for Non-Profit Organizations, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.50 Voluntary Carbon Credit Market for Private Companies, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.51 Voluntary Carbon Credit Market for Individuals, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.52 Voluntary Carbon Credit Market: Distribution by Geographical Regions, 2020, Current Year and 2035
- Table 34.53 Voluntary Carbon Credit Market in North America, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.54 Voluntary Carbon Credit Market in the US, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.55 Voluntary Carbon Credit Market in Canada, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.56 Voluntary Carbon Credit Market in Europe, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.57 Voluntary Carbon Credit Market in Germany, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.58 Voluntary Carbon Credit Market in the France, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.59 Voluntary Carbon Credit Market in Italy, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.60 Voluntary Carbon Credit Market in Belgium, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.61 Voluntary Carbon Credit Market in Austria, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.62 Voluntary Carbon Credit Market in Spain, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.63 Voluntary Carbon Credit Market in Netherlands, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.64 Voluntary Carbon Credit Market in the UK, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.65 Voluntary Carbon Credit Market in Rest of the Europe, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.66 Voluntary Carbon Credit Market in Asia-Pacific, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.67 Voluntary Carbon Credit Market in China, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.68 Voluntary Carbon Credit Market in India, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.69 Voluntary Carbon Credit Market in Japan, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.70 Voluntary Carbon Credit Market in Indonesia, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.71 Voluntary Carbon Credit Market in South Korea, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.72 Voluntary Carbon Credit Market in Australia, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.73 Voluntary Carbon Credit Market in Rest of the Asia-Pacific, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.74 Voluntary Carbon Credit Market in Latin America, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.75 Voluntary Carbon Credit Market in Argentina, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.76 Voluntary Carbon Credit Market in Brazil, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.77 Voluntary Carbon Credit Market in Mexico, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.78 Voluntary Carbon Credit Market in Rest of Latin America, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.79 Voluntary Carbon Credit Market in Middle East and Africa, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.80 Voluntary Carbon Credit Market in Iran, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.81 Voluntary Carbon Credit Market in Saudi Arabia, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.82 Voluntary Carbon Credit Market in UAE, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.83 Voluntary Carbon Credit Market in Israel, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.84 Voluntary Carbon Credit Market in South Africa, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.85 Voluntary Carbon Credit Market in Kuwait, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.86 Voluntary Carbon Credit Market in Oman, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
- Table 34.87 Voluntary Carbon Credit Market in Rest of the Middle East and Africa, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenarios (USD Billion)
List of Figures
- Figure 2.1 Research Methodology: Project Methodology
- Figure 2.2 Research Methodology: Data Sources for Secondary Research
- Figure 2.3 Research Methodology: Robust Quality Control
- Figure 3.1 Market Dynamics: Forecast Methodology
- Figure 3.2 Market Dynamics: Market Assessment Framework
- Figure 4.1 Lessons Learnt from Past Recessions
- Figure 5.1 Executive Summary: Market Landscape
- Figure 5.2 Executive Summary: Market Trends
- Figure 5.3 Executive Summary: Market Forecast and Opportunity Analysis
- Figure 7.1 Voluntary Carbon Credit Providers: Distribution by Year of Establishment
- Figure 7.2 Voluntary Carbon Credit Providers: Distribution by Company Size
- Figure 7.3 Voluntary Carbon Credit Providers: Distribution by Location of Headquarters (Region)
- Figure 7.4 Voluntary Carbon Credit Providers: Distribution by Location of Headquarters (Country)
- Figure 7.5 Voluntary Carbon Credit: Distribution by Type of Credit
- Figure 7.6 Voluntary Carbon Credit: Distribution by Health and Livelihood Credits
- Figure 7.7 Voluntary Carbon Credit: Distribution by Nature-based Solution Credits
- Figure 7.8 Voluntary Carbon Credit: Distribution by Sustainable Infrastructure Credits
- Figure 7.9 Voluntary Carbon Credit: Distribution by End-user
- Figure 8.1 Company Competitiveness Analysis: Voluntary Carbon Credit Providers based in North America
- Figure 8.2 Company Competitiveness Analysis: Voluntary Carbon Credit Providers based in Europe
- Figure 8.3 Company Competitiveness Analysis: Voluntary Carbon Credit Providers based in Asia-Pacific and Rest of the World
- Figure 9.1 EKI Energy Services: Annual Revenues, Since FY 2021 (INR Crore)
- Figure 9.2 3Degrees: Annual Revenues, Since FY 2021 (USD Billion)
- Figure 9.3 Climate Impact Partners: Annual Revenues, Since FY 2021 (EUR Billion)
- Figure 9.4 Cool Effect: Annual Revenues, Since FY 2021 (USD Billion)
- Figure 9.5 Ecologi Impact Funds: Annual Revenues, Since FY 2021 (EUR Billion)
- Figure 9.6 natureOffice: Annual Revenues, Since FY 2021 (EUR Billion)
- Figure 9.7 Solaxy Group: Annual Revenues, Since FY 2021 (USD Billion)
- Figure 10.1 Funding and Investments: Cumulative Year-wise Distribution of Funding Instances, Since 2021
- Figure 10.2 Funding and Investments: Cumulative Year-wise Distribution of Amount Invested (USD Million), Since 2021
- Figure 10.3 Funding and Investments: Distribution by Year of Funding and Amount Invested (USD Million), Since 2021
- Figure 10.4 Funding and Investments: Distribution by Type of Funding
- Figure 10.5 Funding and Investments: Distribution by Year and Type of Funding, Since 2021
- Figure 10.6 Funding and Investments: Distribution by Amount Invested and Type of Funding
- Figure 10.7 Funding and Investments: Distribution by Purpose of Funding
- Figure 10.8 Funding and Investments: Distribution by Geography
- Figure 10.9 Most Active Players: Distribution by Number of Instances
- Figure 10.10 Most Active Players: Distribution by Amount Invested (USD Million)
- Figure 10.11 Leading Investors: Distribution by Number of Funding Instances
- Figure 10.12 Funding and Investment Summary, Since 2021
- Figure 12.1 Voluntary Carbon Credit Market: Growth Drivers
- Figure 12.2 Voluntary Carbon Credit Market: Market Restraints
- Figure 12.3 Voluntary Carbon Credit Market: Market Opportunities
- Figure 12.4 Voluntary Carbon Credit Market: Market Challenges
- Figure 13.1 Porter's Five Forces: Key Parameters
- Figure 13.2 Porter's Five Forces: Harvey Ball Analysis
- Figure 14.1 Voluntary Carbon Credit Market, Historical Trends (Since 2020) and Forecasted Estimated (Till 2035) (USD Billion)
- Figure 14.2 Voluntary Carbon Credit Market, Forecasted Estimated (Till 2035): Conservative Scenario (USD Billion)
- Figure 14.3 Voluntary Carbon Credit Market, Forecasted Estimated (Till 2035): Optimistic Scenario (USD Billion)
- Figure 15.1 Voluntary Carbon Credit Market: Distribution by Project, 2020, Current Year and 2035
- Figure 15.2 Voluntary Carbon Credit Market for Renewable Energy Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 15.3 Voluntary Carbon Credit Market for Energy Efficiency Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 15.4 Voluntary Carbon Credit Market for Forestry and Land Use Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 15.5 Voluntary Carbon Credit Market for Methane Capture and Destruction Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 15.6 Voluntary Carbon Credit Market for Other Projects, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 16.1 Voluntary Carbon Credit Market: Distribution by Type of Transaction, 2020, Current Year and 2035
- Figure 16.2 Voluntary Carbon Credit Market for Carbon Removal, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 16.3 Voluntary Carbon Credit Market for Carbon Reduction, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 16.4 Voluntary Carbon Credit Market for Mixed Transaction, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 17.1 Voluntary Carbon Credit Market: Distribution by Application Area, 2020, Current Year and 2035
- Figure 17.2 Voluntary Carbon Credit Market for Industrial Sector, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 17.3 Voluntary Carbon Credit Market for Household Sector, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 17.4 Voluntary Carbon Credit Market for Energy Sector, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 17.5 Voluntary Carbon Credit Market for Agriculture Sector, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 17.6 Voluntary Carbon Credit Market for Other Application Area, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 18.1 Voluntary Carbon Credit Market: Distribution by End-user, 2020, Current Year and 2035
- Figure 18.2 Voluntary Carbon Credit Market for Government Agencies / Organizations, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 18.3 Voluntary Carbon Credit Market for Non-Profit Organizations, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 18.4 Voluntary Carbon Credit Market for Private Companies, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 18.5 Voluntary Carbon Credit Market for Individuals, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.1 Voluntary Carbon Credit Market: Distribution by Geographical Regions, 2020, Current Year and 2035
- Figure 19.2 Voluntary Carbon Credit Market in North America, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.3 Voluntary Carbon Credit Market in the US, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.4 Voluntary Carbon Credit Market in Canada, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.5 Voluntary Carbon Credit Market in Europe, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.6 Voluntary Carbon Credit Market in Germany, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.7 Voluntary Carbon Credit Market in the France, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.8 Voluntary Carbon Credit Market in Italy, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.9 Voluntary Carbon Credit Market in Belgium, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.10 Voluntary Carbon Credit Market in Austria, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.11 Voluntary Carbon Credit Market in Spain, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.12 Voluntary Carbon Credit Market in Netherlands, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.13 Voluntary Carbon Credit Market in the UK, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.14 Voluntary Carbon Credit Market in Rest of the Europe, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.15 Voluntary Carbon Credit Market in Asia-Pacific, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.16 Voluntary Carbon Credit Market in China, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.17 Voluntary Carbon Credit Market in India, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.18 Voluntary Carbon Credit Market in Japan, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.19 Voluntary Carbon Credit Market in Indonesia, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.20 Voluntary Carbon Credit Market in South Korea, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.21 Voluntary Carbon Credit Market in Australia, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.22 Voluntary Carbon Credit Market in Rest of the Asia-Pacific, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.23 Voluntary Carbon Credit Market in Latin America, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.24 Voluntary Carbon Credit Market in Argentina, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.25 Voluntary Carbon Credit Market in Brazil, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.26 Voluntary Carbon Credit Market in Mexico, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.27 Voluntary Carbon Credit Market in Rest of Latin America, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.28 Voluntary Carbon Credit Market in Middle East and Africa, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.29 Voluntary Carbon Credit Market in Iran, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.30 Voluntary Carbon Credit Market in Saudi Arabia, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.31 Voluntary Carbon Credit Market in UAE, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.32 Voluntary Carbon Credit Market in Israel, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.33 Voluntary Carbon Credit Market in South Africa, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.34 Voluntary Carbon Credit Market in Kuwait, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.35 Voluntary Carbon Credit Market in Oman, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.36 Voluntary Carbon Credit Market in Rest of the Middle East and Africa, Historical Trends (Since 2020) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 19.37 Penetration Growth (P-G) Matrix: Geographical Regions
- Figure 19.38 Market Movement Analysis: Geographical Regions


