


 |
市場調查報告書
商品編碼
2106282
心臟衰竭藥物市場:按心臟衰竭類型、治療方法、分子類型、給藥途徑和地區分類的趨勢和銷售預測(至 2035 年)Heart Failure Drugs Market by Type of Heart Failure, Type of Therapy, Type of Molecule, Route of Administration, Geographical Regions, Sales Forecast - Trends and Forecast Till 2035 |
||||||

心臟衰竭治療市場概覽
根據 Roots Analysis 的研究,全球心臟衰竭治療市場規模預計將從今年的 91.9 億美元成長到 2035 年的 123.1 億美元,在預測期內(到 2035 年)將呈現顯著的複合年成長率(該市場規模僅包括主要用於治療心臟衰竭的藥物)。
心臟衰竭藥物市場:成長與趨勢
心臟衰竭是一種進行性心血管疾病,其特徵是心臟無法泵出足夠的血液來滿足身體的代謝需求。隨著疾病盛行率的不斷上升,製藥公司正致力於開發一系列治療方法,旨在控制體液儲存、改善心臟功能、調節血壓並解決疾病進展的根本原因。根據美國心臟衰竭協會統計,目前約有670萬20歲及以上的美國人患有心臟衰竭,預計到2040年,這一數字將增加至1030萬。
多年來,藥物研發的顯著進展拓寬了心臟衰竭的治療選擇範圍。美國食品藥物管理局(FDA) 已批准多種藥物,包括血管收縮素轉化酵素(ACE) 抑制劑、利尿劑、血管緊張素受體阻斷劑 (ARB)、血管收縮素拮抗劑和BETA阻斷劑。此外,持續的臨床研究和技術創新正在改變治療模式,催生了用於治療先天性心臟病的新一代療法和裝置。特別是血管收縮素受體-腦啡肽酶抑制劑 (ARNI)、鈉-葡萄糖共同輸送體2 (SGLT2) 抑制劑和鹽皮質激素受體阻斷劑,透過靶向與心肌重塑、體液超負荷和神經體液失調相關的多個通路,提供了更廣泛的治療效果。
在製藥公司大力投資研發的推動下,心臟衰竭治療市場持續穩定成長。新型作用機制、聯合治療和先進藥物遞送技術的不斷創新,正在拓展治療選擇,改善患者預後。隨著更多臨床證據的積累,這些先進療法的應用預計將加速,從而為預測期內市場的持續擴張創造顯著機會。
心臟衰竭藥物市場的細分
市場規模和機會分析根據以下參數進行分類:
按類型分類的心臟衰竭
- 慢性心臟衰竭
- 其他
透過治療方法
- 單藥治療
- 聯合治療
依分子類型
- 低分子化合物
- 生物製藥
透過行政途徑
- 口服
- 心肌內部
- 皮下
- 靜脈
- 冠狀動脈內部
按地區
- 北美洲
- 美國
- 加拿大
- 歐洲
- 德國
- 法國
- 英國
- 義大利
- 西班牙
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 其他地區
心臟衰竭治療市場:關鍵細分市場分析
以心臟衰竭類型分類,慢性心臟衰竭目前佔絕對主導地位,預計將佔總銷售額的95%以上。這一主導地位主要歸因於慢性心臟衰竭的高發病率、終身疾病管理的需求以及持續藥物治療以控制症狀和阻止疾病進展的必要性。預計該細分市場在預測期內也將穩定成長。特別是,恩格列淨(Jardiance)於2021年獲批作為心臟衰竭單藥療法,累計到2025年銷售額將達到約44億美元,這充分展現了慢性心臟衰竭治療的巨大商業性潛力。
市場預測顯示,北美今年將佔全球心臟衰竭藥物市場40%以上的佔有率,並持續維持其最大區域市場的地位。該地區受益於完善的醫療保健基礎設施、較高的疾病認知度、有利的保險報銷機制以及對心血管研究的大量投入。尤其值得一提的是,美國正崛起為心臟衰竭藥物研發的重要中心,這得益於以創新主導的監管政策、強大的生物製藥生態系統以及高技能人才的儲備。這些優點使得治療藥物能夠有效率地從早期研發階段推進到商業化階段。
儘管北美預計將在市場佔有率方面佔主導地位,但亞太地區預計到 2035 年將實現最高的成長率。該地區的成長預計將受到人口快速老化、心血管疾病盛行率上升、醫療保健覆蓋範圍擴大以及對藥物創新投資增加的推動。
在阿拉伯聯合大公國(阿拉伯聯合大公國),阿拉伯聯合大公國藥品管理局近期下調了168種藥品的零售價格,預計將改善市場准入狀況。此次降價涵蓋了用於治療慢性心肌功能不全的先進療法,並有望擴大患者獲得創新心臟衰竭藥物的機會。
以分子類型分類,小分子化合物預計今年仍將是領先的分子類別,佔超過95%的市場。其主導地位得益於其確切的療效、口服給藥的優勢以及在心臟衰竭治療中作為標準療法的廣泛應用。 BETABETA阻斷劑、ACE抑制劑、ARB和SGLT2抑制劑等主要藥物類別均展現出顯著的臨床效益,包括降低射血分數降低的心臟衰竭(HFrEF)和射血分數保留的心臟衰竭(HFpEF)患者的死亡率並改善其預後。
同時,生物製藥領域預計在預測期內將以高達52.0%的複合年成長率顯著成長。這一成長被認為主要受精準醫療日益成長的需求驅動。生物製藥有望標靶治療心臟衰竭進展過程中涉及的遺傳、分子和發炎機制。此外,生物製劑能夠滿足現有療法無法充分解決的臨床需求,且其定價潛力更高,預計這些因素也將推動未來市場擴張。
本報告考察了全球心臟衰竭藥物市場,提供了概述、背景、市場影響因素分析、市場規模趨勢和預測、按各個細分市場和地區/主要國家進行的詳細分析、競爭格局以及主要公司的概況。
目錄
第1章 背景
第2章:調查方法
第3章 市場動態
第4章 宏觀經濟指標
第5章摘要整理
第6章:引言
- 心臟衰竭概述
- 心臟衰竭的階段
- 心臟衰竭發生和發展的相關因素
- 心臟衰竭的治療和管理
- 前景
第7章 市場狀況
- 調查方法和關鍵參數
- 心臟衰竭藥物:市場現狀
- 心臟衰竭藥物研發公司:市場概況
第8章:公司簡介
- 章節概要
- AstraZeneca
- Boehringer Ingelheim
- Bristol Myers Squibb
- Corteria Pharmaceuticals
- Cytokinetics
- Eli Lilly
- Hyloris Pharmaceuticals
- Suncadia Pharmaceuticals
- Novo Nordisk
- Sardocor
- StemCardia
- Tasly Pharmaceuticals
- Tenaya Therapeutics
第9章:臨床試驗分析
- 調查方法和關鍵參數
- 心臟衰竭藥物:臨床試驗分析
第10章:藥物研發失敗分析
- 調查方法和關鍵參數
- 心臟衰竭藥物:藥物研發失敗案例分析
第11章 市場影響分析
- 市場促進因素
- 市場限制因素
- 市場機遇
- 市場挑戰
第12章:全球心臟衰竭市場
- 關鍵假設和調查方法
- 全球心臟衰竭藥物市場:歷史趨勢與預測
- 多元情境分析
- 主要市場區隔
第13章心臟衰竭市場:依心臟衰竭類型分類
- 關鍵假設和調查方法
- 心臟衰竭治療市場:依心臟衰竭類型分類
- 慢性心臟衰竭:過去趨勢與預測
- 其他:過往趨勢和預測
- 數據三角測量與檢驗
第14章心臟衰竭市場:依治療方式分類
- 關鍵假設和調查方法
- 心臟衰竭藥物市場:依治療方法分類
- 單藥療法:過往趨勢與預測
- 聯合治療:過往趨勢與預測
- 數據三角測量與檢驗
第15章心臟衰竭市場:依分子類型分類
- 關鍵假設和調查方法
- 心臟衰竭藥物市場:依分子類型分類
- 小分子化合物:過去趨勢與預測
- 生物製藥:過去趨勢與預測
- 數據三角測量與檢驗
第16章心臟衰竭市場:依給藥途徑分類
- 關鍵假設和調查方法
- 心臟衰竭治療市場:依給藥途徑分類
- 口頭報告:過往趨勢與預測
- 心肌內膜:過去趨勢與預測
- 皮下組織:過去趨勢與預測
- 靜脈注射:過去趨勢與預測
- 冠狀動脈:既往趨勢與預測
- 數據三角測量與檢驗
第17章心臟衰竭市場:按地區分類
- 心臟衰竭藥物市場:按地區分類
- 北美:歷史趨勢與預測
- 歐洲:過往趨勢與預測
- 亞太地區:歷史趨勢與預測
- 其他地區:過往趨勢與預測
- 數據三角測量與檢驗
第18章 市場機會分析:北美
- 按類型分類的心臟衰竭
- 透過治療方法
- 依分子類型
- 透過行政途徑
第19章 市場機會分析:歐洲
- 按類型分類的心臟衰竭
- 透過治療方法
- 依分子類型
- 透過行政途徑
第20章 市場機會分析:亞太地區
- 按類型分類的心臟衰竭
- 透過治療方法
- 依分子類型
- 透過行政途徑
第21章 市場機會分析:世界其他地區
- 按類型分類的心臟衰竭
- 透過治療方法
- 依分子類型
- 透過行政途徑
第22章心臟衰竭市場:治療藥物銷售預測
- 已通過核准和 III 期臨床試驗階段的心臟衰竭治療藥物:銷售預測
- Empagliflozin / Jardiance
- Farxiga / Dapagliflozin
- Kerendia / Finerenone
- Furoscix / Furosemide
- Injectafer / Ferinject
- Verquvo / Vericiguat
- Sotagliflozin / Inpefa
- Baxdrostat
- Balcinrenone / Dapagliflozin
- Vicadrostat / BI 690517
- Ziltivekimab
- Revascor / Rexlemestrocel L
- Maridebart cafraglutid
- Omecamtiv Mecarbil
- Ferric Derisomaltose
- JRM-001
- Enavogliflozin / Envlo
第23章 結論
第24章 高階主管洞察
第25章附錄一:表格形式數據
第26章 附錄二:公司與組織列表
HEART FAILURE DRUGS MARKET: OVERVIEW
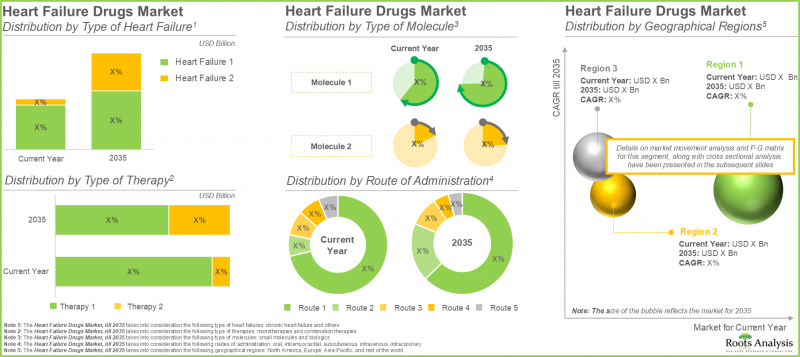
As per Roots Analysis, the global heart failure drugs market is estimated to grow from USD 9.19 billion in the current year to USD 12.31 billion by 2035, at a notable CAGR during the forecast period, till 2035 (this represents the opportunity only for those drugs that are primarily indicated for heart failure).
HEART FAILURE DRUGS MARKET: GROWTH AND TRENDS
Heart failure is a progressive cardiovascular disorder characterized by the heart's inability to pump an adequate volume of blood to meet the body's metabolic demands. The rising prevalence of this condition has prompted pharmaceutical companies to develop a broad range of therapeutic interventions aimed at managing fluid retention, enhancing cardiac function, regulating blood pressure, and addressing the underlying causes of disease progression. According to the Heart Failure Society of America, approximately 6.7 million Americans aged 20 years and older are currently living with heart failure, a figure projected to increase to 10.3 million by 2040.
Over the years, significant advancements in drug development have expanded the range of treatment options available for heart failure management. Several therapeutic classes have received approval from the U.S. Food and Drug Administration, including angiotensin-converting enzyme (ACE) inhibitors, diuretics, angiotensin receptor blockers (ARBs), aldosterone antagonists, and beta-blockers. Continued clinical research and technological innovation have further introduced next-generation therapies and congenital heart defect devices that are transforming treatment paradigms. Notably, angiotensin receptor-neprilysin inhibitors (ARNIs), sodium-glucose cotransporter-2 (SGLT2) inhibitors, and mineralocorticoid receptor antagonists provide broader therapeutic benefits by targeting multiple pathways associated with cardiac remodeling, fluid overload, and neurohormonal dysregulation.
The heart failure therapeutics market continues to demonstrate steady growth, supported by substantial investments in research and development by pharmaceutical companies. Ongoing innovation in novel drug mechanisms, combination therapies, and advanced drug-delivery technologies is expanding the treatment landscape and improving patient outcomes. As clinical evidence supporting these advanced therapies continues to strengthen, their adoption is expected to accelerate, creating significant opportunities for sustained market expansion over the forecast period.
Growth Drivers: Strategic Enablers of Market Expansion
The growth of the heart failure therapeutics market is being driven by the convergence of demographic trends and continued innovation in treatment approaches. The expanding geriatric population, coupled with the rising prevalence of age-associated risk factors such as hypertension, obesity, coronary artery disease, and diabetes, has led to a substantial increase in the incidence of heart failure worldwide.
As the prevalence of the condition rises significantly among individuals aged 70 years and above, the demand for more effective treatment options continues to grow. In response, pharmaceutical companies have introduced innovative drug classes, including sodium-glucose cotransporter-2 (SGLT2) inhibitors and angiotensin receptor-neprilysin inhibitors (ARNIs), which have demonstrated strong clinical efficacy in improving patient outcomes. These therapies are associated with reduced mortality rates and lower risks of heart failure-related hospitalizations, while the combined use of SGLT2 inhibitors and ARNIs has shown enhanced therapeutic benefits. Consequently, the increasing adoption of these advanced therapies is expected to support sustained growth of the heart failure therapeutics market over the coming years.
Market Challenges: Critical Barriers Impeding Progress
Despite the growing demand for innovative heart failure therapies, the market continues to face several challenges that may impede its growth trajectory. The development of therapies for this indication is associated with high attrition rates, primarily driven by inadequate clinical efficacy, limited target specificity, and safety concerns that frequently emerge during the clinical development process.. Additionally, the approval rate of new molecular entities (NMEs) for cardiovascular indications remains relatively low, increasing both the complexity and cost of bringing novel therapies to market. These challenges are further compounded by the substantial financial requirements associated with large-scale clinical trials, stringent regulatory pathways, and patient recruitment difficulties. At the same time, limited funding support from government agencies and private investors can restrict the progression of promising research programs, creating barriers to innovation and slowing the development of next-generation heart failure treatments. Consequently, these factors continue to pose significant challenges for stakeholders operating within the heart failure therapeutics market.
HEART FAILURE DRUGS MARKET: KEY INSIGHTS
The report delves into the current state of the heart failure drugs market and identifies potential growth opportunities within industry. Some key findings from the report include:
1. Owing to the rising disease prevalence and lack of selective treatment approaches, several researchers and industry stakeholders are prioritizing the development of heart failure drugs.
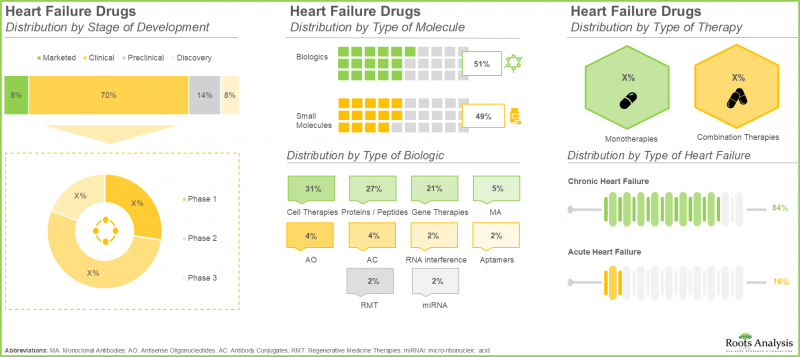
2. More than 120 drugs are currently approved / being investigated across various stages of development for the treatment and management of heart failure; of these, over 90% are under clinical development.
3. Majority (51%) of the heart failure drugs are biologics; of these, 75% of the drugs are being investigated for chronic heart failure under different stages of clinical development.
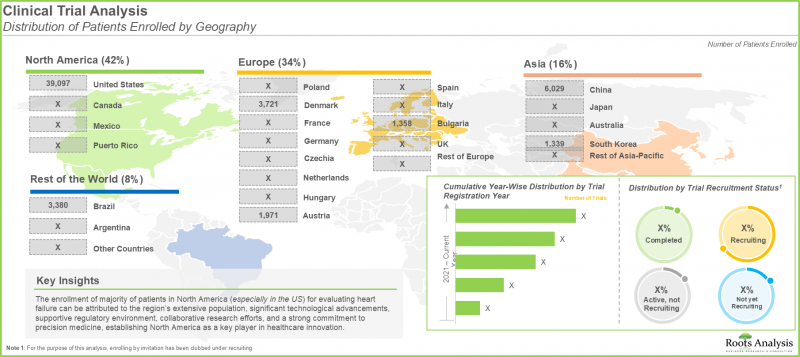
4. Clinical trials investigating drugs targeting heart failure are distributed across different geographical regions; maximum patient enrollment was observed in North America (42%), followed by Europe (34%).
5. Around 45% of the discontinued therapies were industry sponsored; of these, more than 35% of the trials were for heart failure with preserved ejection fraction.
6. The heart failure drugs market is anticipated to grow at a notable CAGR owing to the ability to improve patient outcomes through novel therapeutic mechanisms (such as SGLT2 inhibitors and other emerging classes).
7. The heart failure drugs market in North America is expected to capture maximum share by 2035, driven by a robust pharmaceutical ecosystem, high R&D investments, and accelerated regulatory approvals.
8. Driven by the growing adoption of heart failure drugs in the US, the market is poised to grow at a relatively higher CAGR over the forecast period.
Heart Failure Drugs Market Segments
The market sizing and opportunity analysis has been segmented across the following parameters:
By Type of Heart Failure
- Chronic Heart Failure
- Others
By Type of Therapy
- Monotherapies
- Combination Therapies
By Type of Molecule
- Small Molecules
- Biologics
Route of Administration
- Oral
- Intramyocardial
- Subcutaneous
- Intravenous
- Intracoronary
By Geographical Regions
- North America
- US
- Canada
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of the World
HEART FAILURE DRUGS MARKET: KEY SEGMENT INSIGHTS
Which Type of Heart Failure Represents the Largest Share of the Heart Failure Drugs Market?
Currently, the chronic heart failure segment is expected to account for the overwhelming majority of the heart failure drugs market, capturing more than 95% of total revenue. This dominance is primarily attributed to the high prevalence of chronic heart failure, its lifelong disease management requirements, and the continuous need for pharmacological intervention to control symptoms and prevent disease progression. The segment is also expected to witness steady growth throughout the forecast period. Notably, Empagliflozin (Jardiance), a monotherapy approved for heart failure treatment in 2021, generated approximately USD 4.4 billion in sales in 2025, underscoring the strong commercial potential of chronic heart failure therapeutics.
Regional Analysis: Which Regions are Expected to Exhibit the Strongest Growth?
North America: Maintaining Market Leadership
According to market projections, North America is expected to retain its position as the largest regional market, accounting for over 40% of the global heart failure drugs market in the current year. The region benefits from a well-established healthcare infrastructure, high disease awareness, favorable reimbursement frameworks, and significant investment in cardiovascular research. In particular, the United States has emerged as a leading hub for heart failure drug development, supported by innovation-driven regulatory policies, a robust biopharmaceutical ecosystem, and access to a highly skilled workforce. These advantages facilitate the efficient progression of therapies from early-stage development through commercialization.
Asia-Pacific: Fastest-Growing Regional Market
While North America is expected to dominate in terms of market share, Asia-Pacific is projected to register the highest growth rate through 2035. Growth in the region is anticipated to be driven by a rapidly aging population, increasing prevalence of cardiovascular disorders, expanding healthcare access, and rising investments in pharmaceutical innovation.
UAE Market Outlook
In the United Arab Emirates, market accessibility is expected to improve following recent initiatives by the Emirates Drug Establishment to reduce the retail prices of 168 pharmaceutical products. The price revisions include advanced therapies used in the treatment of chronic heart muscle failure, thereby supporting broader patient access to innovative heart failure medications.
Which Molecule Type is Expected to Dominate the Heart Failure Drugs Market?
Small molecules are projected to remain the dominant molecule category, accounting for more than 95% of the market in the current year. Their leadership position is supported by their established efficacy, advantages associated with oral drug administration, and widespread use as the standard of care in heart failure management. Key therapeutic classes, including beta-blockers, ACE inhibitors, ARBs, and SGLT2 inhibitors, have demonstrated significant clinical benefits in reducing mortality and improving patient outcomes across both heart failure with reduced ejection fraction (HFrEF) and preserved ejection fraction (HFpEF) populations.
Conversely, the biologics segment is anticipated to expand at a substantially higher CAGR of 52.0% during the forecast period. This growth is expected to be driven by increasing interest in precision medicine approaches, with biologics offering the potential to target genetic, molecular, and inflammatory mechanisms underlying heart failure progression. Their ability to address unmet clinical needs and command premium pricing is likely to support future market expansion.
Which Route of Administration Accounts for the Largest Market Share?
Based on market forecasts, oral therapies currently contribute more than 95% of total market revenue. The widespread adoption of oral formulations can be attributed to their convenience, strong patient adherence, suitability for long-term disease management, and ease of self-administration in outpatient settings.
Meanwhile, therapies administered through the intramyocardial route are expected to experience the fastest growth, registering a CAGR of 34.9% through 2035. This growth is driven by the route's ability to deliver therapeutic agents directly to cardiac tissue, potentially enhancing treatment efficacy and improving cardiac function in patients with advanced heart failure.
Among Monotherapies and Combination Therapies, Which Segment Holds the Largest Share?
Monotherapies currently account for the majority of market revenue, reflecting their long-standing role as first-line treatment options within established clinical guidelines. Their broad adoption is supported by favorable cost-effectiveness profiles, well-documented clinical outcomes, and higher patient adherence compared to more complex treatment regimens.
However, the combination therapy segment is expected to witness stronger growth, with a projected CAGR of 34.4% over the forecast period. Increasing adoption of multidrug treatment strategies, including quadruple therapy regimens comprising ARNIs, beta-blockers, mineralocorticoid receptor antagonists (MRAs), and SGLT2 inhibitors, is expected to drive this expansion. These combination approaches offer synergistic therapeutic effects, leading to improved clinical outcomes, reduced mortality and hospitalization rates, and enhanced disease management compared to standalone therapies.
Example Players in Heart Failure Drugs Market
- AstraZeneca
- Boehringer Ingelheim
- Bristol Myers Squibb
- Corteria Pharmaceuticals
- Cytokinetics
- Eli Lilly
- Hyloris Pharmaceuticals
- Jiangsu Hengrui Pharmaceuticals
- Novo Nordisk
- Sardocor
- StemCardia
- Tasly Pharmaceuticals
- Tenaya Therapeutics
Primary Research Overview
The opinions and insights presented in this study were influenced by discussions conducted with multiple stakeholders. The research report features detailed transcripts of the following third-party discussions:
- Professor of Medical Cardiology, Very Large Organization, United Kingdom, Europe
- Professor and Head of Advanced Heart Failure Wing, Very Large Organization, United States, North America
- Clinical Associate Professor and Director of Clinical Research, Large Organization, United States, North America
- Doctor of Medicine, Very Large Organization, United States, North America
- Professor, Very Large Organization, United States, North America
- Professor of Medicine and Heart Failure Specialist (Former Chair of Division for Circulatory Failure), Very Large Organization, United States, North America
- Senior Consultant Cardiologist, Large Organization, India, Asia
- Chair of DIGIT-HF trial, Very Large Organization, Germany, Europe
- Cardiologist and Clinical Researcher, Very Large Organization, United States, North America
HEART FAILURE DRUGS MARKET: RESEARCH COVERAGE
- Market Sizing and Opportunity Analysis: The report features an in-depth analysis of the heart failure drugs market, focusing on key market segments, including [A] type of heart failure, [B] type of therapy, [C] type of molecule, [D] route of administration, [E] geographical regions, and [F] sales forecast.
- Market Landscape: A detailed assessment of the overall heart failure drugs market landscape, featuring information on several relevant parameters, such as [A] stage of development, [B] type of molecule, [C] type of biologic, [D] type of therapy, [E] mechanism of action, [F] route of administration, [G] target patient population, [H] type of heart failure, [I] year of establishment, [J] company size, [K] location of headquarters and [L] most active players.
- Company Profiles: In-depth profiles of key drug developers in the heart failure drugs market, focusing on [A] company overview, [B] financial information, [C] drug portfolio, [D] recent developments and [E] an informed future outlook.
- Clinical Trial Analysis: An analysis of completed and ongoing clinical trials related to heart failure drugs, based on several relevant parameters, such as [A] trial registration year, [B] enrolled patient population, [C] trial phase, [D] trial status, [E] type of sponsor / collaborator, [F] patient gender, [G] study design (type of trial masking, type of intervention model, trial purpose and design allocation), [H] leading industry and non-industry players (based on number of clinical trials) and [I] geography.
- Drug Failure Analysis: An insightful drug failure analysis, based on several parameters, such as [A] trial phase, [B] trial status, [C] reason of drug discontinuation, [D] study start year, [E] year of discontinuation, [F] type of molecule, and [G] route of administration.
- Market Impact Analysis: The report analyzes various factors such as drivers, restraints, opportunities, and challenges affecting market growth.
KEY QUESTIONS ANSWERED IN THIS REPORT
- Which are the leading companies in the heart failure drugs market?
- Which region dominates the heart failure drugs market?
- What are the key trends observed in the heart failure drugs market?
- What factors are likely to influence the evolution of this market?
- What are the primary challenges faced by heart failure drug developers?
- What is the current and future market size?
- What is the CAGR of this market?
- How is the current and future market opportunity likely to be distributed across key market segments?
REASONS TO BUY THIS REPORT
- The report provides a comprehensive market analysis, offering detailed revenue projections of the overall market and its specific sub-segments. This information is valuable to both established market leaders and emerging entrants.
- The report offers stakeholders a comprehensive overview of the market, including key drivers, barriers, opportunities, and challenges. This information empowers stakeholders to stay abreast of market trends and make data-driven decisions to capitalize on growth prospects.
- The report can aid businesses in identifying future opportunities in any sector. It also helps in understanding if those opportunities are worth pursuing.
- The report helps in identifying customer demand by understanding the needs, preferences, and behavior of the target audience in order to tailor products or services effectively.
- The report equips new entrants with requisite information regarding a particular market to help them build successful business strategies.
- The report allows for more effective communication with the audience and in building strong business relations.
ADDITIONAL BENEFITS
- Complementary Excel Data Packs for all Analytical Modules in the Report
- 15% Free Content Customization
- Detailed Report Walkthrough Session with Research Team
- Free Updated report if the report is 6-12 months old or older
TABLE OF CONTENTS
1. BACKGROUND
- 1.1. Context
- 1.2. Project Objectives
2. RESEARCH METHODOLOGY
- 2.1. Chapter Overview
- 2.2. Research Assumptions
- 2.2.1. Market Landscape and Market Trends
- 2.2.2. Market Forecast and Opportunity Analysis
- 2.2.3. Comparative Analysis
- 2.3. Database Building
- 2.3.1. Data Collection
- 2.3.2. Data Validation
- 2.3.3. Data Analysis
- 2.4. Project Methodology
- 2.4.1. Secondary Research
- 2.4.1.1. Annual Reports
- 2.4.1.2. Academic Research Papers
- 2.4.1.3. Company Websites
- 2.4.1.4. Investor Presentations
- 2.4.1.5. Regulatory Filings
- 2.4.1.6. White Papers
- 2.4.1.7. Industry Publications
- 2.4.1.8. Conferences and Seminars
- 2.4.1.9. Government Portals
- 2.4.1.10. Media and Press Releases
- 2.4.1.11. Newsletters
- 2.4.1.12. Industry Databases
- 2.4.1.13. Roots Proprietary Databases
- 2.4.1.14. Paid Databases and Sources
- 2.4.1.15. Social Media Portals
- 2.4.1.16. Other Secondary Sources
- 2.4.2. Primary Research
- 2.4.2.1. Types of Primary Research
- 2.4.2.1.1. Qualitative Research
- 2.4.2.1.2. Quantitative Research
- 2.4.2.1.3. Hybrid Approach
- 2.4.2.2. Advantages of Primary Research
- 2.4.2.3. Techniques for Primary Research
- 2.4.2.3.1. Interviews
- 2.4.2.3.2. Surveys
- 2.4.2.3.3. Focus Groups
- 2.4.2.3.4. Observational Research
- 2.4.2.3.5. Social Media Interactions
- 2.4.2.4. Key Opinion Leaders Considered in Primary Research
- 2.4.2.4.1. Company Executives (CXOs)
- 2.4.2.4.2. Board of Directors
- 2.4.2.4.3. Company Presidents and Vice Presidents
- 2.4.2.4.4. Research and Development Heads
- 2.4.2.4.5. Technical Experts
- 2.4.2.4.6. Subject Matter Experts
- 2.4.2.4.7. Scientists
- 2.4.2.4.8. Doctors and Other Healthcare Providers
- 2.4.2.5. Ethics and Integrity
- 2.4.2.5.1. Research Ethics
- 2.4.2.5.2. Data Integrity
- 2.4.2.1. Types of Primary Research
- 2.4.3. Analytical Tools and Databases
- 2.4.1. Secondary Research
- 2.5. Robust Quality Control
3. MARKET DYNAMICS
- 3.1. Chapter Overview
- 3.2. Forecast Methodology
- 3.2.1. Top-down Approach
- 3.2.2. Bottom-up Approach
- 3.2.3. Hybrid Approach
- 3.3. Market Assessment Framework
- 3.3.1. Total Addressable Market (TAM)
- 3.3.2. Serviceable Addressable Market (SAM)
- 3.3.3. Serviceable Obtainable Market (SOM)
- 3.3.4. Currently Acquired Market (CAM)
- 3.4. Forecasting Tools and Techniques
- 3.4.1. Qualitative Forecasting
- 3.4.2. Correlation
- 3.4.3. Regression
- 3.4.4. Extrapolation
- 3.4.5. Convergence
- 3.4.6. Sensitivity Analysis
- 3.4.7. Scenario Planning
- 3.4.8. Data Visualization
- 3.4.9. Time Series Analysis
- 3.4.10. Forecast Error Analysis
- 3.5. Key Considerations
- 3.5.1. Demographics
- 3.5.2. Government Regulations
- 3.5.3. Reimbursement Scenarios
- 3.5.4. Market Access
- 3.5.5. Supply Chain
- 3.5.6. Industry Consolidation
- 3.5.7. Pandemic / Unforeseen Disruptions Impact
- 3.6. Limitations
4. MACRO-ECONOMIC INDICATORS
- 4.1. Chapter Overview
- 4.2. Market Dynamics
- 4.2.1. Time Period
- 4.2.1.1. Historical Trends
- 4.2.1.2. Current and Forecasted Estimates
- 4.2.2. Currency Coverage
- 4.2.2.1. Major Currencies Affecting the Market
- 4.2.2.2. Factors Affecting Currency Fluctuations on the Industry
- 4.2.2.3. Impact of Currency Fluctuations on the Industry
- 4.2.3. Foreign Currency Exchange Rate
- 4.2.3.1. Impact of Foreign Exchange Rate Volatility on the Market
- 4.2.3.2. Strategies for Mitigating Foreign Exchange Risk
- 4.2.4. Recession
- 4.2.4.1. Assessment of Current Economic Conditions and Potential Impact on the Market
- 4.2.4.2. Historical Analysis of Past Recessions and Lessons Learnt
- 4.2.5. Inflation
- 4.2.5.1. Measurement and Analysis of Inflationary Pressures in the Economy
- 4.2.5.2. Potential Impact of Inflation on the Market Evolution
- 4.2.6. Interest Rates
- 4.2.6.1. Interest Rates and Their Impact on the Market
- 4.2.6.2. Strategies for Managing Interest Rate Risk
- 4.2.7. Commodity Flow Analysis
- 4.2.7.1. Type of Commodity
- 4.2.7.2. Origins and Destinations
- 4.2.7.3. Values and Weights
- 4.2.7.4. Modes of Transportation
- 4.2.8. Global Trade Dynamics
- 4.2.8.1. Import Scenario
- 4.2.8.2. Export Scenario
- 4.2.8.3. Trade Policies
- 4.2.8.4. Strategies for Mitigating the Risks Associated with Trade Barriers
- 4.2.8.5. Impact of Trade Barriers on the Market
- 4.2.9. War Impact Analysis
- 4.2.9.1. Russian-Ukraine War
- 4.2.9.2. Israel-Hamas War
- 4.2.10. COVID Impact / Related Factors
- 4.2.10.1. Global Economic Impact
- 4.2.10.2. Industry-specific Impact
- 4.2.10.3. Government Response and Stimulus Measures
- 4.2.10.4. Future Outlook and Adaptation Strategies
- 4.2.11. Other Indicators
- 4.2.11.1. Fiscal Policy
- 4.2.11.2. Consumer Spending
- 4.2.11.3. Gross Domestic Product
- 4.2.11.4. Employment
- 4.2.11.5. Taxes
- 4.2.11.6. Stock Market Performance
- 4.2.11.7. Cross Border Dynamics
- 4.2.1. Time Period
- 4.3. Conclusion
5. EXECUTIVE SUMMARY
- 5.1. Executive Summary: Market Landscape
- 5.2. Executive Summary: Market Trends
- 5.3. Executive Summary: Market Forecast and Opportunity Analysis
6. INTRODUCTION
- 6.1. Overview of Heart Failure
- 6.2. Stages of Heart Failure
- 6.3. Factors Contributing to Heart Failure
- 6.4. Heart Failure Treatment and Management
- 6.5. Future Perspectives
7. MARKET LANDSCAPE
- 7.1. Methodology and Key Parameters
- 7.2. Heart Failure Drugs: Overall Market Landscape
- 7.2.1. Analysis by Stage of Development
- 7.2.2. Analysis by Type of Molecule
- 7.2.3. Analysis by Type of Biologic
- 7.2.4. Analysis by Type of Therapy
- 7.2.5. Analysis by Mechanism of Action
- 7.2.6. Analysis by Route of Administration
- 7.2.7. Analysis by Target Patient Population
- 7.2.8. Analysis by Type of Heart Failure
- 7.3. Heart Failure Drug Developers: Market Landscape
- 7.3.1. Analysis by Year of Establishment
- 7.3.2. Analysis by Company Size
- 7.3.3. Analysis by Location of Headquarters
- 7.3.4. Most Active Players: Analysis by Number of Drugs Developed
8. COMPANY PROFILES
- 8.1. Chapter Overview
- 8.2. AstraZeneca
- 8.2.1. Company Overview
- 8.2.2. Heart Failure Drugs Portfolio
- 8.2.3. Key Initiatives
- 8.3. Boehringer Ingelheim
- 8.4. Bristol Myers Squibb
- 8.5. Corteria Pharmaceuticals
- 8.6. Cytokinetics
- 8.7. Eli Lilly
- 8.8. Hyloris Pharmaceuticals
- 8.9. Suncadia Pharmaceuticals
- 8.10. Novo Nordisk
- 8.11. Sardocor
- 8.12. StemCardia
- 8.13. Tasly Pharmaceuticals
- 8.14. Tenaya Therapeutics
9. CLINICAL TRIAL ANALYSIS
- 9.1. Methodology and Key Parameters
- 9.2. Heart Failure Drugs: Clinical Trial Analysis
- 9.2.1. Analysis by Trial Registration Year
- 9.2.2. Analysis by Trial Status
- 9.2.3. Analysis by Trial Registration Year and Trial Status
- 9.2.4. Analysis by Patients Enrolled by Trial Phase
- 9.2.5. Analysis by Patients Enrolled by Trial Registration Year
- 9.2.6. Analysis by Trial Phase
- 9.2.7. Analysis by Type of Sponsor / Collaborator
- 9.2.8. Analysis by Patient Gender
- 9.2.9. Analysis by Study Design
- 9.2.10. Analysis by Target Patient Population
- 9.2.11. Most Active Industry Players: Analysis by Number of Clinical Trials
- 9.2.12. Most Active Non-Industry Players: Analysis by Number of Clinical Trials
- 9.2.13. Geographical Distribution of Trials and Number of Patients Enrolled
- 9.2.14. Analysis of Clinical Trials by Trial Status and Geography
- 9.2.15. Analysis of Patients Enrolled by Trial Status and Geography
10. DRUG FAILURE ANALYSIS
- 10.1. Methodology and Key Parameters
- 10.2. Heart Failure Drugs: Drug Failure Analysis
- 10.2.1. Analysis by Trial Phase
- 10.2.2. Analysis by Trial Status
- 10.2.3. Analysis by Reason of Drug Discontinuation
- 10.2.4. Analysis by Study Start Year and Year of Discontinuation
- 10.2.5. Analysis by Type of Heart Failure
- 10.2.6. Analysis by Type of Sponsor
- 10.2.7. Analysis by Geographical Region
11. MARKET IMPACT ANALYSIS
- 11.1. Market Drivers
- 11.2. Market Restraints
- 11.3. Market Opportunities
- 11.4. Market Challenges
12. GLOBAL HEART FAILURE MARKET
- 12.1. Key Assumptions and Methodology
- 12.2. Global Heart Failure Drugs Market, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 12.3. Multivariate Scenario Analysis
- 12.3.1. Global Heart Failure Drugs Market, Forecasted Estimates (Till 2035), Conservative Scenario
- 12.3.2. Global Heart Failure Drugs Market, Forecasted Estimates (Till 2035), Optimistic Scenario
- 12.4. Key Market Segments
13. HEART FAILURE MARKET, BY TYPE OF HEART FAILURE
- 13.1. Key Assumptions and Methodology
- 13.2. Heart Failure Drugs Market: Distribution by Type of Heart Failure
- 13.2.1. Heart Failure Drugs Market for Chronic Heart Failure: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 13.2.2. Heart Failure Drugs Market for Others: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 13.3. Data Triangulation and Validation
14. HEART FAILURE MARKET, BY TYPE OF THERAPY
- 14.1. Key Assumptions and Methodology
- 14.2. Heart Failure Drugs Market: Distribution by Type of Therapy
- 14.2.1. Heart Failure Drugs Market for Monotherapies: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 14.2.2. Heart Failure Drugs Market for Combination Therapies: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 14.3. Data Triangulation and Validation
15. HEART FAILURE MARKET, BY TYPE OF MOLECULE
- 15.1. Key Assumptions and Methodology
- 15.2. Heart Failure Drugs Market: Distribution by Type of Molecule
- 15.2.1. Heart Failure Drugs Market for Small Molecules: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 15.2.2. Heart Failure Drugs Market for Biologics: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 15.3. Data Triangulation and Validation
16. HEART FAILURE MARKET, BY ROUTE OF ADMINISTRATION
- 16.1. Key Assumptions and Methodology
- 16.2. Heart Failure Drugs Market: Distribution by Route of Administration
- 16.2.1. Heart Failure Drugs Market for Oral Route: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 16.2.2. Heart Failure Drugs Market for Subcutaneous Route: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 16.2.3. Heart Failure Drugs Market for Intramyocardial Route: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 16.2.4. Heart Failure Drugs Market for Intravenous Route: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 16.2.5. Heart Failure Drugs Market for Intracoronary Route: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 16.3. Data Triangulation and Validation
17. HEART FAILURE MARKET, BY GEOGRAPHICAL REGIONS
- 17.1. Heart Failure Drugs Market: Distribution by Geographical Regions
- 17.1.1. Heart Failure Drugs Market in North America: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 17.1.1.1. Heart Failure Drugs Market in the US: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 17.1.1.2. Heart Failure Drugs Market in Canada: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 17.1.2. Heart Failure Drugs Market in Europe: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 17.1.2.1. Heart Failure Drugs Market in Germany: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 17.1.2.2. Heart Failure Drugs Market in France: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 17.1.2.3. Heart Failure Drugs Market in UK: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 17.1.2.4. Heart Failure Drugs Market in Italy: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 17.1.2.5. Heart Failure Drugs Market in Spain: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 17.1.2.6. Heart Failure Drugs Market in Rest of Europe: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 17.1.3. Heart Failure Drugs Market in Asia-Pacific: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 17.1.3.1. Heart Failure Drugs Market in China: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 17.1.3.2. Heart Failure Drugs Market in Japan: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 17.1.3.3. Heart Failure Drugs Market in India: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 17.1.3.4. Heart Failure Drugs Market in South Korea: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 17.1.3.5. Heart Failure Drugs Market in Rest of Asia-Pacific: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 17.1.4. Heart Failure Drugs Market in Rest of the World: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 17.1.1. Heart Failure Drugs Market in North America: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 17.2. Data Triangulation and Validation
18. MARKET OPPORTUNITY ANALYSIS: NORTH AMERICA
- 18.1. Heart Failure Drugs Market in North America: Distribution by Type of Heart Failure
- 18.1.1. Heart Failure Drugs Market in North America for Chronic Heart Failure, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 18.1.2. Heart Failure Drugs Market in North America for Others, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 18.2. Heart Failure Drugs Market in North America: Distribution by Type of Therapy
- 18.2.1. Heart Failure Drugs Market in North America for Monotherapies, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 18.2.2. Heart Failure Drugs Market in North America for Combination Therapies, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 18.3. Heart Failure Drugs Market in North America: Distribution by Type of Molecule
- 18.3.1. Heart Failure Drugs Market in North America for Small Molecules, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 18.3.2. Heart Failure Drugs Market in North America for Biologics, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 18.4. Heart Failure Drugs Market in North America: Distribution by Route of Administration
- 18.4.1. Heart Failure Drugs Market in North America for Oral Route, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 18.4.2. Heart Failure Drugs Market in North America for Subcutaneous Route, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 18.4.3. Heart Failure Drugs Market in North America for Intramyocardial Route, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 18.4.4. Heart Failure Drugs Market in North America for Intravenous Route, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 18.4.5. Heart Failure Drugs Market in North America for Intracoronary Route, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
19. MARKET OPPORTUNITY ANALYSIS: EUROPE
- 19.1. Heart Failure Drugs Market in Europe: Distribution by Type of Heart Failure
- 19.1.1. Heart Failure Drugs Market in Europe for Chronic Heart Failure, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 19.1.2. Heart Failure Drugs Market in Europe for Others, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 19.2. Heart Failure Drugs Market in Europe: Distribution by Type of Therapy
- 19.2.1. Heart Failure Drugs Market in Europe for Monotherapies, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 19.2.2. Heart Failure Drugs Market in Europe for Combination Therapies, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 19.3. Heart Failure Drugs Market in Europe: Distribution by Type of Molecule
- 19.3.1. Heart Failure Drugs Market in Europe for Small Molecules, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 19.3.2. Heart Failure Drugs Market in Europe for Biologics, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 19.4. Heart Failure Drugs Market in Europe: Distribution by Route of Administration
- 19.4.1. Heart Failure Drugs Market in Europe for Oral Route, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 19.4.2. Heart Failure Drugs Market in Europe for Subcutaneous Route, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 19.4.3. Heart Failure Drugs Market in Europe for Intramyocardial Route, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 19.4.4. Heart Failure Drugs Market in Europe for Intravenous Route, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 19.4.5. Heart Failure Drugs Market in Europe for Intracoronary Route, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
20. MARKET OPPORTUNITY ANALYSIS: ASIA-PACIFIC
- 20.1. Heart Failure Drugs Market in Asia-Pacific: Distribution by Type of Heart Failure
- 20.1.1. Heart Failure Drugs Market in Asia-Pacific for Chronic Heart Failure, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 20.1.2. Heart Failure Drugs Market in Asia-Pacific for Others, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 20.2. Heart Failure Drugs Market in Asia-Pacific: Distribution by Type of Therapy
- 20.2.1. Heart Failure Drugs Market in Asia-Pacific for Monotherapies, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 20.2.2. Heart Failure Drugs Market in Asia-Pacific for Combination Therapies, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 20.3. Heart Failure Drugs Market in Asia-Pacific: Distribution by Type of Molecule
- 20.3.1. Heart Failure Drugs Market in Asia-Pacific for Small Molecules, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 20.3.2. Heart Failure Drugs Market in Asia-Pacific for Biologics, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 20.4. Heart Failure Drugs Market in Asia-Pacific: Distribution by Route of Administration
- 20.4.1. Heart Failure Drugs Market in Asia-Pacific for Oral Route, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 20.4.2. Heart Failure Drugs Market in Asia-Pacific for Subcutaneous Route, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 20.4.3. Heart Failure Drugs Market in Asia-Pacific for Intramyocardial Route, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 20.4.4. Heart Failure Drugs Market in Asia-Pacific for Intravenous Route, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 20.4.5. Heart Failure Drugs Market in Asia-Pacific for Intracoronary Route, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
21. MARKET OPPORTUNITY ANALYSIS: REST OF THE WORLD
- 21.1. Heart Failure Drugs Market in Rest of the World: Distribution by Type of Heart Failure
- 21.1.1. Heart Failure Drugs Market in Rest of the World for Chronic Heart Failure, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 21.1.2. Heart Failure Drugs Market in Rest of the World for Others, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 21.2. Heart Failure Drugs Market in Rest of the World: Distribution by Type of Therapy
- 21.2.1. Heart Failure Drugs Market in Rest of the World for Monotherapies, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 21.2.2. Heart Failure Drugs Market in Rest of the World for Combination Therapies, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 21.3. Heart Failure Drugs Market in Rest of the World: Distribution by Type of Molecule
- 21.3.1. Heart Failure Drugs Market in Rest of the World for Small Molecules, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 21.3.2. Heart Failure Drugs Market in Rest of the World for Biologics, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 21.4. Heart Failure Drugs Market in Rest of the World: Distribution by Route of Administration
- 21.4.1. Heart Failure Drugs Market in Rest of the World for Oral Route, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 21.4.2. Heart Failure Drugs Market in Rest of the World for Subcutaneous Route, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 21.4.3. Heart Failure Drugs Market in Rest of the World for Intramyocardial Route, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 21.4.4. Heart Failure Drugs Market in Rest of the World for Intravenous Route, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- 21.4.5. Heart Failure Drugs Market in Rest of the World for Intracoronary Route, Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
22. HEART FAILURE MARKET, SALES FORECAST OF DRUGS
- 22.1. Approved and Phase III Heart Failure Drugs: Sales Forecast
- 22.1.1. Empagliflozin / Jardiance: Sales Forecast
- 22.1.2. Farxiga / Dapagliflozin: Sales Forecast
- 22.1.3. Kerendia / Finerenone: Sales Forecast
- 22.1.4. Furoscix / Furosemide: Sales Forecast
- 22.1.5. Injectafer / Ferinject: Sales Forecast
- 22.1.6. Verquvo / Vericiguat: Sales Forecast
- 22.1.7. Sotagliflozin / Inpefa: Sales Forecast
- 22.1.8. Baxdrostat: Sales Forecast
- 22.1.9. Balcinrenone / Dapagliflozin: Sales Forecast
- 22.1.10. Vicadrostat / BI 690517: Sales Forecast
- 22.1.11. Ziltivekimab: Sales Forecast
- 22.1.12. Revascor / Rexlemestrocel L: Sales Forecast
- 22.1.13. Maridebart cafraglutid: Sales Forecast
- 22.1.14. Omecamtiv Mecarbil: Sales Forecast
- 22.1.15. Ferric Derisomaltose: Sales Forecast
- 22.1.16. JRM-001: Sales Forecast
- 22.1.17. Enavogliflozin / Envlo: Sales Forecast
23. CONCLUDING REMARKS
24. EXECUTIVE INSIGHTS
- 24.1. Chapter Overview
- 24.2. Company A
- 24.2.1. Company Snapshot
- 24.2.2. Interview Transcript: Professor of Medical Cardiology
- 24.3. Company B
- 24.3.1. Company Snapshot
- 24.3.2. Interview Transcript: Professor and Head of Advanced Heart Failure Wing
- 24.4. Company C
- 24.4.1. Company Snapshot
- 24.4.2. Interview Transcript: Clinical Associate Professor & Director of Clinical Research
- 24.5. Company D
- 24.5.1. Company Snapshot
- 24.5.2. Interview Transcript: Doctor of Medicine
- 24.6. Company E
- 24.6.1. Company Snapshot
- 24.6.2. Interview Transcript: Professor
- 24.7. Company F
- 24.7.1. Company Snapshot
- 24.7.2. Interview Transcript: Professor of Medicine and Heart Failure Specialist (Former Chair of Division for Circulatory Failure)
- 24.8. Company G
- 24.8.1. Company Snapshot
- 24.8.2. Interview Transcript: Senior Consultant Cardiologist
- 24.9. Company H
- 24.9.1. Company Snapshot
- 24.9.2. Interview Transcript: Professor and Chair of DIGIT-HF trial
- 24.10. Company I
- 24.10.1. Company Snapshot
- 24.10.2. Interview Transcript: Cardiologist
25. APPENDIX I: TABULATED DATA
26. APPENDIX II: LIST OF COMPANIES AND ORGANIZATIONS
List of Tables
- Table 7.1 Back of the Eye Disorders Market: List of Drugs
- Table 7.2 Back of the Eye Disorders Market: List of Drug Developers
- Table 11.1 Back of the Eye Disorders Market: List of Forecasted Drugs
- Table 25.1 Back of the Eye Disorders Market: Drugs Landscape: Distribution by Stage of Development
- Table 25.2 Back of the Eye Disorders Market: Drugs Landscape: Distribution by Type of Molecule
- Table 25.3 Back of the Eye Disorders Market: Drugs Landscape: Distribution by Mechanism of Action
- Table 25.4 Back of the Eye Disorders Market: Drugs Landscape: Distribution by Dosing Frequency
- Table 25.5 Back of the Eye Disorders Market: Drugs Landscape: Distribution by Route of Administration
- Table 25.6 Back of the Eye Disorders Market: Drugs Landscape: Distribution by Target Indication
- Table 25.7 Back of the Eye Disorders Market: Drugs Landscape: Distribution by Type of Therapy
- Table 25.8 Back of the Eye Disorders Market: Drugs Landscape: Distribution by Drug Designation
- Table 25.9 Gene and Cell Therapy-based Back of the Eye Disorders Related Drugs Landscape: Distribution by Stage of Development
- Table 25.10 Gene and Cell Therapy-based Back of the Eye Disorders Related Drugs Landscape: Distribution by Dosing Frequency
- Table 25.11 Gene and Cell Therapy-based Back of the Eye Disorders Related Drugs Landscape: Distribution by Target Indication
- Table 25.12 Gene and Cell Therapy-based Back of the Eye Disorders Related Drugs Landscape: Distribution by Route of Administration
- Table 25.13 Gene and Cell Therapy-based Back of the Eye Disorders Related Drugs Landscape: Distribution by Type of Therapy
- Table 25.14 Small Molecule-based Back of the Eye Disorders Related Drugs Landscape: Distribution by Stage of Development
- Table 25.15 Small Molecule-based Back of the Eye Disorders Related Drugs Landscape: Distribution by Dosing Frequency
- Table 25.16 Small Molecule-based Back of the Eye Disorders Related Drugs Landscape: Distribution by Target Indication
- Table 25.17 Small Molecule-based Back of the Eye Disorders Related Drugs Landscape: Distribution by Route of Administration
- Table 25.18 Small Molecule-based Back of the Eye Disorders Related Drugs Landscape: Distribution by Type of Therapy
- Table 25.19 Antibody-based Back of the Eye Disorders Related Drugs Landscape: Distribution by Stage of Development
- Table 25.20 Antibody-based Back of the Eye Disorders Related Drugs Landscape: Distribution by Dosing Frequency
- Table 25.21 Antibody-based Back of the Eye Disorders Related Drugs Landscape: Distribution by Target Indication
- Table 25.22 Antibody-based Back of the Eye Disorders Related Drugs Landscape: Distribution by Route of Administration
- Table 25.23 Antibody-based Back of the Eye Disorders Related Drugs Landscape: Distribution by Type of Therapy
- Table 25.24 Protein-based Back of the Eye Disorders Related Drugs Landscape: Distribution by Stage of Development
- Table 25.25 Protein-based Back of the Eye Disorders Related Drugs Landscape: Distribution by Dosing Frequency
- Table 25.26 Protein-based Back of the Eye Disorders Related Drugs Landscape: Distribution by Target Indication
- Table 25.27 Protein-based Back of the Eye Disorders Related Drugs Landscape: Distribution by Route of Administration
- Table 25.28 Protein-based Back of the Eye Disorders Related Drugs Landscape: Distribution by Type of Therapy
- Table 25.29 Peptide-based Back of the Eye Disorders Related Drugs Landscape: Distribution by Stage of Development
- Table 25.30 Peptide-based Back of the Eye Disorders Related Drugs Landscape: Distribution by Dosing Frequency
- Table 25.31 Peptide-based Back of the Eye Disorders Related Drugs Landscape: Distribution by Target Indication
- Table 25.32 Peptide-based Back of the Eye Disorders Related Drugs Landscape: Distribution by Route of Administration
- Table 25.33 Peptide-based Back of the Eye Disorders Related Drugs Landscape: Distribution by Type of Therapy
- Table 25.34 Back of the Eye Disorders (Developers Landscape): Distribution by Year of Establishment
- Table 25.35 Back of the Eye Disorders (Developers Landscape): Distribution by Company Size
- Table 25.36 Back of the Eye Disorders (Developers Landscape): Distribution by Location of Headquarters
- Table 25.37 Back of the Eye Disorders (Developers Landscape): Distribution by Company Size and Location of Headquarters
- Table 25.38 Most Active Players: Distribution by Number of Drugs
- Table 25.39 Back of the Eye Disorders Market, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (USD Billion)
- Table 25.40 Back of the Eye Disorders Market, Forecasted Estimates (Till 2035): Conservative Scenario (USD Billion)
- Table 25.41 Back of the Eye Disorders Market, Forecasted Estimates (Till 2035): Optimistic Scenario (USD Billion)
- Table 25.42 Back of The Eye Disorders Market: Distribution by Scale of Operation
- Table 25.43 Back of The Eye Disorders Market at Clinical Scale, Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.44 Back of The Eye Disorders Market at Commercial Scale, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.45 Back of The Eye Disorders Market: Distribution by Type of Molecule
- Table 25.46 Back of The Eye Disorders Market for Biologics, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.47 Back of The Eye Disorders Market for Small Molecules, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.48 Back of The Eye Disorders Market: Distribution by Target Indication
- Table 25.49 Back of The Eye Disorders Market for Diabetic Macular Edema, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.50 Back of The Eye Disorders Market for Neovascular (Wet) Age-Related Macular Degeneration, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.51 Back of The Eye Disorders Market for Diabetic Retinopathy, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.52 Back of The Eye Disorders Market for Glaucoma, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.53 Back of The Eye Disorders Market for Geographic Atrophy, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USDBillion)
- Table 25.54 Back of The Eye Disorders Market for Uveal Melanoma, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.55 Back of The Eye Disorders Market for Retinal Vein Occlusion, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.56 Back of The Eye Disorders Market for Uveitic Macular Edema, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.57 Back of The Eye Disorders Market for Choroidal Neovascularization, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.58 Back of The Eye Disorders Market for Biallelic RPE65 mutation-associated Retinal Dystrophy, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.59 Back of The Eye Disorders Market for Retinopathy of Prematurity, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.60 Back of The Eye Disorders Market for Leber's Hereditary Optic Neuropathy, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.61 Back of the Eye Disorders Market: Distribution by Geographical Regions
- Table 25.62 Back of the Eye Disorders Market in North America: Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.63 Back of the Eye Disorders Market in the US: Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.64 Back of the Eye Disorders Market in Canada: Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion))
- Table 25.65 Back of the Eye Disorders Market in Europe: Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.66 Back of the Eye Disorders Market in Germany: Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.67 Back of the Eye Disorders Market in the UK: Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.68 Back of the Eye Disorders Market in France: Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.69 Back of the Eye Disorders Market in Italy: Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.70 Back of the Eye Disorders Market in Spain: Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.71 Back of the Eye Disorders Market in Rest of Europe: Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.72 Back of The Eye Disorders Market in Asia-Pacific, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.73 Back of The Eye Disorders Market in China, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.74 Back of The Eye Disorders Market in Japan, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.75 Back of The Eye Disorders Market in India, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.76 Back of The Eye Disorders Market in South Korea, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.77 Back of The Eye Disorders Market in Australia, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.78 Back of The Eye Disorders Market in Rest of Asia-Pacific, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.79 Back of The Eye Disorders Market in Middle East and North Africa, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.80 Back of The Eye Disorders Market in Saudi Arabia, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.81 Back of The Eye Disorders Market in Egypt, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.82 Back of The Eye Disorders Market in Rest of Middle East and North Africa, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.83 Back of The Eye Disorders Market in Latin America, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.84 Back of The Eye Disorders Market in Brazil, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.85 Back of The Eye Disorders Market in Argentina, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.86 Back of The Eye Disorders Market in Rest of Latin America, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Billion)
- Table 25.87 Back of the Eye Disorders Market: Distribution by Distribution by Key Players, 2026 (based on revenues generated)
- Table 25.88 Back of the Eye Disorders Market: Distribution by Distribution by Key Players, 2035 (based on forecasted revenues)
- Table 25.89 Back of the Eye Disorders Market for ALPHAGAN(R) P / COMBIGAN(R) Franchise, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 25.90 Back of the Eye Disorders Market for AZARGA(R), Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 25.91 Back of the Eye Disorders Market for Beovu(R) (brolucizumab) / RTH258, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 25.92 Back of the Eye Disorders Market for Duotrav(TM), Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 25.93 Back of the Eye Disorders Market for Eylea HD(R) (aflibercept), Historical Trends (Since 2023) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 25.94 Back of the Eye Disorders Market for Eylea(R) (aflibercept), Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 25.95 Back of the Eye Disorders Market for IZERVAY(TM), Historical Trends (Since 2023) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 25.96 Back of the Eye Disorders Market for KIMMTRAK(R) (tebentafusp-tebn), Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 25.97 Back of the Eye Disorders Market for Latanoprost / DE-130A / (Catioprost) / Catiolanze(R), Historical Trends (Since 2024) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 25.98 Back of the Eye Disorders Market for Lucentis(R) / Ranibizumab, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 25.99 Back of the Eye Disorders Market for Lumigan/Ganfort, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 25.100 Back of the Eye Disorders Market for Lumitin(R) (Conbercept Ophthalmic Solution) / KH902, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 25.101 Back of the Eye Disorders Market for LUXTURNA(R) (voretigene neparvovec-rzyl), Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 25.102 Back of the Eye Disorders Market for NCX 470 / OT-301 / K-911, Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 25.103 Back of the Eye Disorders Market for Omidenepag / Isopropyl / OMLONTI(R) / Eybelis / DE-117, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 25.104 Back of the Eye Disorders Market for ONS-5010 / LYTENAVA(TM), Historical Trends (Since 2025) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 25.105 Back of the Eye Disorders Market for Raxone(R) / Idebenone, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 25.106 Back of the Eye Disorders Market for Rhopressa(R) + ROCKLATAN(TM), Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 25.107 Back of the Eye Disorders Market for Sepetaprost / DE-126 / SETANEO(R) Ophthalmic Solution, Historical Trends (Since 2025) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 25.108 Back of the Eye Disorders Market for Simbrinza(R), Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 25.109 Back of the Eye Disorders Market for SYFOVRE(R) (pegcetacoplan injection), Historical Trends (Since 2023) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 25.110 Back of the Eye Disorders Market for Tafluprost / Timolol Maleate / TAPCOM Combination Ophthalmic Solution, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 25.111 Back of the Eye Disorders Market for Travatan Z(R) / Travoprost, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 25.112 Back of the Eye Disorders Market for Vabysmo (faricimab-sova, RG7716), Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 25.113 Back of the Eye Disorders Market for VYZULTA(R), Historical Trends (Since 2023) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 25.114 Back of the Eye Disorders Market for XIPERE(R) / ARCATUS(R) / ARVN001, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035): Conservative, Base and Optimistic Scenario (USD Million)
List of Figures
- Figure 2.1 Research Methodology: Project Methodology
- Figure 2.2 Research Methodology: Data Sources for Secondary Research
- Figure 2.3 Research Methodology: Robust Quality Control
- Figure 3.1 Market Dynamics: Forecast Methodology
- Figure 3.2 Market Dynamics: Market Assessment Framework
- Figure 4.1 Lessons Learnt from Past Recessions
- Figure 5.1 Executive Summary: Market Landscape
- Figure 5.2 Executive Summary: Market Trends
- Figure 5.3 Executive Summary: Market Forecast and Opportunity Analysis
- Figure 6.1 Stages of Heart Failure
- Figure 7.1 Heart Failure Drugs: Distribution by Stage of Development
- Figure 7.2 Heart Failure Drugs: Distribution by Type of Molecule
- Figure 7.3 Heart Failure Drugs: Distribution by Type of Biologic
- Figure 7.4 Heart Failure Drugs: Distribution by Type of Therapy
- Figure 7.5 Heart Failure Drugs: Distribution by Mechanism of Action
- Figure 7.6 Heart Failure Drugs: Distribution by Route of Administration
- Figure 7.7 Heart Failure Drugs: Distribution by Target Patient Population
- Figure 7.8 Heart Failure Drugs: Distribution by Type of Heart Failure
- Figure 7.9 Heart Failure Drug Developers: Distribution by Year of Establishment
- Figure 7.10 Heart Failure Drug Developers: Distribution by Company Size
- Figure 7.11 Heart Failure Drug Developers: Distribution by Location of Headquarters
- Figure 7.12 Most Active Players: Distribution by Number of Drugs Developed
- Figure 9.1 Clinical Trial Analysis: Distribution by Trial Registration Year
- Figure 9.2 Clinical Trial Analysis: Distribution by Trial Status
- Figure 9.3 Clinical Trial Analysis: Distribution by Trial Registration Year and Trial Status
- Figure 9.4 Clinical Trial Analysis: Distribution of Patients Enrolled by Trial Phase
- Figure 9.5 Clinical Trial Analysis: Distribution of Patients Enrolled by Trial Registration Year
- Figure 9.6 Clinical Trial Analysis: Distribution by Trial Phase
- Figure 9.7 Clinical Trial Analysis: Distribution by Type of Sponsor / Collaborator
- Figure 9.8 Clinical Trial Analysis: Distribution by Patient Gender
- Figure 9.9 Clinical Trial Analysis: Distribution by Study Design
- Figure 9.10 Clinical Trial Analysis: Distribution by Target Patient Population
- Figure 9.11 Most Active Industry Players: Distribution by Number of Clinical Trials
- Figure 9.12 Most Active Non-Industry Players: Distribution by Number of Clinical Trials
- Figure 9.13 Clinical Trial Analysis: Geographical Distribution of Trials and Number of Patients Enrolled
- Figure 9.14 Clinical Trial Analysis: Distribution of Clinical Trials by Trial Status and Geography
- Figure 9.15 Clinical Trial Analysis: Distribution of Patients Enrolled by Trial Status and Geography
- Figure 10.1 Drug Failure Analysis: Distribution by Trial Phase
- Figure 10.2 Drug Failure Analysis: Distribution by Trial Status
- Figure 10.3 Drug Failure Analysis: Distribution by Reason of Drug Discontinuation
- Figure 10.4 Drug Failure Analysis: Distribution by Study Start Year and Year of Discontinuation
- Figure 10.5 Drug Failure Analysis: Distribution by Type of Heart Failure
- Figure 10.6 Drug Failure Analysis: Distribution by Type of Sponsor
- Figure 10.7 Drug Failure Analysis: Distribution by Geographical Region
- Figure 12.1 Global Heart Failure Drugs Market: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035) (USD Billion)
- Figure 12.2 Global Heart Failure Drugs Market: Forecasted Estimates (Till 2035) (USD Billion), Conservative Scenario
- Figure 12.3 Global Heart Failure Drugs Market: Forecasted Estimates (Till 2035) (USD Billion), Optimistic Scenario
- Figure 13.1 Heart Failure Drugs Market for Chronic Heart Failure: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- Figure 13.2 Heart Failure Drugs Market for Others: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- Figure 14.1 Heart Failure Drugs Market for Monotherapies: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- Figure 14.2 Heart Failure Drugs Market for Combination Therapies: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- Figure 15.1 Heart Failure Drugs Market for Small Molecules: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- Figure 15.2 Heart Failure Drugs Market for Biologics: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- Figure 16.1 Heart Failure Drugs Market for Oral Route: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- Figure 16.2 Heart Failure Drugs Market for Subcutaneous Route: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- Figure 16.3 Heart Failure Drugs Market for Intramyocardial Route: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- Figure 16.4 Heart Failure Drugs Market for Intravenous Route: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- Figure 16.5 Heart Failure Drugs Market for Intracoronary Route: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- Figure 17.1 Heart Failure Drugs Market in North America: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- Figure 17.2 Heart Failure Drugs Market in the US: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- Figure 17.3 Heart Failure Drugs Market in Canada: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- Figure 17.4 Heart Failure Drugs Market in Europe: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- Figure 17.5 Heart Failure Drugs Market in Germany: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- Figure 17.6 Heart Failure Drugs Market in France: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- Figure 17.7 Heart Failure Drugs Market in UK: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- Figure 17.8 Heart Failure Drugs Market in Italy: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- Figure 17.9 Heart Failure Drugs Market in Spain: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- Figure 17.10 Heart Failure Drugs Market in Rest of Europe: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- Figure 17.11 Heart Failure Drugs Market in Asia-Pacific: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- Figure 17.12 Heart Failure Drugs Market in China: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- Figure 17.13 Heart Failure Drugs Market in Japan: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- Figure 17.14 Heart Failure Drugs Market in India: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- Figure 17.15 Heart Failure Drugs Market in South Korea: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- Figure 17.16 Heart Failure Drugs Market in Rest of Asia-Pacific: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- Figure 17.17 Heart Failure Drugs Market in Rest of the World: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- Figure 22.1 Heart Failure Drugs Market Empagliflozin / Jardiance: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- Figure 22.2 Heart Failure Drugs Market for Farxiga / Dapagliflozin: Historical Trends (Since 2021) and Forecasted Estimates (Till 2035)
- Figure 22.3 Heart Failure Drugs Market for Kerendia / Finerenone: Historical Trends (Since 2025) and Forecasted Estimates (Till 2035)
- Figure 22.4 Heart Failure Drugs Market for Furoscix / Furosemide: Historical Trends (Since 2023) and Forecasted Estimates (Till 2035)
- Figure 22.5 Heart Failure Drugs Market for Injectafer / Ferinject: Historical Trends (Since 2024) and Forecasted Estimates (Till 2035)
- Figure 22.6 Heart Failure Drugs Market for Verquvo / Vericiguat: Historical Trends (Since 2022) and Forecasted Estimates (Till 2035)
- Figure 22.7 Heart Failure Drugs Market for Sotagliflozin / Inpefa: Historical Trends (Since 2025) and Forecasted Estimates (Till 2035)
- Figure 22.8 Heart Failure Drugs Market for Baxdrostat: Forecasted Estimates (Till 2035)
- Figure 22.9 Heart Failure Drugs Market for Balcinrenone / Dapagliflozin: Forecasted Estimates (Till 2035)
- Figure 22.10 Heart Failure Drugs Market for Vicadrostat / BI 690517: Forecasted Estimates (Till 2035)
- Figure 22.11 Heart Failure Drugs Market for Ziltivekimab: Forecasted Estimates (Till 2035)
- Figure 22.12 Heart Failure Drugs Market for Revascor / Rexlemestrocel L: Forecasted Estimates (Till 2035)
- Figure 22.13 Heart Failure Drugs Market for Maridebart cafraglutid: Forecasted Estimates (Till 2035)
- Figure 22.14 Heart Failure Drugs Market for Omecamtiv Mecarbil: Forecasted Estimates (Till 2035)
- Figure 22.15 Heart Failure Drugs Market for Ferric Derisomaltose: Forecasted Estimates (Till 2035)
- Figure 22.16 Heart Failure Drugs Market for JRM-001: Forecasted Estimates (Till 2035)
- Figure 22.17 Heart Failure Drugs Market for Enavogliflozin / Envlo: Forecasted Estimates (Till 2035)

 心臟衰竭治療醫療設備市場規模、佔有率和成長分析:按器材類型、應用、最終用戶、病患類型、分銷管道和地區分類-2026-2033年產業預測
 鬱血性心臟衰竭治療設備市場:按設備類型、治療方法、最終用戶和分銷管道分類-2026-2032年全球市場預測心臟衰竭治療市場:2026-2032年全球市場預測(依藥物類別、心臟衰竭類型、給藥途徑、作用機制、最終用戶和通路分類)
 鬱血性心臟衰竭治療器材市場規模、佔有率及成長分析:依產品類型、治療方法、模式、病患類型、最終用戶和地區分類-2026-2033年產業預測
 2034年Takotsubo症候群治療市場預測-按產品類型、診斷方法、通路、最終用戶和地區分類的全球分析西拉普利市場:全球市場按劑型、劑量、應用、分銷管道和最終用戶分類的預測-2026-2032年
 全球心臟衰竭檢測設備市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 心臟衰竭藥物市場-全球產業規模、佔有率、趨勢、機會及預測(依藥物類別、通路、地區及競爭格局分類,2021-2031年)
 全球慢性心臟衰竭市場:按地區和國家分析和預測(2025 年至 2035 年)
 心臟衰竭藥物市場報告:2031 年趨勢、預測與競爭分析