


 |
市場調查報告書
商品編碼
2106281
全身性紅斑性狼瘡市場:按分子類型、藥物類別、給藥途徑、療法和地區分類的趨勢和銷售預測(至 2035 年)Systemic Lupus Erythematosus Market by Type of Molecule, Drug Class, Route of Administration, Type of Therapy, Geographical Regions and Sales Forecast - Trends and Forecast, Till 2035 |
||||||

全身性紅斑性狼瘡市場概覽
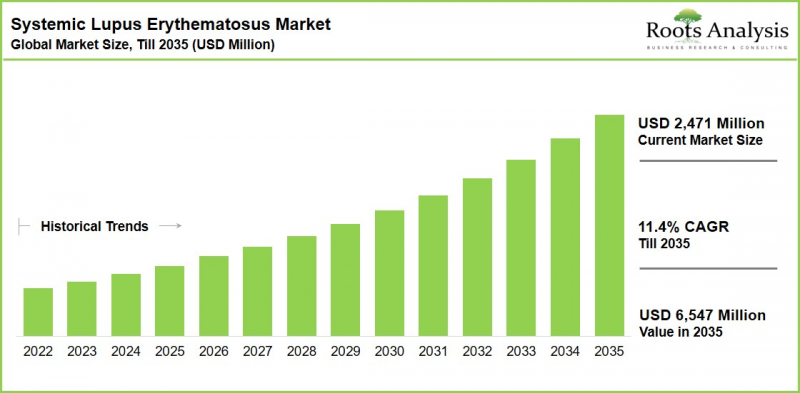
根據 Roots Analysis 的研究,全身性紅斑性狼瘡的市場規模預計將從今年的 24.71 億美元成長到 2035 年的 65.47 億美元,在預測期(到 2035 年)的複合年成長率為 11.4%。
全身性紅斑性狼瘡市場:成長與趨勢
全身性紅斑性狼瘡及相關狼瘡疾病是自體免疫疾病領域中亟待關注的領域。狼瘡是一種慢性發炎性自體免疫疾病,其特徵是症狀多樣且涉及多個器官。根據美國狼瘡基金會統計,美國約有150萬人,全球超過500萬人患有某種形式的狼瘡。此疾病主要分為四種:新生兒狼瘡、盤狀紅斑狼瘡、藥物誘發性狼瘡、全身性紅斑性狼瘡(SLE)。
其中,全身性紅斑性狼瘡(SLE)最為常見,臨床表現也最為複雜,它是一種慢性風濕性自體免疫疾病,涉及免疫活動的失調。在這種疾病中,免疫系統會錯誤地攻擊健康的組織和器官。 SLE可涉及多個器官系統,包括皮膚、關節、腎臟、中樞神經系統和心血管系統。 SLE的確切病因尚不清楚,但其發病被認為是多種因素交互作用的結果,包括遺傳易感性、環境誘因、荷爾蒙影響以及某些藥物。
全身性紅斑性狼瘡(SLE)可發生於任何年齡,但最常見於15至44歲。流行病學數據顯示,成人SLE的發生率有顯著的性別差異,女性患病的可能性是男性的9至13倍。另一方面,兒童中男孩的盛行率相對較高,報告道男孩患病的可能性是女孩的2至3倍。目前的估計表明,全球SLE的發生率約為每10萬人43.7例,這意味著全球約有360萬名患者。
系統性紅斑狼瘡(SLE)的臨床異質性和複雜性促使診斷和治療方法的發展取得了顯著創新。迄今為止,僅有三種藥物獲得監管機構特異性用於治療SLE:葛蘭素史克(GSK)的貝利尤單抗(Benlysta)、阿斯特捷利康(AstraZeneca)的沙普諾(Saphnelo)和瑞美健(RemeGen)的達艾(Ta'ai)。這些藥物目前均與標準療法合併使用。
同時,越來越多的生物製藥公司和研究機構正致力於開發標靶生技藥品和新型免疫調節療法,旨在更有效地應對系統性紅斑狼瘡(SLE)的多種臨床表現。在持續的研發投入、不斷擴充的治療產品線以及精準診斷技術的進步的推動下,預計全球SLE市場在預測期內將實現顯著成長。
全身性紅斑性狼瘡市場
市場規模和機會分析根據以下參數進行分類:
依分子類型
- 生技藥品
- 小分子藥物
藥物類別
- 單株抗體
- 融合蛋白
- 抑制劑
- 免疫調節劑
透過行政途徑
- 靜脈
- 皮下
- 口服
透過治療方法
- 單藥治療
- 聯合治療
按地區
- 北美洲
- 美國
- 加拿大
- 歐洲
- 英國
- 德國
- 法國
- 義大利
- 西班牙
- 其他
- 亞太地區
- 中國
- 日本
- 韓國
- 澳洲
- 中東和北非
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 拉丁美洲
- 巴西
- 阿根廷
全身性紅斑性狼瘡市場:主要細分市場
全身性紅斑性狼瘡市場的區域和細分市場分析
北美目前佔全球全身性紅斑性狼瘡(SLE) 市場 80% 以上的佔有率,預計未來仍將維持最大的市場佔有率。這一主導地位主要得益於 SLE 盛行率的上升、靶向生技藥品的快速普及以及完善的醫療保險報銷機制。同時,歐洲預計將呈現相對較高的成長,預測期內複合年成長率 (CAGR) 預計為 20.8%。這一成長預計將受到即將獲批的新藥和治療途徑擴大的推動。
單株抗體預計將佔最大的市場佔有率。
從藥物類別來看,單株抗體預計將佔市場主導地位,約佔95%的市場。這一市場主導地位主要歸功於已通過核准療法(如Benlysta和Saphnelo)適應症的持續擴展及其在臨床實踐中的廣泛應用。這些療法已證實能夠有效降低疾病活動度、抑制器官損傷並減少對皮質類固醇的依賴。另一方面,抑制劑領域預計在預測期內將呈現更高的成長。推動這一成長的主要因素是口服小分子療法(如Cenerimod、Deucravacitinib和Upadacitinib)的預期獲準。
本報告檢視了全身性紅斑性狼瘡的全球市場,提供了市場概述、背景、市場影響因素分析、市場規模趨勢和預測、按各個細分市場和地區/主要國家進行的詳細分析、競爭格局以及主要公司的概況。
目錄
第1章 背景
第2章:調查方法
第3章 市場動態
第4章 宏觀經濟指標
第5章摘要整理
第6章:引言
- 全身性紅斑性狼瘡概述
- 全身性紅斑性狼瘡的發展機制
- 全身性紅斑性狼瘡的症狀
- 全球全身性紅斑性狼瘡統計數據
- 全身性紅斑性狼瘡治療指南
- 全身性紅斑性狼瘡的診斷
- 前景
第7章全身性紅斑性狼瘡治療藥物的市場狀況
- 調查方法和關鍵參數
- 全身性紅斑性狼瘡治療藥物:市場現狀
第8章:創業生態系分析
- 調查方法和關鍵參數
- 全身性紅斑性狼瘡治療:新創企業生態系統分析
第9章:公司簡介
- 概述
- 全身性紅斑性狼瘡治療領域領先的研發公司
- AbbVie
- Amgen
- AstraZeneca
- Bristol-Myers Squibb
- GSK
- Novartis
- Pfizer
- Roche
- Sanofi
第10章:臨床試驗分析
- 調查方法和關鍵參數
- 全身性紅斑性狼瘡的治療:臨床試驗分析
第11章:藥物研發失敗分析
- 調查方法和關鍵參數
- 全身性紅斑性狼瘡治療藥物研發失敗分析。
第12章 市場影響分析:促進因素、阻礙因素、機會與挑戰
- 市場促進因素
- 市場限制因素
- 市場機遇
- 市場挑戰
第13章:全球全身性紅斑性狼瘡市場
- 關鍵假設和調查方法
- 全球全身性紅斑性狼瘡市場:歷史趨勢與預測
- 主要市場區隔
第14章:全身性紅斑性狼瘡市場:依分子類型分類
- 關鍵假設和調查方法
- 全身性紅斑性狼瘡市場:依分子類型分類
- 生技藥品:過往趨勢與預測
- 小分子化合物:過去趨勢與預測
- 數據三角測量與檢驗
第15章:全身性紅斑性狼瘡市場:依藥物類別分類
- 關鍵假設和調查方法
- 全身性紅斑性狼瘡市場:依藥物類別分類
- 單株抗體:過去趨勢與預測
- 融合蛋白:過去趨勢與預測
- 抑制劑:過去趨勢和預測
- 免疫調節劑:過去趨勢與預測
- 數據三角測量與檢驗
第16章:全身性紅斑性狼瘡市場:依給藥途徑分類
- 關鍵假設和調查方法
- 全身性紅斑性狼瘡市場:依給藥途徑分類
- 靜脈注射:過去趨勢與預測
- 皮下給藥:過去趨勢與預測
- 口服給藥:過去趨勢與預測
- 數據三角測量與檢驗
第17章全身性紅斑性狼瘡市場:依治療方法分類
- 關鍵假設和調查方法
- 全身性紅斑性狼瘡市場:依治療類型分類
- 單藥療法:過往趨勢與預測
- 聯合治療:過往趨勢與預測
- 數據三角測量與檢驗
第18章:全身性紅斑性狼瘡市場:依地區分類
- 關鍵假設和調查方法
- 全身性紅斑性狼瘡市場:依地區分類
- 北美洲
- 歐洲
- 亞太地區
- 中東和北非
- 拉丁美洲
- 數據三角測量與檢驗
第19章:全身性紅斑性狼瘡市場:銷售預測
- 關鍵假設和調查方法
- 全身性紅斑性狼瘡市場:銷售預測
- Benlysta
- Saphnelo
- Telitacicept
- Dapirolizumab Pegol
- Obinutuzumab
- Litifilimab
- Cenerimod
- Deucravacitinib
- Upadacitinib
- Ianalumab
- 數據三角測量與檢驗
第20章 結論
第21章:表格形式數據
第22章 公司和組織列表
SYSTEMIC LUPUS ERYTHEMATOSUS MARKET: OVERVIEW
As per Roots Analysis, the systemic lupus erythematosus market is estimated to grow from USD 2,471 million in the current year to USD 6,547 million by 2035, at a CAGR of 11.4% during the forecast period, till 2035.
SYSTEMIC LUPUS ERYTHEMATOSUS MARKET: GROWTH AND TRENDS
Systemic lupus and related lupus disorders represent a significant area of unmet medical need within the autoimmune disease landscape. Lupus is a chronic inflammatory autoimmune condition characterized by diverse symptoms and multi-organ system involvement. According to the Lupus Foundation of America, approximately 1.5 million individuals in the United States and over 5 million people globally are affected by some form of lupus. The disease is broadly classified into four primary subtypes namely neonatal lupus, discoid lupus, drug-induced lupus, and systemic lupus erythematosus (SLE).
Among these, systemic lupus erythematosus (SLE) is the most prevalent and clinically complex form, classified as a chronic rheumatic autoimmune disorder involving dysregulated immune activity, wherein the immune system erroneously attacks healthy tissues and organs. SLE can affect multiple organ systems, including the skin, joints, kidneys, central nervous system, and cardiovascular system. While the precise etiology of SLE remains unclear, its development is believed to result from a multifactorial interplay of genetic predisposition, environmental triggers, hormonal influences, and certain pharmacological agents.
While systemic lupus erythematosus (SLE) can occur across all age groups, disease onset most commonly occurs between 15 and 44 years of age. Epidemiological data indicate a strong gender disparity in adults, with women being 9 to 13 times more likely to develop SLE than men. Conversely, pediatric incidence patterns suggest a relatively higher prevalence among males, who are reported to be two to three times more likely to develop the condition compared to females. Current estimates indicate a global prevalence of approximately 43.7 cases per 100,000 individuals, translating to nearly 3.6 million affected patients worldwide.
The clinical heterogeneity and complexity of SLE has driven substantial innovation in both diagnostic and therapeutic development. To date, only three therapies have received regulatory approval specifically for SLE treatment: Benlysta by GSK, Saphnelo by AstraZeneca, and Ta'ai developed by RemeGen. These therapies are currently administered in combination with standard-of-care treatment regimens.
In parallel, a growing number of biopharmaceutical companies and research institutions are advancing targeted biologics and novel immunomodulatory approaches aimed at addressing the diverse clinical manifestations of SLE more effectively. Supported by sustained research and development efforts, an expanding therapeutic pipeline, and advancements in precision diagnostics, the global SLE market is positioned for substantial growth over the forecast period.
Growth Drivers: Strategic Enablers of Market Expansion
The systemic lupus erythematosus (SLE) treatment landscape is undergoing a significant transformation, driven by the growing adoption of targeted biologics and continued innovation in drug development. Limitations associated with conventional therapies, including corticosteroids, antimalarials, and immunosuppressants particularly their long-term safety concerns, have accelerated the shift toward advanced treatment modalities such as monoclonal antibodies, B-cell inhibitors, and cell-based therapies. Notably, biologics such as Benlysta and Saphnelo have collectively generated approximately USD 2.7 billion in sales, reflecting strong market uptake and improved clinical outcomes, including enhanced efficacy and steroid-sparing benefits. In parallel, advancements in drug delivery are enhancing patient convenience and adherence, exemplified by the European Union approval of a subcutaneous, self-administered formulation of Saphnelo in December 2025, which has demonstrated a significant reduction in disease activity among patients receiving standard-of-care therapies.
Furthermore, a robust late-stage pipeline including candidates such as Deucravacitinib by Bristol Myers Squibb, Litifilimab by Biogen, and Upadacitinib by AbbVie is expected to introduce novel mechanisms of action that address existing therapeutic gaps, including high placebo response rates, while offering safer and more targeted alternatives. Complementing these advancements, increasing strategic partnerships and investment activities are playing a pivotal role in accelerating innovation, expanding clinical development programs, and strengthening companies' global market presence. A notable example is Royalty Pharma's USD 250 million R&D investment to support Biogen's monoclonal antibody program for Litifilimab, underscoring the growing emphasis on collaborative funding models to advance the development and commercialization of novel lupus therapies.
Market Challenges: Critical Barriers Impeding Progress
The growth of the systemic lupus erythematosus (SLE) market is constrained by significant challenges in both diagnosis and therapeutic development. The heterogeneous nature of systemic lupus erythematosus (SLE) and the frequent overlap of symptoms with those of other conditions often result in significant diagnostic delays. According to the Lupus Foundation of America, patients experience an average delay of nearly seven years before receiving an accurate diagnosis. This delay frequently results in patients being diagnosed at advanced stages of the disease, leading to irreversible organ damage and a reduced pool of patients eligible for timely intervention. These challenges are further intensified by the high attrition rate in SLE drug development, which remains one of the most difficult therapeutic areas within autoimmune disorders. Several candidates, including Rituximab, Abatacept, and Epratuzumab, demonstrated promising results in early-stage trials but failed to achieve desired outcomes in Phase III studies. These setbacks are primarily driven by the heterogeneous nature of the disease, challenges in establishing clinically meaningful endpoints, and limitations in trial design, all of which constrain investment and impede innovation across the SLE therapeutics landscape.
SYSTEMIC LUPUS ERYTHEMATOSUS MARKET: KEY INSIGHTS
The report delves into the current state of the systemic lupus erythematosus market and identifies potential growth opportunities within industry. Some key findings from the report include:
1. More than 130 therapies are currently approved / being investigated across various stages of development for the treatment of systemic lupus erythematosus; of these, 96% are under different phases of clinical trials.
2. Majority (42%) of the SLE drugs are cell therapies, of these, 83% of the therapies are CAR-Ts that are being investigated as monotherapy / in combination under different stages of clinical development.
3. Over 45% of the systemic lupus erythematosus therapy developers are based in Asia-Pacific and rest of the world, with China and Japan emerging as the key hub for these companies
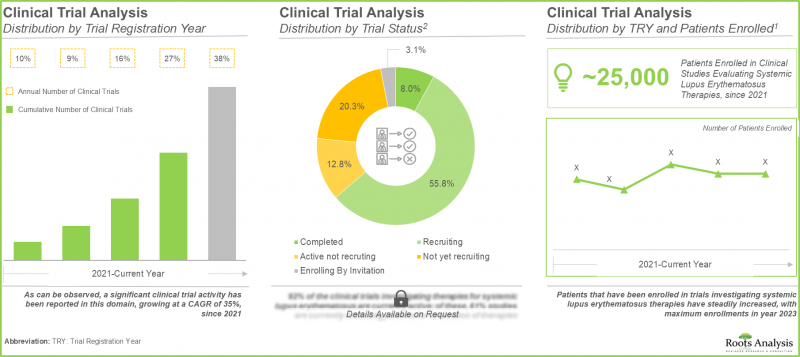
4. Around 25,000 patients have been enrolled in clinical trials underway to investigate SLE therapies, notably, ~10,000 patients were enrolled in last two years.
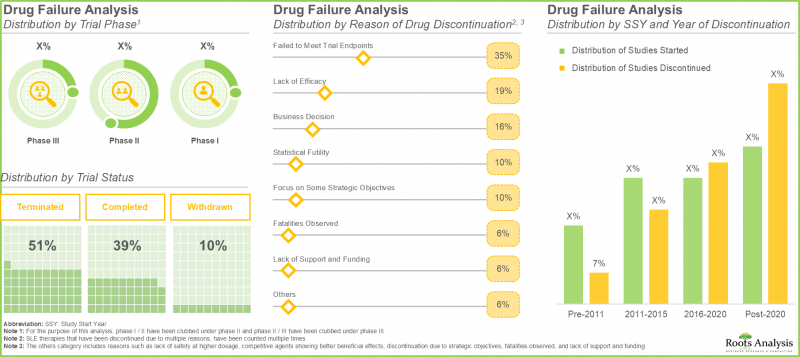
5. More than 30 therapies have been discontinued for systemic lupus erythematosus, notably, majority (~20%) of the therapies were discontinued in a year alone.
6. Close to 55% of the SLE drugs were discontinued in Phase II clinical trials; further, 35% of the drugs were discontinued due to failure in meeting primary endpoints in trials.
7. The overall systemic lupus erythematosus market is likely to be worth USD 2,471 million in the current year and this value is projected to reach around USD 6,547 million in 2035, growing at a CAGR of 11.4%.
8. Given the rising adoption of targeted biologics and ongoing research efforts in this domain, the systemic lupus erythematosus market is expected to witness significant growth in the coming future.
Systemic Lupus Erythematosus Market
The market sizing and opportunity analysis has been segmented across the following parameters:
By Type of Molecule
- Biologics
- Small Molecules
By Drug Class
- Monoclonal Antibodies
- Fusion Proteins
- Inhibitors
- Immunomodulators
By Route of Administration
- Intravenous
- Subcutaneous
- Oral
By Type of Therapy
- Monotherapies
- Combination Therapies
By Geographical Regions
- North America
- US
- Canada
- Europe
- UK
- Germany
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- Australia
- Middle East and North Africa
- Saudi Arabia
- UAE
- Latin America
- Brazil
- Argentina
SYSTEMIC LUPUS ERYTHEMATOSUS MARKET: KEY SEGMENTS
Regional and Segment Analysis of the Systemic Lupus Erythematosus Market
North America is expected to capture the highest market share, accounting for over 80% of the global systemic lupus erythematosus (SLE) market share in the current year. This dominance is primarily driven by a rising prevalence of the disease, rapid adoption of targeted biologic therapies, and well-established reimbursement frameworks. In contrast, Europe is projected to exhibit comparatively faster growth, with an anticipated compound annual growth rate (CAGR) of 20.8% throughout the forecast period, supported by upcoming drug approvals and expanding treatment access.
Monoclonal Antibodies Account for the Largest Systemic Lupus Erythematosus Market Share
From a therapeutic class perspective, monoclonal antibodies are anticipated to dominate the market, capturing approximately 95% share in the current year. This leadership is largely attributed to continued label expansions and strong clinical adoption of approved therapies such as Benlysta and Saphnelo, which have demonstrated efficacy in reducing disease activity, minimizing organ damage, and lowering reliance on corticosteroids. However, the inhibitors segment is expected to witness higher growth over the forecast period, driven by the anticipated approval of oral small-molecule therapies, including Cenerimod, Deucravacitinib, and Upadacitinib.
Intravenous Segment Dominates the Systemic Lupus Erythematosus Market
In terms of route of administration, intravenous therapies are projected to account for the largest market share, nearly 70% in the current year owing to the administration profile of most currently approved and near-term pipeline drugs. Nevertheless, oral therapies are expected to register the fastest growth, with a projected CAGR of 47.3%, supported by their non-invasive nature, ease of administration, and improved patient adherence compared to alternative delivery methods.
Example Players in Systemic Lupus Erythematosus Market
- AbbVie
- Amgen
- AstraZeneca
- Bristol-Myers Squibb
- GSK
- Novartis
- Pfizer
- Roche
- Sanofi
SYSTEMIC LUPUS ERYTHEMATOSUS MARKET: RESEARCH COVERAGE
- Market Sizing and Opportunity Analysis: The report features an in-depth analysis of the systemic lupus erythematosus market, focusing on key market segments, including [A] type of molecule, [B] drug class, [C] route of administration, [D] type of therapy, [E] geographical regions, and [F] sales forecast.
- Systemic Lupus Erythematosus Therapies Market Landscape: A detailed assessment of the overall systemic lupus erythematosus therapies market landscape, along with information on several relevant parameters, such as [A] stage of development, [B] drug class, [C] type of molecule, [D] type of therapy, [E] therapy role, [F] route of administration, [G] drug frequency, [H] patient type, [I] year of establishment, [J] company size, and [K] location of headquarters.
- Start Up Ecosystem Analysis: An in-depth start-up ecosystem analysis based on various relevant parameters, such as [A] stage of development [B] type of molecule, [C] drug class [D] type of therapy, [E] route of administration, [F] year of establishment, [G] company size and [H] location of headquarters.
- Company Profiles: In-depth profiles of key companies based in North America, Europe and Asia-Pacific based on several parameters such as [A] year of establishment, [B] location of headquarters, [C] product portfolio, [D] recent developments and [E] an informed future outlook.
- Clinical Trial Analysis: an analysis of completed and ongoing clinical trials related to atrial fibrillation, based on several relevant parameters, such as [A] trial registration year, [B] enrolled patient population, [C] trial phase, [D] trial status, [E] type of sponsor / collaborator, [F] patient gender, [G] study design, [H] leading industry and non-industry players and [I] geography.
- Drug Failure Analysis: An insightful drug failure analysis, based on several parameters, such as [A] trial phase, [B] trial status, [C] reason of drug discontinuation, [D] study start year, [E] year of discontinuation, [F] type of molecule, and [G] route of administration.
- Market Impact Analysis: An in-depth analysis of the factors that can impact the growth of the market. It also features identification and analysis of key drivers, potential restraints, emerging opportunities, and existing challenges in this domain.
KEY QUESTIONS ANSWERED IN THIS REPORT
- Which are the leading companies in the systemic lupus erythematosus market?
- Which region dominates the systemic lupus erythematosus market?
- What are the key trends observed in the systemic lupus erythematosus market?
- What factors are likely to influence the evolution of this market?
- What are the primary challenges faced by systemic lupus erythematosus therapy developers?
- What is the current and future market size?
- What is the CAGR of this market?
- How is the current and future market opportunity likely to be distributed across key market segments?
REASONS TO BUY THIS REPORT
- The report provides a comprehensive market analysis, offering detailed revenue projections of the overall market and its specific sub-segments. This information is valuable to both established market leaders and emerging entrants.
- The report offers stakeholders a comprehensive overview of the market, including key drivers, barriers, opportunities, and challenges. This information empowers stakeholders to stay abreast of market trends and make data-driven decisions to capitalize on growth prospects.
- The report can aid businesses in identifying future opportunities in any sector. It also helps in understanding if those opportunities are worth pursuing.
- The report helps in identifying customer demand by understanding the needs, preferences, and behavior of the target audience in order to tailor products or services effectively.
- The report equips new entrants with requisite information regarding a particular market to help them build successful business strategies.
- The report allows for more effective communication with the audience and in building strong business relations.
ADDITIONAL BENEFITS
- Complementary PPT Insights Pack
- Complimentary Excel Data Packs for all Analytical Modules in the Report
- 15% Free Content Customization
- Detailed Report Walkthrough Session with Research Team
- Free Updated report if the report is 6-12 months old or older
TABLE OF CONTENTS
1. BACKGROUND
- 1.1. Context
- 1.2. Project Objectives
2. RESEARCH METHODOLOGY
- 2.1. Chapter Overview
- 2.2. Research Assumptions
- 2.2.1. Market Landscape and Market Trends
- 2.2.2. Market Forecast and Opportunity Analysis
- 2.2.3. Comparative Analysis
- 2.3. Database Building
- 2.3.1. Data Collection
- 2.3.2. Data Validation
- 2.3.3. Data Analysis
- 2.4. Project Methodology
- 2.4.1. Secondary Research
- 2.4.1.1. Annual Reports
- 2.4.1.2. Academic Research Papers
- 2.4.1.3. Company Websites
- 2.4.1.4. Investor Presentations
- 2.4.1.5. Regulatory Filings
- 2.4.1.6. White Papers
- 2.4.1.7. Industry Publications
- 2.4.1.8. Conferences and Seminars
- 2.4.1.9. Government Portals
- 2.4.1.10. Media and Press Releases
- 2.4.1.11. Newsletters
- 2.4.1.12. Industry Databases
- 2.4.1.13. Roots Proprietary Databases
- 2.4.1.14. Paid Databases and Sources
- 2.4.1.15. Social Media Portals
- 2.4.1.16. Other Secondary Sources
- 2.4.2. Primary Research
- 2.4.2.1. Types of Primary Research
- 2.4.2.1.1. Qualitative Research
- 2.4.2.1.2. Quantitative Research
- 2.4.2.1.3. Hybrid Approach
- 2.4.2.2. Advantages of Primary Research
- 2.4.2.3. Techniques for Primary Research
- 2.4.2.3.1. Interviews
- 2.4.2.3.2. Surveys
- 2.4.2.3.3. Focus Groups
- 2.4.2.3.4. Observational Research
- 2.4.2.3.5. Social Media Interactions
- 2.4.2.4. Key Opinion Leaders Considered in Primary Research
- 2.4.2.4.1. Company Executives (CXOs)
- 2.4.2.4.2. Board of Directors
- 2.4.2.4.3. Company Presidents and Vice Presidents
- 2.4.2.4.4. Research and Development Heads
- 2.4.2.4.5. Technical Experts
- 2.4.2.4.6. Subject Matter Experts
- 2.4.2.4.7. Scientists
- 2.4.2.4.8. Doctors and Other Healthcare Providers
- 2.4.2.5. Ethics and Integrity
- 2.4.2.5.1. Research Ethics
- 2.4.2.5.2. Data Integrity
- 2.4.2.1. Types of Primary Research
- 2.4.3. Analytical Tools and Databases
- 2.4.1. Secondary Research
- 2.5. Robust Quality Control
3. MARKET DYNAMICS
- 3.1. Chapter Overview
- 3.2. Forecast Methodology
- 3.2.1. Top-down Approach
- 3.2.2. Bottom-up Approach
- 3.2.3. Hybrid Approach
- 3.3. Market Assessment Framework
- 3.3.1. Total Addressable Market (TAM)
- 3.3.2. Serviceable Addressable Market (SAM)
- 3.3.3. Serviceable Obtainable Market (SOM)
- 3.3.4. Currently Acquired Market (CAM)
- 3.4. Forecasting Tools and Techniques
- 3.4.1. Qualitative Forecasting
- 3.4.2. Correlation
- 3.4.3. Regression
- 3.4.4. Extrapolation
- 3.4.5. Convergence
- 3.4.6. Sensitivity Analysis
- 3.4.7. Scenario Planning
- 3.4.8. Data Visualization
- 3.4.9. Time Series Analysis
- 3.4.10. Forecast Error Analysis
- 3.5. Key Considerations
- 3.5.1. Demographics
- 3.5.2. Government Regulations
- 3.5.3. Reimbursement Scenarios
- 3.5.4. Market Access
- 3.5.5. Supply Chain
- 3.5.6. Industry Consolidation
- 3.5.7. Pandemic / Unforeseen Disruptions Impact
- 3.6. Limitations
4. MACRO-ECONOMIC INDICATORS
- 4.1. Chapter Overview
- 4.2. Market Dynamics
- 4.2.1. Time Period
- 4.2.1.1. Historical Trends
- 4.2.1.2. Current and Forecasted Estimates
- 4.2.2. Currency Coverage
- 4.2.2.1. Major Currencies Affecting the Market
- 4.2.2.2. Factors Affecting Currency Fluctuations on the Industry
- 4.2.2.3. Impact of Currency Fluctuations on the Industry
- 4.2.3. Foreign Currency Exchange Rate
- 4.2.3.1. Impact of Foreign Exchange Rate Volatility on the Market
- 4.2.3.2. Strategies for Mitigating Foreign Exchange Risk
- 4.2.4. Recession
- 4.2.4.1. Assessment of Current Economic Conditions and Potential Impact on the Market
- 4.2.4.2. Historical Analysis of Past Recessions and Lessons Learnt
- 4.2.5. Inflation
- 4.2.5.1. Measurement and Analysis of Inflationary Pressures in the Economy
- 4.2.5.2. Potential Impact of Inflation on the Market Evolution
- 4.2.6. Interest Rates
- 4.2.6.1. Interest Rates and Their Impact on the Market
- 4.2.6.2. Strategies for Managing Interest Rate Risk
- 4.2.7. Commodity Flow Analysis
- 4.2.7.1. Type of Commodity
- 4.2.7.2. Origins and Destinations
- 4.2.7.3. Values and Weights
- 4.2.7.4. Modes of Transportation
- 4.2.8. Global Trade Dynamics
- 4.2.8.1. Import Scenario
- 4.2.8.2. Export Scenario
- 4.2.8.3. Trade Policies
- 4.2.8.4. Strategies for Mitigating the Risks Associated with Trade Barriers
- 4.2.8.5. Impact of Trade Barriers on the Market
- 4.2.9. War Impact Analysis
- 4.2.9.1. Russian-Ukraine War
- 4.2.9.2. Israel-Hamas War
- 4.2.10. COVID Impact / Related Factors
- 4.2.10.1. Global Economic Impact
- 4.2.10.2. Industry-specific Impact
- 4.2.10.3. Government Response and Stimulus Measures
- 4.2.10.4. Future Outlook and Adaptation Strategies
- 4.2.11. Other Indicators
- 4.2.11.1. Fiscal Policy
- 4.2.11.2. Consumer Spending
- 4.2.11.3. Gross Domestic Product
- 4.2.11.4. Employment
- 4.2.11.5. Taxes
- 4.2.11.6. Stock Market Performance
- 4.2.11.7. Cross Border Dynamics
- 4.2.1. Time Period
- 4.3. Conclusion
5. EXECUTIVE SUMMARY
6. INTRODUCTION
- 6.1. An Overview of Systemic Lupus Erythematosus
- 6.2. Pathogenesis of Systemic Lupus Erythematosus
- 6.3. Symptoms of Systemic Lupus Erythematosus
- 6.4. Global Statistics of Systemic Lupus Erythematosus
- 6.5. Treatment Guidelines for Systemic Lupus Erythematosus
- 6.6. Diagnosis of Systemic Lupus Erythematosus
- 6.7. Future Perspectives
7. MARKET LANDSCAPE OF SYSTEMIC LUPUS ERYTHEMATOSUS THERAPIES
- 7.1. Methodology and Key Parameters
- 7.2. Systemic Lupus Erythematosus Therapies: Market Landscape
- 7.2.1. Analysis by Stage of Development
- 7.2.2. Analysis by Drug Class
- 7.2.3. Analysis by Type of Molecule
- 7.2.4. Analysis by Type of Therapy
- 7.2.5. Analysis by Therapy Role
- 7.2.6. Analysis by Route of Administration
- 7.2.7. Analysis by Drug Frequency
- 7.2.8. Analysis by Patient Type
- 7.2.9. Analysis by Year of Establishment
- 7.2.10. Analysis by Company Size
- 7.2.11. Analysis by Location of Headquarters
8. STARTUP ECOSYSTEM ANALYSIS
- 8.1. Methodology and Key Parameters
- 8.2. Systemic Lupus Erythematosus Therapies: Startup Ecosystem Analysis
- 8.2.1. Analysis by Stage of Development
- 8.2.2. Analysis by Type of Molecule
- 8.2.3. Analysis by Drug Class
- 8.2.4. Analysis by Type of Therapy
- 8.2.5. Analysis by Route of Administration
- 8.2.6. Analysis by Year of Establishment
- 8.2.7. Analysis by Company Size
- 8.2.8. Analysis by Location of Headquarters
9. COMPANY PROFILES
- 9.1. Overview
- 9.2. Leading Systemic Lupus Erythematosus Therapy Developers
- 9.2.1. AbbVie
- 9.2.1.1. Company Overview
- 9.2.1.2. Business Segments
- 9.2.1.3. SLE Therapies Portfolio
- 9.2.1.4. Key Initiatives
- 9.2.2. Amgen
- 9.2.3. AstraZeneca
- 9.2.4. Bristol-Myers Squibb
- 9.2.5. GSK
- 9.2.6. Novartis
- 9.2.7. Pfizer
- 9.2.8. Roche
- 9.2.9. Sanofi
- 9.2.1. AbbVie
10. CLINICAL TRIAL ANALYSIS
- 10.1. Methodology and Key Parameters
- 10.2. Systemic Lupus Erythematosus Therapies: Clinical Trial Analysis
- 10.2.1. Analysis by Trial Registration Year
- 10.2.2. Analysis by Trial Status
- 10.2.3. Analysis by Trial Registration Year and Trial Status
- 10.2.4. Analysis by Trial Registration Year and Patients Enrolled
- 10.2.5. Analysis by Trial Phase
- 10.2.6. Analysis by Trial Registration Year and Trial Phase
- 10.2.7. Analysis of Patients Enrolled by Trial Phase
- 10.2.8. Analysis by Patient Gender
- 10.2.9. Analysis by Study Design
- 10.2.9.1. Analysis by Design Masking
- 10.2.9.2. Analysis by Intervention Model
- 10.2.9.3. Analysis by Trial Purpose
- 10.2.9.4. Analysis by Allocation
- 10.2.10. Analysis by Target Patient Population
- 10.2.11. Most Active Sponsor / Collaborator: Analysis by Number of Registered Trials
- 10.2.11.1. Analysis by Leading Industry Players
- 10.2.11.2. Analysis by Leading Non-Industry Players
- 10.2.13. Analysis by Geography
- 10.2.13.1. Analysis of Clinical Trials by Trial Status and Geography
- 10.2.13.2. Analysis of Patients Enrolled by Trial Status and Geography
11. DRUG FAILURE ANALYSIS
- 11.1. Methodology and Key Parameters
- 11.2. Systemic Lupus Erythematosus Therapies: Drug Failure Analysis
- 11.2.1. Analysis by Trial Phase
- 11.2.2. Analysis by Trial Status
- 11.2.3. Analysis by Reason of Drug Discontinuation
- 11.2.4. Analysis by Study Start Year and Year of Discontinuation
- 11.2.5. Analysis by Type of Molecule and Drug Class
- 11.2.6. Analysis by Type of Therapy
- 11.2.7. Analysis by Route of Administration
12. MARKET IMPACT ANALYSIS: DRIVERS, RESTRAINTS, OPPORTUNITIES AND CHALLENGES
- 12.1. Market Drivers
- 12.2. Market Restraints
- 12.3. Market Opportunities
- 12.4. Market Challenges
13. GLOBAL SYSTEMIC LUPUS ERYTHEMATOSUS MARKET
- 13.1. Key Assumptions and Methodology
- 13.2. Global Systemic Lupus Erythematosus Market, Historical Trends (since 2023) and Forecasted Estimates (till 2035)
- 13.2.1. Multivariate Scenario Analysis
- 13.2.1.1. Conservative Scenario
- 13.2.1.2. Optimistic Scenario
- 13.2.1. Multivariate Scenario Analysis
- 13.3. Key Market Segmentations
14. SYSTEMIC LUPUS ERYTHEMATOSUS MARKET, BY TYPE OF MOLECULE
- 14.1. Key Assumptions and Methodology
- 14.2. Systemic Lupus Erythematosus Market: Distribution by Type of Molecule
- 14.2.1. Systemic Lupus Erythematosus Market for Biologics, Historical Trends (since 2023) and Forecasted Estimates (till 2035)
- 14.2.2. Systemic Lupus Erythematosus Market for Small Molecules, Forecasted Estimates (till 2035)
- 14.3. Data Triangulation and Validation
15. SYSTEMIC LUPUS ERYTHEMATOSUS MARKET, BY DRUG CLASS
- 15.1. Key Assumptions and Methodology
- 15.2. Systemic Lupus Erythematosus Market: Distribution by Drug Class
- 15.2.1. Systemic Lupus Erythematosus Market for Monoclonal Antibodies, Historical Trends (since 2023) and Forecasted Estimates (till 2035)
- 15.2.2. Systemic Lupus Erythematosus Market for Fusion Proteins, Historical Trends (since 2023) and Forecasted Estimates (till 2035)
- 15.2.3. Systemic Lupus Erythematosus Market for Inhibitors, Forecasted Estimates (till 2035)
- 15.2.4. Systemic Lupus Erythematosus Market for Immunomodulators, Forecasted Estimates (till 2035)
- 15.3. Data Triangulation and Validation
16. SYSTEMIC LUPUS ERYTHEMATOSUS MARKET, BY ROUTE OF ADMINISTRATION
- 16.1. Key Assumptions and Methodology
- 16.2. Systemic Lupus Erythematosus Market: Distribution by Route of Administration
- 16.2.1. Systemic Lupus Erythematosus Market for Intravenous Route, Historical Trends (since 2023) and Forecasted Estimates (till 2035)
- 16.2.2. Systemic Lupus Erythematosus Market for Subcutaneous Route, Historical Trends (since 2023) and Forecasted Estimates (till 2035)
- 16.2.3. Systemic Lupus Erythematosus Market for Oral Route, Forecasted Estimates (till 2035)
- 16.3. Data Triangulation and Validation
17. SYSTEMIC LUPUS ERYTHEMATOSUS MARKET, BY TYPE of THERAPY
- 17.1. Key Assumptions and Methodology
- 17.2. Systemic Lupus Erythematosus Market: Distribution by Type of Therapy
- 17.2.1. Systemic Lupus Erythematosus Market for Monotherapies, Historical Trends (since 2023) and Forecasted Estimates (till 2035)
- 17.2.2. Systemic Lupus Erythematosus Market for Combination Therapies, Historical Trends (since 2023) and Forecasted Estimates (till 2035)
- 17.3. Data Triangulation and Validation
18. SYSTEMIC LUPUS ERYTHEMATOSUS MARKET, BY GEOGRAPHICAL REGIONS
- 18.1. Key Assumptions and Methodology
- 18.2. Systemic Lupus Erythematosus Market: Distribution by Geographical Regions
- 18.2.1. Systemic Lupus Erythematosus Market in North America, Historical Trends (since 2023) and Forecasted Estimates (till 2035)
- 18.2.1.1. Systemic Lupus Erythematosus Market in the US, Historical Trends (since 2023) and Forecasted Estimates (till 2035)
- 18.2.1.2. Systemic Lupus Erythematosus Market in Canada, Historical Trends (since 2023) and Forecasted Estimates (till 2035)
- 18.2.2. Systemic Lupus Erythematosus Market in Europe, Historical Trends (since 2023) and Forecasted Estimates (till 2035)
- 18.2.2.1. Systemic Lupus Erythematosus Market in the UK, Historical Trends (since 2023) and Forecasted Estimates (till 2035)
- 18.2.2.2. Systemic Lupus Erythematosus Market in Germany, Historical Trends (since 2023) and Forecasted Estimates (till 2035)
- 18.2.2.3. Systemic Lupus Erythematosus Market in France, Historical Trends (since 2023) and Forecasted Estimates (till 2035)
- 18.2.2.4. Systemic Lupus Erythematosus Market in Italy, Historical Trends (since 2023) and Forecasted Estimates (till 2035)
- 18.2.2.5. Systemic Lupus Erythematosus Market in Spain, Historical Trends (since 2023) and Forecasted Estimates (till 2035)
- 18.2.2.6. Systemic Lupus Erythematosus Market in Rest of Europe, Historical Trends (since 2023) and Forecasted Estimates (till 2035)
- 18.2.3. Systemic Lupus Erythematosus Market in Asia-Pacific, Historical Trends (since 2023) and Forecasted Estimates (till 2035)
- 18.2.3.1. Systemic Lupus Erythematosus Market in China, Historical Trends (since 2023) and Forecasted Estimates (till 2035)
- 18.2.3.2. Systemic Lupus Erythematosus Market in Japan, Historical Trends (since 2023) and Forecasted Estimates (till 2035)
- 18.2.3.3. Systemic Lupus Erythematosus Market in South Korea, Historical Trends (since 2023) and Forecasted Estimates (till 2035)
- 18.2.3.4. Systemic Lupus Erythematosus Market in Australia, Historical Trends (since 2023) and Forecasted Estimates (till 2035)
- 18.2.4. Systemic Lupus Erythematosus Market in Middle East and North Africa, Historical Trends (since 2023) and Forecasted Estimates (till 2035)
- 18.2.4.1. Systemic Lupus Erythematosus Market in Saudi Arabia, Historical Trends (since 2023) and Forecasted Estimates (till 2035)
- 18.2.4.2. Systemic Lupus Erythematosus Market in the UAE, Historical Trends (since 2023) and Forecasted Estimates (till 2035)
- 18.2.5. Systemic Lupus Erythematosus Market in Latin America, Historical Trends (since 2023) and Forecasted Estimates (till 2035)
- 18.2.5.1. Systemic Lupus Erythematosus Market in Brazil, Historical Trends (since 2023) and Forecasted Estimates (till 2035)
- 18.2.5.2. Systemic Lupus Erythematosus Market in Argentina, Historical Trends (since 2023) and Forecasted Estimates (till 2035)
- 18.2.1. Systemic Lupus Erythematosus Market in North America, Historical Trends (since 2023) and Forecasted Estimates (till 2035)
- 18.4. Data Triangulation and Validation
19. SYSTEMIC LUPUS ERYTHEMATOSUS MARKET, SALES FORECAST
- 19.1. Key Assumptions and Methodology
- 19.2. Systemic Lupus Erythematosus Market: Sales Forecast
- 19.2.1. Systemic Lupus Erythematosus Market for Benlysta, Historical Trends (since 2023) and Forecasted Estimates (till 2035)
- 19.2.2. Systemic Lupus Erythematosus Market for Saphnelo Historical Trends (since 2023) and Forecasted Estimates (till 2035)
- 19.2.3. Systemic Lupus Erythematosus Market for Telitacicept, Historical Trends (since 2023) and Forecasted Estimates (till 2035)
- 19.2.4. Systemic Lupus Erythematosus Market for Dapirolizumab Pegol, Forecasted Estimates (till 2035)
- 19.2.5. Systemic Lupus Erythematosus Market for Obinutuzumab, Forecasted Estimates (till 2035)
- 19.2.6. Systemic Lupus Erythematosus Market for Litifilimab, Forecasted Estimates (till 2035)
- 19.2.7. Systemic Lupus Erythematosus Market for Cenerimod Forecasted Estimates (till 2035)
- 19.2.8. Systemic Lupus Erythematosus Market for Deucravacitinib, Forecasted Estimates (till 2035)
- 19.2.9. Systemic Lupus Erythematosus Market for Upadacitinib, Forecasted Estimates (till 2035)
- 19.2.10. Systemic Lupus Erythematosus Market for Ianalumab, Forecasted Estimates (till 2035)
- 19.3. Data Triangulation and Validation
20. CONCLUDING INSIGHTS
21. TABULATED DATA
22. LIST OF COMPANIES AND ORGANIZATIONS
List of Tables
- Table 7.1 Systemic Lupus Erythematosus Therapies: List of Systemic Lupus Erythematosus Therapies
- Table 7.2 Systemic Lupus Erythematosus Therapy Developers: List of Systemic Lupus Erythematosus Therapy Developers
- Table 8.1 Startup Ecosystem Analysis: List of Systemic Lupus Erythematosus Therapies Developed by Startups
- Table 8.2 Startup Ecosystem Analysis Therapy Developers: List of Systemic Lupus Erythematosus Therapy Startups
- Table 10.1 Systemic Lupus Erythematosus Therapies: List of Clinical Trials, 2021-2025
- Table 11.1 Systemic Lupus Erythematosus Therapies: List of Discontinued Systemic Lupus Erythematosus Therapies
- Table 13.1 Global Systemic Lupus Erythematosus Market: List of Systemic Lupus Erythematosus Therapies Forecasted
- Table 21.1 System Lupus Erythematosus Therapies: Distribution by Stage of Development
- Table 21.2 System Lupus Erythematosus Therapies: Distribution by Drug Class
- Table 21.3 System Lupus Erythematosus Therapies: Distribution by Type of Molecule
- Table 21.4 System Lupus Erythematosus Therapies: Distribution by Type of Therapy
- Table 21.5 System Lupus Erythematosus Therapies: Distribution by Therapy Role
- Table 21.6 System Lupus Erythematosus Therapies: Distribution by Route of Administration
- Table 21.7 System Lupus Erythematosus Therapies: Distribution by Drug Frequency
- Table 21.8 System Lupus Erythematosus Therapies: Distribution by Patient Type
- Table 21.9 System Lupus Erythematosus Therapy Developers: Distribution by Year of Establishment
- Table 21.10 System Lupus Erythematosus Therapy Developers: Distribution by Company Size
- Table 21.11 System Lupus Erythematosus Therapy Developers: Distribution by Location of Headquarters
- Table 21.12 Startup Ecosystem Analysis: Distribution by Stage of Development
- Table 21.13 Startup Ecosystem Analysis: Distribution by Type of Molecule
- Table 21.14 Startup Ecosystem Analysis: Distribution by Drug Class
- Table 21.15 Startup Ecosystem Analysis: Distribution by Type of Therapy
- Table 21.16 Startup Ecosystem Analysis: Distribution by Route of Administration
- Table 21.17 Startup Ecosystem Analysis: Distribution by Year of Establishment
- Table 21.18 Startup Ecosystem Analysis: Distribution by Company Size
- Table 21.19 Startup Ecosystem Analysis: Distribution by Location of Headquarters
- Table 21.20 Clinical Trial Analysis: Distribution by Trial Registration Year
- Table 21.21 Clinical Trial Analysis: Distribution by Trial Status
- Table 21.22 Clinical Trial Analysis: Distribution by Trial Registration Year and Trial Status
- Table 21.23 Clinical Trial Analysis: Distribution by Trial Registration Year and Patients Enrolled
- Table 21.24 Clinical Trial Analysis: Distribution by Trial Phase
- Table 21.25 Clinical Trial Analysis: Distribution by Trial Registration Year and Trial Phase
- Table 21.26 Clinical Trial Analysis: Distribution of Patients Enrolled by Trial Phase
- Table 21.27 Clinical Trial Analysis: Distribution by Patient Gender
- Table 21.28 Clinical Trial Analysis: Distribution by Design Masking
- Table 21.29 Clinical Trial Analysis: Distribution by Intervention Model
- Table 21.30 Clinical Trial Analysis: Distribution by Trial Purpose
- Table 21.31 Clinical Trial Analysis: Distribution by Allocation
- Table 21.32 Clinical Trial Analysis: Distribution by Target Patient Population
- Table 21.33 Most Active Industry Players: Distribution by Number of Clinical Trials
- Table 21.34 Most Active Non-Industry Players: Distribution by Number of Clinical Trials
- Table 21.35 Clinical Trial Analysis: Distribution of Clinical Trials by Trial Status and Geography
- Table 21.36 Clinical Trial Analysis: Distribution of Patients Enrolled by Trial Status and Geography
- Table 21.37 Drug Failure Analysis: Distribution by Phase of Discontinuation
- Table 21.38 Drug Failure Analysis: Distribution by Status of Discontinuation
- Table 21.39 Drug Failure Analysis: Distribution by Reason of Drug Discontinuation
- Table 21.40 Drug Failure Analysis: Distribution by Study Start Year and Year of Discontinuation
- Table 21.41 Drug Failure Analysis: Distribution by Type of Molecule and Drug Class
- Table 21.42 Drug Failure Analysis: Distribution by Type of Therapy
- Table 21.43 Drug Failure Analysis: Distribution by Route of Administration
- Table 21.44 Global Systemic Lupus Erythematosus Market, Historical Trends (since 2023) and Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.45 Systemic Lupus Erythematosus Market: Distribution by Type of Molecule
- Table 21.46 Systemic Lupus Erythematosus Market for Biologics, Historical Trends (since 2023) and Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.47 Systemic Lupus Erythematosus Market for Small Molecules, Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.48 Systemic Lupus Erythematosus Market: Distribution by Drug Class,
- Table 21.49 Systemic Lupus Erythematosus Market for Monoclonal Antibodies, Historical Trends (since 2023) and Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.50 Systemic Lupus Erythematosus Market for Fusion Proteins, Historical Trends (since 2023) and Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.51 Systemic Lupus Erythematosus Market for Inhibitors, Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.52 Systemic Lupus Erythematosus Market for Immunomodulators, Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.53 Systemic Lupus Erythematosus Market: Distribution by Route of Administration
- Table 21.54 Systemic Lupus Erythematosus Market for Intravenous Route, Historical Trends (since 2023) and Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.55 Systemic Lupus Erythematosus Market for Subcutaneous Route, Historical Trends (since 2023) and Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.56 Systemic Lupus Erythematosus Market for Oral Route, Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.57 Systemic Lupus Erythematosus Market: Distribution by Type of Therapy
- Table 21.58 Systemic Lupus Erythematosus Market for Monotherapies, Historical Trends (since 2023) and Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.59 Systemic Lupus Erythematosus Market for Combination Therapies, Historical Trends (since 2023) and Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.60 Systemic Lupus Erythematosus Market: Distribution by Geographical Regions
- Table 21.61 Systemic Lupus Erythematosus Market in North America, Historical Trends (since 2023) and Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.62 Systemic Lupus Erythematosus Market in the US, Historical Trends (since 2023) and Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.63 Systemic Lupus Erythematosus Market in Canada, Historical Trends (since 2023) and Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.64 Systemic Lupus Erythematosus Market in Europe, Historical Trends (since 2023) and Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.65 Systemic Lupus Erythematosus Market in the UK, Historical Trends (since 2023) and Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.66 Systemic Lupus Erythematosus Market in Germany, Historical Trends (since 2023) and Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.67 Systemic Lupus Erythematosus Market in France, Historical Trends (since 2023) and Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.68 Systemic Lupus Erythematosus Market in Italy, Historical Trends (since 2023) and Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.69 Systemic Lupus Erythematosus Market in Spain, Historical Trends (since 2023) and Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.70 Systemic Lupus Erythematosus Market in Rest of Europe, Historical Trends (since 2023) and Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.71 Systemic Lupus Erythematosus Market in Asia-Pacific, Historical Trends (since 2023) and Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.72 Systemic Lupus Erythematosus Market in China, Historical Trends (since 2023) and Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.73 Systemic Lupus Erythematosus Market in Japan, Historical Trends (since 2023) and Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.74 Systemic Lupus Erythematosus Market in South Korea, Historical Trends (since 2023) and Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.75 Systemic Lupus Erythematosus Market in Australia, Historical Trends (since 2023) and Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.76 Systemic Lupus Erythematosus Market in Middle East and North Africa, Historical Trends (since 2023) and Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.77 Systemic Lupus Erythematosus Market in Saudi Arabia, Historical Trends (since 2023) and Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.78 Systemic Lupus Erythematosus Market in UAE, Historical Trends (since 2023) and Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.79 Systemic Lupus Erythematosus Market in Latin America, Historical Trends (since 2023) and Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.80 Systemic Lupus Erythematosus Market in Brazil, Historical Trends (since 2023) and Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.81 Systemic Lupus Erythematosus Market in Argentina, Historical Trends (since 2023) and Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.82 Systemic Lupus Erythematosus Market for Benlysta, Historical Trends (since 2023) and Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.83 Systemic Lupus Erythematosus Market for Saphnelo, Historical Trends (since 2023) and Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.84 Systemic Lupus Erythematosus Market for Telitacicept, Historical Trends (since 2023) and Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.85 Systemic Lupus Erythematosus Market for Dapirolizumab Pegol, Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.86 Systemic Lupus Erythematosus Market for Obinutuzumab, Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.87 Systemic Lupus Erythematosus Market for Litifilimab, Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.88 Systemic Lupus Erythematosus Market for Cenerimod, Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.89 Systemic Lupus Erythematosus Market for Deucravacitinib, Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.90 Systemic Lupus Erythematosus Market for Upadacitinib, Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
- Table 21.91 Systemic Lupus Erythematosus Market for Ianalumab, Forecasted Estimates (till 2035): Conservative, Base and Optimistic Scenario (USD Million)
List of Figures
- Figure 2.1 Research Methodology: Project Methodology
- Figure 2.2 Research Methodology: Data Sources for Secondary Research
- Figure 2.3 Research Methodology: Robust Quality Control
- Figure 3.1 Market Dynamics: Forecast Methodology
- Figure 3.2 Market Dynamics: Market Assessment Framework
- Figure 3.3 Market Dynamics: Example List of Parameters
- Figure 4.1 Historical Analysis of Past Recessions and Lessons Learnt
- Figure 5.1 Executive Summary: Market Landscape
- Figure 5.2 Executive Summary: Market Trends
- Figure 5.3 Executive Summary: Market Forecast and Opportunity Analysis
- Figure 6.1 Pathogenesis of Systemic Lupus Erythematosus
- Figure 6.2 Global Statistics of Systemic Lupus Erythematosus
- Figure 6.3 Diagnosis of Systemic Lupus Erythematosus
- Figure 6.4 Future Perspectives
- Figure 7.1 Systemic Lupus Erythematosus Therapies: Distribution by Stage of Development
- Figure 7.2 Systemic Lupus Erythematosus Therapies: Distribution by Drug Class
- Figure 7.3 Systemic Lupus Erythematosus Therapies: Distribution by Type of Molecule
- Figure 7.4 Systemic Lupus Erythematosus Therapies: Distribution by Type of Therapy
- Figure 7.5 Systemic Lupus Erythematosus Therapies: Distribution by Therapy Role
- Figure 7.6 Systemic Lupus Erythematosus Therapies: Distribution by Route of Administration
- Figure 7.7 Systemic Lupus Erythematosus Therapies: Distribution by Drug Frequency
- Figure 7.8 Systemic Lupus Erythematosus Therapies: Distribution by Patient Type
- Figure 7.9 Systemic Lupus Erythematosus Therapy Developers: Distribution by Year of Establishment
- Figure 7.10 Systemic Lupus Erythematosus Therapy Developers: Distribution by Company Size
- Figure 7.11 Systemic Lupus Erythematosus Therapy Developers: Distribution by Location of Headquarters
- Figure 8.1 Startup Ecosystem Analysis: Distribution by Stage of Development
- Figure 8.2 Startup Ecosystem Analysis: Distribution by Type of Molecule
- Figure 8.3 Startup Ecosystem Analysis: Distribution by Drug Class
- Figure 8.4 Startup Ecosystem Analysis: Distribution by Type of Therapy
- Figure 8.5 Startup Ecosystem Analysis: Distribution by Route of Administration
- Figure 8.6 Startup Ecosystem Analysis: Distribution by Year of Establishment
- Figure 8.7 Startup Ecosystem Analysis: Distribution by Company Size
- Figure 8.8 Startup Ecosystem Analysis: Distribution by Location of Headquarters
- Figure 10.1 Clinical Trial Analysis: Distribution by Trial Registration Year
- Figure 10.2 Clinical Trial Analysis: Distribution by Trial Status
- Figure 10.3 Clinical Trial Analysis: Distribution by Trial Registration Year and Trial Status
- Figure 10.4 Clinical Trial Analysis: Distribution by Trial Registration Year and Patients Enrolled
- Figure 10.5 Clinical Trial Analysis: Distribution by Trial Phase
- Figure 10.6 Clinical Trial Analysis: Distribution by Trial Registration Year and Trial Phase
- Figure 10.7 Clinical Trial Analysis: Distribution by Patients Enrolled by Trial Phase
- Figure 10.9 Clinical Trial Analysis: Distribution by Patient Gender
- Figure 10.10 Clinical Trial Analysis: Distribution by Design Masking
- Figure 10.11 Clinical Trial Analysis: Distribution by Intervention Model
- Figure 10.12 Clinical Trial Analysis: Distribution by Trial Purpose
- Figure 10.13 Clinical Trial Analysis: Distribution by Allocation
- Figure 10.14 Clinical Trial Analysis: Distribution by Target Patient Population
- Figure 10.15 Most Active Industry Players: Distribution by Number of Clinical Trials
- Figure 10.16 Most Active Non-Industry Players: Distribution by Number of Clinical Trials
- Figure 10.17 Clinical Trial Analysis: Distribution of Clinical Trials by Trial Status and Geography
- Figure 10.18 Clinical Trial Analysis: Distribution of Patients Enrolled by Trial Status and Geography
- Figure 11.1 Drug Failure Analysis: Distribution by Trial Phase
- Figure 11.2 Drug Failure Analysis: Distribution by Trial Status
- Figure 11.3 Drug Failure Analysis: Distribution by Reason of Drug Discontinuation
- Figure 11.4 Drug Failure Analysis: Distribution by Study Start Year and Year of Discontinuation
- Figure 11.5 Drug Failure Analysis: Distribution by Type of Therapy
- Figure 11.6 Drug Failure Analysis: Distribution by Route of Administration
- Figure 13.1 Global Systemic Lupus Erythematosus Market, Historical Trends (since 2023) and Forecasted Estimates (till 2035) (USD Million)
- Figure 13.2 Global Systemic Lupus Erythematosus Market, Forecasted Estimates (till 2035): Conservative Scenario (USD Million)
- Figure 13.3 Global Systemic Lupus Erythematosus Market, Forecasted Estimates (till 2035): Optimistic Scenario (USD Million)
- Figure 14.1 Systemic Lupus Erythematosus Market for Biologics, Historical Trends (since 2023) and Forecasted Estimates (till 2035) (USD Million)
- Figure 14.2 Systemic Lupus Erythematosus Market for Small Molecules, Forecasted Estimates (till 2035) (USD Million)
- Figure 15.1 Systemic Lupus Erythematosus Market for Monoclonal Antibodies, Historical Trends (since 2023) and Forecasted Estimates (till 2035) (USD Million)
- Figure 15.2 Systemic Lupus Erythematosus Market for Fusion Proteins, Historical Trends (since 2023) and Forecasted Estimates (till 2035) (USD Million)
- Figure 15.3 Systemic Lupus Erythematosus Market for Inhibitors, Forecasted Estimates (till 2035) (USD Million)
- Figure 15.4 Systemic Lupus Erythematosus Market for Immunomodulators, Forecasted Estimates (till 2035) (USD Million)
- Figure 16.1 Systemic Lupus Erythematosus Market for Intravenous Route, Historical Trends (since 2023) and Forecasted Estimates (till 2035) (USD Million)
- Figure 16.2 Systemic Lupus Erythematosus Market for Subcutaneous Route, Historical Trends (since 2023) and Forecasted Estimates (till 2035) (USD Million)
- Figure 16.3 Systemic Lupus Erythematosus Market for Oral Route, Forecasted Estimates (till 2035) (USD Million)
- Figure 17.1 Systemic Lupus Erythematosus Market for Monotherapies, Historical Trends (since 2023) and Forecasted Estimates (till 2035) (USD Million)
- Figure 17.2 Systemic Lupus Erythematosus Market for Combination Therapies, Historical Trends (since 2023) and Forecasted Estimates (till 2035) (USD Million)
- Figure 18.1 Systemic Lupus Erythematosus Market in North America, Historical Trends (since 2023) and Forecasted Estimates (till 2035) (USD Million)
- Figure 18.2 Systemic Lupus Erythematosus Market in the US, Historical Trends (since 2023) and Forecasted Estimates (till 2035) (USD Million)
- Figure 18.3 Systemic Lupus Erythematosus Market in Canada, Historical Trends (since 2023) and Forecasted Estimates (till 2035) (USD Million)
- Figure 18.4 Systemic Lupus Erythematosus Market in Europe, Historical Trends (since 2023) and Forecasted Estimates (till 2035) (USD Million)
- Figure 18.5 Systemic Lupus Erythematosus Market in the UK, Historical Trends (since 2023) and Forecasted Estimates (till 2035) (USD Million)
- Figure 18.6 Systemic Lupus Erythematosus Market in Germany, Historical Trends (since 2023) and Forecasted Estimates (till 2035) (USD Million)
- Figure 18.7 Systemic Lupus Erythematosus Market in France, Historical Trends (since 2023) and Forecasted Estimates (till 2035) (USD Million)
- Figure 18.8 Systemic Lupus Erythematosus Market in Italy, Historical Trends (since 2023) and Forecasted Estimates (till 2035) (USD Million)
- Figure 18.9 Systemic Lupus Erythematosus Market in Spain, Historical Trends (since 2023) and Forecasted Estimates (till 2035) (USD Million)
- Figure 18.10 Systemic Lupus Erythematosus Market in Rest of Europe, Historical Trends (since 2023) and Forecasted Estimates (till 2035) (USD Million)
- Figure 18.11 Systemic Lupus Erythematosus Market in Asia-Pacific, Historical Trends (since 2023) and Forecasted Estimates (till 2035) (USD Million)
- Figure 18.12 Systemic Lupus Erythematosus Market in China, Historical Trends (since 2023) and Forecasted Estimates (till 2035) (USD Million)
- Figure 18.13 Systemic Lupus Erythematosus Market in Japan, Historical Trends (since 2023) and Forecasted Estimates (till 2035) (USD Million)
- Figure 18.14 Systemic Lupus Erythematosus Market in South Korea, Historical Trends (since 2023) and Forecasted Estimates (till 2035) (USD Million)
- Figure 18.15 Systemic Lupus Erythematosus Market in Australia, Historical Trends (since 2023) and Forecasted Estimates (till 2035) (USD Million)
- Figure 18.16 Systemic Lupus Erythematosus Market in Middle East and North Africa, Historical Trends (since 2023) and Forecasted Estimates (till 2035) (USD Million)
- Figure 18.17 Systemic Lupus Erythematosus Market in Saudi Arabia, Historical Trends (since 2023) and Forecasted Estimates (till 2035) (USD Million)
- Figure 18.18 Systemic Lupus Erythematosus Market in UAE, Historical Trends (since 2023) and Forecasted Estimates (till 2035) (USD Million)
- Figure 18.19 Systemic Lupus Erythematosus Market in Latin America, Historical Trends (since 2023) and Forecasted Estimates (till 2035) (USD Million)
- Figure 18.20 Systemic Lupus Erythematosus Market in Brazil, Historical Trends (since 2023) and Forecasted Estimates (till 2035) (USD Million)
- Figure 18.21 Systemic Lupus Erythematosus Market in Argentina, Historical Trends (since 2023) and Forecasted Estimates (till 2035) (USD Million)
- Figure 19.1 Systemic Lupus Erythematosus Market for Benlysta, Historical Trends (since 2023) and Forecasted Estimates (till 2035) (USD Million)
- Figure 19.2 Systemic Lupus Erythematosus Market for Saphnelo, Historical Trends (since 2023) and Forecasted Estimates (till 2035) (USD Million)
- Figure 19.3 Systemic Lupus Erythematosus Market for Telitacicept, Historical Trends (since 2023) and Forecasted Estimates (till 2035) (USD Million)
- Figure 19.4 Systemic Lupus Erythematosus Market for Dapirolizumab Pegol, Forecasted Estimates (till 2035) (USD Million)
- Figure 19.5 Systemic Lupus Erythematosus Market for Obinutuzumab, Forecasted Estimates (till 2035) (USD Million)
- Figure 19.6 Systemic Lupus Erythematosus Market for Litifilimab, Forecasted Estimates (till 2035) (USD Million)
- Figure 19.7 Systemic Lupus Erythematosus Market for Cenerimod, Forecasted Estimates (till 2035) (USD Million)
- Figure 19.8 Systemic Lupus Erythematosus Market for Deucravacitinib, Forecasted Estimates (till 2035) (USD Million)
- Figure 19.9 Systemic Lupus Erythematosus Market for Upadacitinib, Forecasted Estimates (till 2035) (USD Million)
- Figure 19.10 Systemic Lupus Erythematosus Market for Ianalumab, Forecasted Estimates (till 2035) (USD Million)


