


 |
市場調查報告書
商品編碼
2157133
建築金屬塗層:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)Architectural Metal Coatings - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,2025 年建築金屬塗料市場價值為 59.8 億美元,預計到 2031 年將達到 85.2 億美元,而 2026 年為 63.4 億美元,預測期(2026-2031 年)的複合年成長率為 6.08%。
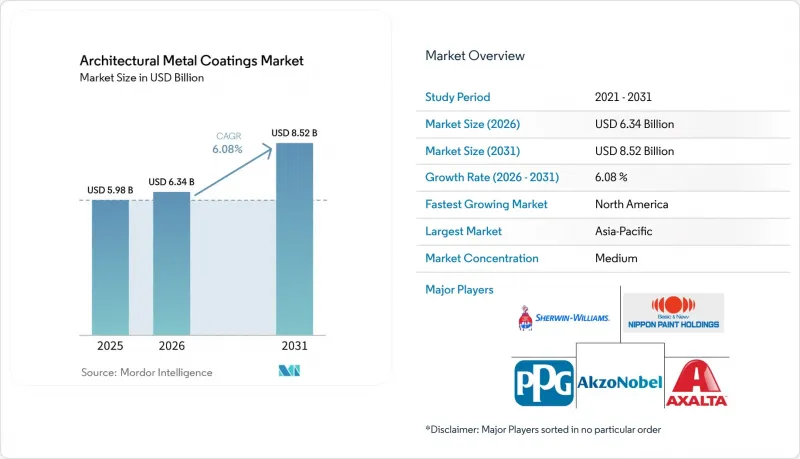
全球建築金屬塗料市場趨勢及洞察。
都市化與金屬建築外牆的擴張
隨著新建築擴大選擇鋼鋁外牆作為設計方案,建築金屬塗料市場將受益於此趨勢。金屬系統能夠滿足倉庫、物流園區、資料中心和科技園區等專案的工期、結構重量和全生命週期預算要求。中國的都市更新改造計畫持續推動著帷幕牆用線圈塗布和擠壓型材塗料的需求。阿克蘇諾貝爾公司推出了「TRINAR SC系列」塗料,該系列產品在東營經濟開發區的一個商業項目中經過長期測試後,獲得了美國建築製造商協會(AAMA)2605認證。四川省發布了關於鋼材表面節能塗料的DB51/T 3266-2025標準,體現了地方政府技術規範的角色。因此,即使新建案成長放緩,建築金屬塗料市場仍能維持由維修驅動的需求基礎。
商業建築擴建與基礎建設維修
建築金屬塗料市場持續受到商業建築和基礎設施維修項目的推動。美國土木工程師協會 (ASCE) 在其 2025 年報告卡中,將美國橋樑、道路和供水系統的評級定為「C」或更低。這種延緩的維護負擔推動了對用於裸露金屬資產的耐用環氧底漆和聚氨酯面漆的需求。在印度的智慧城市計畫中,截至 2025 年 5 月,總額達 15.1 億美元(約 178 億美元)的 8067 個項目中,已有 94% 完成。這些合約還要求使用顏色匹配的現場修復系統,這將帶來初始塗料供應之外的額外收入。數位化配色技術能夠實現跨多個建築專案的迭代工作,但同時也使得更換供應商變得更加困難。
監管複雜性和認證成本
在建築金屬塗料市場,由於標準和產品要求的變化,合規流程往往變得更加繁瑣。 AAMA 2603、AAMA 2604 和 AAMA 2605 的修訂版要求承包商重新評估預處理劑和底漆的化學性能。這可能導致供應商需要重新認證才能再次被列入高價值項目的規範清單。美國塗料協會也指出了全氟烷基和多氟烷基物質 (PFAS) 法規對塗料技術的潛在影響。相關的研發工作成本高昂,且可能無法立即轉換為效益。此外,複雜的法規可能更有利於那些已經擁有測試、法規遵循和文件編制資源的大型配方生產商。
細分市場分析
2025年,含氟聚合物塗料佔據了建築金屬塗料市場47.32%的佔有率。這主要是由於商業建築外觀、帷幕牆和屋頂材料對長期耐候性的要求較高。當需要在整個使用壽命期間保持顏色和光澤時,通常會選擇這類塗料。聚酯塗料則用於屋頂和外牆工程,因為低初始成本會影響材料的選擇。隨著維修工程轉向水性雙組分塗料系統,預計到2031年,聚氨酯塗料的複合年成長率將達到6.74%。在建築金屬塗料行業,當專案需要降低VOC排放和提供持久保護時,通常會採用這類塗料。環氧塗料在沿海環境中作為鍍鋅鋼和鍍鋁鋅鋼的防腐蝕底漆,仍扮演重要角色。
在含氟聚合物系統中,PVDF的供應狀況正成為一項關鍵的規格考量。 2026年初,中國北方R142b的生產調整促使採購決策優先考慮供應穩定性。這可能會影響高階塗料生產線所需的建築級樹脂的供應和價格。阿科瑪位於卡爾弗特城的工廠擴建工程已於2026年6月運作,提高了北美混料商的產能。該公司也宣布,其位於中國常熟的Kynar PVDF產能將提高20%,並於2028年運作。這些投資旨在滿足塗料、鋰離子電池和半導體應用領域的需求。隨著聚氨酯塗料在維修工程中日益普及,建築金屬塗料產業可能會逐步調整樹脂配方。
區域分析
2025年,亞太地區佔全球市場收入的41.05%。這反映了中國、印度、日本、韓國、越南、印尼和馬來西亞等國的需求,這些國家受益於城市更新和新建項目的活性化,建築金屬塗料市場從中受益。在中國,城市更新計畫正在大力推廣使用高性能飾面材料。阿克蘇諾貝爾公司的「TRINAR SC系列」在東營經濟開發區的長期測試中展現了其自清潔性能。在印度的「智慧城市計畫」中,截至2025年5月,8067個項目中已有94%竣工。該計劃涵蓋公共建築、交通基礎設施以及使用金屬覆層和塗層構件的設施。在日本和韓國,建築物外露表面採用技術先進的氟聚合物塗料。
東南亞各國的工業建築、物流設施和商業空間正在增加。佐敦公司宣布,繼其杜拜工廠於2024年完工後,將於2026年在馬來西亞開設一家黏合金屬塗料生產廠。 2026年5月,貝克爾集團透過其合資企業Berger Becker Coatings在納格浦爾開設了一家可再生聚酯樹脂工廠。該廠將於2026年第三季開始商業化生產,初始年產能為9,000噸。本廠採用回收聚對苯二甲酸乙二醇酯(PET)及生物基原料。本地化生產將改善當地混料商和客戶的供應管道。因此,在地化生產以及該地區建築存量的持續成長,共同支撐著建築金屬塗料市場的發展。
受商業建築和塗漆金屬屋頂的更新換代週期推動,預計到2031年,北美市場將以7.03%的複合年成長率成長。陽光地帶城市地區正在部署採用耐用屋頂和牆體系統的新商業項目,這進一步鞏固了建築金屬塗料市場。 2026年6月,PPG工業公司推出了採用Kynar Aquatec PVDF樹脂的「建築更新永不褪色」外牆塗料。該系統提供15年保固,並符合材料保護與性能協會(AMPP)和防腐蝕塗料協會(SSPC)的Paint 47標準。在歐洲,德國、法國和比荷盧經濟聯盟地區仍然關注老舊商業外牆的維修。歐盟生態標章正在重塑全部區域的認證標準。在南美洲,商業建築和物流基礎設施的需求不斷成長;而在中東和非洲,海灣國家的商業和基礎設施項目持續推動市場需求。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 都市化與金屬建築圍護結構的擴張
- 永續和節能建築標準
- 商業建築擴建與基礎建設維修
- 採用低能耗、低揮發性有機化合物和生物基塗料。
- 數位色彩匹配和現場維修的成本效益
- 市場限制因素
- 監管複雜性和認證成本
- 先進系統的高昂開發與實施成本
- PVDF原料的限制以及翻新工程中的顏色匹配問題
- 價值鏈分析
- 波特五力分析
第5章 市場規模與成長預測
- 依樹脂類型
- 螢光樹脂
- 聚酯纖維
- 聚氨酯
- 環氧樹脂
- 其他樹脂類型
- 透過使用
- 屋頂材料和外牆材料
- 牆板和外觀
- 帷幕牆和商店立面
- 窗框和門
- 其他用途
- 最終用戶
- 商業的
- 住宅
- 其他最終用戶
- 按地區
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 東南亞國協
- 其他亞太國家
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 北歐國家
- 俄羅斯
- 其他歐洲國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 南非
- 其他中東和非洲國家
- 亞太地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率和排名分析
- 公司簡介
- Akzo Nobel NV
- Alcea SpA
- Axalta Coating Systems LLC
- Beckers Group
- Hempel A/S
- Jotun
- Kansai Paint Co., Ltd.
- KCC Corporation
- Nippon Paint Holdings Co., Ltd.
- NOROO Paint & Coatings Co., Ltd.
- PPG Industries, Inc.
- RPM International Inc.
- The Sherwin-Williams Company
- TIGER Coatings GmbH & Co. KG
- Tnemec
第7章 市場機會與未來展望
According to Mordor Intelligence, the architectural metal coatings market size was valued at USD 5.98 billion in 2025 and is estimated to grow from USD 6.34 billion in 2026 to reach USD 8.52 billion by 2031, at a CAGR of 6.08% during the forecast period (2026-2031).
Global Architectural Metal Coatings Market Trends and Insights
Urbanization and Metal-Building-Envelope Expansion
The architectural metal coatings market benefits when steel and aluminum envelopes become a preferred design choice for new buildings. Metal systems can meet project timing, structural weight, and lifecycle budget requirements across warehouses, logistics parks, data centers, and technology campuses. China's urban renewal program supports recurring demand for coil-applied and extrusion-applied finishes on curtain-wall geometries. Akzo Nobel N.V. deployed its American Architectural Manufacturers Association (AAMA) 2605-certified TRINAR SC Series after long-term testing at a commercial project in Dongying Economic Development Zone. Sichuan Province issued DB51/T 3266-2025 for energy-saving coatings on steel surfaces, reflecting the role of subnational technical requirements. The architectural metal coatings market can therefore retain a renovation-led demand base when new construction activity weakens.
Expansion of Commercial Construction and Infrastructure Renovation
The architectural metal coatings market receives recurring demand from commercial construction and infrastructure renovation projects. The American Society of Civil Engineers gave U.S. bridges, roads, and water systems grades of C or below in its 2025 report card. That deferred maintenance burden supports demand for durable epoxy primers and polyurethane topcoats on exposed metal assets. India's Smart Cities Mission had completed 94% of 8,067 projects worth INR 1.51 lakh crore (approximately USD 17.8 billion) as of May 2025. Such contracts also require color-matched field repair systems, which can add sales beyond the initial coating supply. Digital color matching supports repeat work across multi-building portfolios and can make supplier changes more difficult.
Regulatory Complexity and Certification Costs
The architectural metal coatings market faces longer compliance processes as standards and product requirements change. Updated AAMA 2603, AAMA 2604, and AAMA 2605 editions require applicators to reassess pretreatment and primer chemistry. This work can require requalification before a supplier returns to specification lists for high-value projects. The American Coatings Association has also identified potential effects from perfluoroalkyl and polyfluoroalkyl substances (PFAS) regulation on coating technologies. The associated development work can be costly and may not create immediate revenue. Complex rules can also favor large formulators that already maintain testing, regulatory, and documentation resources.
Other drivers and restraints analyzed in the detailed report include:
- Sustainable and Energy-Efficient Construction Standards
- Low-Energy, Low-VOC and Bio-Based Coating Adoption
- High Formulation and Application Costs for Advanced Systems
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Fluoropolymer held 47.32% of the architectural metal coatings market size in 2025 because commercial facades, curtain walls, and roofing often require long weatherability warranties. These systems are specified where color retention and gloss retention remain important throughout extended service periods. Polyester coatings serve roofing and cladding projects where lower initial costs influence material selection. Polyurethane is projected to advance at a 6.74% CAGR through 2031 as renovation work shifts toward waterborne 2-component systems. The architectural metal coatings industry uses these systems when a project requires lower VOC emissions and durable protection. Epoxy coatings remain important as corrosion-inhibiting primers for galvanized and Galvalume steel in coastal environments.
PVDF supply availability is becoming an important specification consideration for fluoropolymer systems. R142b output adjustments in northern China during early 2026 shifted procurement decisions toward supply security. This may affect the availability and pricing of architectural-grade resin for premium coating lines. Arkema's Calvert City expansion began operating in June 2026 and has added capacity for North American formulators. The company also announced a 20% Kynar PVDF capacity expansion at Changshu, China, for commissioning in 2028. These investments address demand from coatings, lithium-ion batteries, and semiconductor applications. The architectural metal coatings industry may see a gradual resin mix adjustment as polyurethane systems gain acceptance in renovation projects.
Complete Report Scope:
- By Resin Type
- Fluoropolymer
- Polyester
- Polyurethane
- Epoxy
- Other Resin Types
- By Application
- Roofing and Cladding
- Wall Panels and Facades
- Curtain Walls and Storefronts
- Window Frames and Doors
- Other Applications
- By End-User
- Commercial
- Residential
- Other End-Users
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 41.05% of the market revenue in 2025, reflecting demand across China, India, Japan, South Korea, Vietnam, Indonesia, and Malaysia, where the architectural metal coatings market benefits from urban renewal and new building activity. China supports urban renewal projects using high-performance finishes. Akzo Nobel N.V.'s TRINAR SC Series delivered self-cleaning performance in long-term testing at Dongying Economic Development Zone. India's Smart Cities Mission had completed 94% of 8,067 projects by May 2025. This work includes public buildings, transit assets, and facilities that use metal cladding and coated components. Japan and South Korea maintain technically demanding fluoropolymer specifications for exposed building surfaces.
Southeast Asian economies are adding industrial buildings, logistics facilities, and commercial space. Jotun announced a bonded metallics facility in Malaysia for opening in 2026, following the completion of its Dubai facility in 2024. Beckers Group inaugurated a renewable polyester resin plant in Nagpur through its Berger-Becker Coatings joint venture in May 2026. The plant began commercial production in the 3rd quarter of 2026 with an initial 9,000 metric tons of annual capacity. It uses recycled polyethylene terephthalate (PET) and bio-based feedstocks. Local manufacturing can improve supply access for regional formulators and customers. Both local production and continuing additions to the regional building stock consequently support the architectural metal coatings market.
North America is projected to advance at a 7.03% CAGR through 2031, supported by commercial construction and a replacement cycle for pre-painted metal roofing. Sun Belt metropolitan areas support new commercial projects that use durable roof and wall systems, which strengthen the architectural metal coatings market. PPG Industries, Inc. introduced BUILDING RENEWAL NEVERFADE Exterior Coatings with Kynar Aquatec PVDF resin in June 2026. The system carries a 15-year warranty and meets Association for Materials Protection and Performance (AMPP) SSPC (The Society for Protective Coatings) Paint 47 requirements. Europe remains focused on the renovation of aging commercial facades in Germany, France, and the Benelux region. The European Union Ecolabel is reshaping product qualification across the region. South America gains demand from commercial construction and logistics infrastructure, while the Middle East and Africa remain supported by Gulf commercial and infrastructure projects.
- Akzo Nobel N.V.
- Alcea S.p.A.
- Axalta Coating Systems LLC
- Beckers Group
- Hempel A/S
- Jotun
- Kansai Paint Co., Ltd.
- KCC Corporation
- Nippon Paint Holdings Co., Ltd.
- NOROO Paint & Coatings Co., Ltd.
- PPG Industries, Inc.
- RPM International Inc.
- The Sherwin-Williams Company
- TIGER Coatings GmbH & Co. KG
- Tnemec
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Urbanization and Metal-Building-Envelope Expansion
- 4.2.2 Sustainable and Energy-Efficient Construction Standards
- 4.2.3 Expansion of Commercial Construction and Infrastructure Renovation
- 4.2.4 Low-Energy, Low-VOC and Bio-Based Coating Adoption
- 4.2.5 Digital Color Matching and Field-Repair Economics
- 4.3 Market Restraints
- 4.3.1 Regulatory Complexity and Certification Costs
- 4.3.2 High Formulation and Application Costs for Advanced Systems
- 4.3.3 PVDF Raw-Material and Color-Matching Constraints in Renovation
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Resin Type
- 5.1.1 Fluoropolymer
- 5.1.2 Polyester
- 5.1.3 Polyurethane
- 5.1.4 Epoxy
- 5.1.5 Other Resin Types
- 5.2 By Application
- 5.2.1 Roofing and Cladding
- 5.2.2 Wall Panels and Facades
- 5.2.3 Curtain Walls and Storefronts
- 5.2.4 Window Frames and Doors
- 5.2.5 Other Applications
- 5.3 By End-User
- 5.3.1 Commercial
- 5.3.2 Residential
- 5.3.3 Other End-Users
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 NORDIC Countries
- 5.4.3.6 Russia
- 5.4.3.7 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Akzo Nobel N.V.
- 6.4.2 Alcea S.p.A.
- 6.4.3 Axalta Coating Systems LLC
- 6.4.4 Beckers Group
- 6.4.5 Hempel A/S
- 6.4.6 Jotun
- 6.4.7 Kansai Paint Co., Ltd.
- 6.4.8 KCC Corporation
- 6.4.9 Nippon Paint Holdings Co., Ltd.
- 6.4.10 NOROO Paint & Coatings Co., Ltd.
- 6.4.11 PPG Industries, Inc.
- 6.4.12 RPM International Inc.
- 6.4.13 The Sherwin-Williams Company
- 6.4.14 TIGER Coatings GmbH & Co. KG
- 6.4.15 Tnemec
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


