


 |
市場調查報告書
商品編碼
2157058
塑膠壓力管:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Plastic Pressure Pipes - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
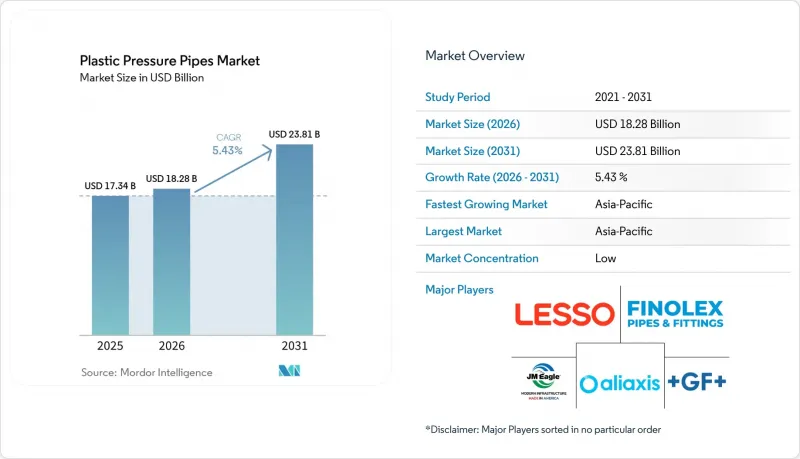
根據 Mordor Intelligence 估計,2025 年塑膠壓力管的市場規模為 173.4 億美元,預計到 2031 年將達到 238.1 億美元,而 2026 年為 182.8 億美元,預測期(2026-2031 年)的複合年成長率為 5.43%。
全球塑膠壓力管市場趨勢與洞察
由於下水道處理管路老化,對更換壓力管道的需求增加
隨著供水和污水處理業者升級老化的供水和污水處理基礎設施,塑膠承壓管道市場將從中受益。 2024年10月,美國環保署 (EPA) 最終確定了相關要求,強制規定飲用水系統中的鉛管必須在10年內進行識別和更換。根據《兩黨基礎設施法案》,聯邦政府已撥款150億美元用於支持鉛管的淘汰。這將使一些先前被推遲的維護工作轉變為由監管合規驅動的高密度聚苯乙烯(HDPE) 和聚氯乙烯-環氧丙烷 (PVC-O) 管道製造商的採購流程。此外,適用於非開挖安裝的管道等級,例如 PE100-RC,在維修規範中變得越來越重要,這可以提高每米管道的安裝效益。美國自來水廠協會 (AWWA) 和國際標準化組織 (ISO) 標準、美國環保署 2024 年修訂的《鉛和銅規則》以及歐盟的《都市污水處理指令》都在影響公共計畫的規範和材料選擇。
擴大高效灌溉和節水基礎設施
高效灌溉正在擴大缺水地區對塑膠加壓管道的潛在需求。中國已發布聚乙烯加壓管道農業灌溉鞍座國家標準(GB/T)19796.1-2025,該標準將於2026年5月生效。印度的「總理農業灌溉計畫」(PM Krishi Sinchayee Yojana)與「飲用水生命線2.0計畫」(Jal Jeevan Mission 2.0)同步實施,旨在支持採購經認證的uPVC管道用於農田供水。根據乙烯基協會(Vinyl Institute)的報告顯示,PVC管道的輸水效率為89%至99%,而土質灌溉管道的輸水效率僅為60%至65%,這為在灌溉項目中採用加壓系統提供了有力支持。 Molecor公司的TR6是一款符合UNE-EN 17176和ISO 16422標準的PN6規格PVC灌溉管道,其剛性比傳統的PVC-U PN6管道高15%。這些要求鼓勵生產既能減少材料用量又能滿足農業用地用水需求的產品。
聚合物和添加劑的價格波動
由於樹脂是主要投入成本,聚合物和添加劑的價格波動是塑膠承壓管市場的限制因素。截至2026年7月,美國塑膠管材及配件製造業生產者物價指數為418.1。該指數反映了乙烯和聚氯乙烯單體價格波動對成本週期的持續影響。價格波動同時影響製造商、承包商和公共工程預算。穩定的樹脂價格將使生產商能夠更自信地規劃產能並推進長期基礎設施競標。印度於2026年7月對聚氯乙烯樹脂設定了最低進口價格,這顯示樹脂價格波動可能導致政策措施的推出。
細分市場分析
2025年,PVC將佔據塑膠壓力管市場48.67%的佔有率。這一地位反映了PVC樹脂成本低廉、承包商技術基礎成熟以及與現有供水和農業系統配件的兼容性。由於PVC-O的靜水壓設計標準為7100 psi(高於傳統PVC的4000 psi),因此其在大口徑城市供水幹管中的應用日益廣泛。更高的耐壓等級允許在相同壓力下使用更薄的管壁,從而減少材料用量和安裝重量。聚丙烯(PP)和其他材料則用於高溫、特殊工業和化學應用領域,在這些領域,PVC存在一些操作限制。
預計到2031年,聚乙烯(PE)市場將以6.24%的複合年成長率成長。聚乙烯廣泛應用於非維修、大口徑熔焊輸水管道和農業滴灌系統。中國萊索公司宣布,其農業專用管線業務將於2026年上半年拓展至非洲和東南亞市場。該公司還宣布,在同一時期開展了高性能複合管道的研究,並獲得了多項相關專利。因此,材料的選擇將取決於所需的耐壓性能、安裝方式、溫度環境和預期使用條件。
區域分析
到2025年,亞太地區將佔全球塑膠承壓管市場的45.06%,預計到2031年將以6.39%的複合年成長率成長。在中國和印度,城市供水、農村供水和農業灌溉計畫是推動市場成長的主要因素。在印度,JJM 2.0將實施一項長期農村供水採購計劃,該計劃將持續到2028年12月。中國的GB/T 19796.1-2025標準將於2026年5月起適用於PE農業灌溉鞍座。在日本和韓國,由於管道網路成熟和對品質的高要求,對老舊管道的更換需求旺盛。在東南亞和南亞,城市擴張和供水網路的發展正在推動市場需求的成長。
在北美和歐洲,市場需求主要集中在維修項目上,包括符合市政和工業規範的PE100-RC和PVC-O等級產品。美國關於鉛製水管的法規明確規定了10年內的更換義務。 ISO 11300-1:2026為在地下水管網的非開挖式翻新中使用PE提供了技術基礎。歐洲的監管要求影響著城市改造計畫中符合EN 12201標準的PE和PVC-O產品的選擇。此外,英國實施了永續水基礎設施投資計劃,以支持國內對承壓管道製造商的需求。
南美洲、中東和非洲是塑膠壓力管道市場的新興成長區域。 2026年4月,GF工業與基礎設施流體解決方案公司與SABESP簽署了一份價值1億瑞士法郎(約合1.265億美元)的契約,旨在對聖保羅州375個城市的供水管網進行現代化改造。沙烏地阿拉伯的水資源戰略目標是到2030年建成超過1萬公里的新輸水基礎設施,投資額達300億美元。中國樂索公司於2025年5月在衣索比亞開設了生產基地,而Polyfab Plastic Middle East FZC則透過其出口網路向多個非洲市場供應產品。由於水資源短缺、基礎設施需求以及出口導向供應商的積極性,這些地區預計將擁有巨大的市場潛力。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 老舊供水和污水管網中壓力管需要更換
- 擴大高效灌溉和節水基礎設施
- 與金屬替代品相比,具有耐腐蝕性和更低的安裝成本。
- 採用軟性聚乙烯和熔接接頭系統進行非開挖維修
- 與新型管道網路中的數位化洩漏檢測和資產監控相容。
- 市場限制因素
- 聚合物和添加劑的價格波動
- 各國的認證和壓力等級要求各不相同。
- 用於加壓應用的認證再生樹脂供應有限。
- 價值鏈分析
- 波特五力分析
第5章 市場規模與成長預測
- 材料
- 聚氯乙烯(PVC)
- 聚乙烯(PE)
- 聚丙烯(PP)
- 其他材料
- 按最終用戶行業分類
- 供水和廢水處理
- 建築/施工
- 農業
- 石油和天然氣
- 礦業
- 產業
- 其他終端用戶產業
- 按地區
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 其他亞太國家
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 其他歐洲國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 南非
- 其他中東和非洲國家
- 亞太地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率和排名分析
- 公司簡介
- Aliaxis Holdings SA
- APL Apollo
- ASTRAL PIPES
- CHINA LESSO
- Finolex Industries Limited
- GF Industry and Infrastructure Flow Solutions
- JM EAGLE, INC.
- KPT Piping System
- LUNA PLAST as na EDB
- Martoni Group
- Molecor
- P&F Global
- Polyfab Plastic Middle East FZC
- Supreme
- TRUFLO
第7章 市場機會與未來展望
According to Mordor Intelligence, the plastic pressure pipes market size was valued at USD 17.34 billion in 2025 and is estimated to grow from USD 18.28 billion in 2026 to reach USD 23.81 billion by 2031, at a CAGR of 5.43% during the forecast period (2026-2031).
Global Plastic Pressure Pipes Market Trends and Insights
Aging Water and Wastewater Networks Requiring Pressure-Pipe Replacement
The plastic pressure pipes market benefits when utilities replace aging water and wastewater infrastructure. The U.S. Environmental Protection Agency finalized requirements in October 2024 for drinking water systems to identify and replace lead service lines within 10 years. Federal funding of USD 15 billion supports the lead service line transition under the Bipartisan Infrastructure Law. This turns a portion of deferred maintenance into a compliance-led procurement cycle for High-Density Polyethylene (HDPE) and PVC-O pipe producers. Rehabilitation specifications also increasingly favor trenchless-compatible grades such as PE100-RC, which can increase revenue per installed meter. American Water Works Association (AWWA) and ISO standards, the 2024 U.S. EPA Lead and Copper Rule revision, and the EU Urban Wastewater Treatment Directive influence public-project specifications and material selection.
Expansion of Efficient Irrigation and Water-Conservation Infrastructure
Efficient irrigation is widening the addressable demand base for the plastic pressure pipes market in water-scarce regions. China issued Guobiao (GB/T) 19796.1-2025 for polyethylene pressure-pipe agricultural irrigation saddles, with implementation effective in May 2026. India's PM Krishi Sinchayee Yojana operates alongside Jal Jeevan Mission 2.0 and supports certified uPVC pipe procurement for farm distribution. The Vinyl Institute reported PVC delivery efficiency of 89%-99%, compared with 60%-65% for earthen canals, which supports the use of pressurized systems in irrigation projects. Molecor's TR6 is a PN6-oriented PVC irrigation pipe certified under UNE-EN 17176 and ISO 16422, with 15% higher stiffness than conventional PVC-U PN6. These requirements support products that use less material while meeting farm-water distribution needs.
Polymer and Additive Price Volatility
Polymer and additive price changes restrain the plastic pressure pipes market because resin is a major input cost. The U.S. Producer Price Index for plastics pipe and pipe fitting manufacturing stood at 418.1 in July 2026. The index reflects continued exposure to ethylene and PVC monomer cost cycles. Price movements affect manufacturers, contractors, and public-project budgets at the same time. A stable resin environment allows producers to plan capacity and bid on longer infrastructure programs with greater certainty. India imposed a minimum import price on PVC resin in July 2026, showing that resin price instability can also prompt policy action.
Other drivers and restraints analyzed in the detailed report include:
- Corrosion Resistance and Lower Installed Cost Versus Metallic Alternatives
- Trenchless Rehabilitation Enabled by Flexible PE and Fusion-Jointed Systems
- Fragmented Certification and Pressure-Rating Requirements Across Countries
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
PVC held 48.67% of the plastic pressure pipes market in 2025. Its position reflects lower resin cost, an established contractor skill base, and compatibility with existing fittings used in water distribution and agricultural systems. PVC-O is gaining use in large-diameter municipal mains because its hydrostatic design basis is 7,100 psi, compared with 4,000 psi for conventional PVC. The higher rating permits thinner walls at comparable pressure levels and can reduce material use and installation weight. Polypropylene (PP) and other materials serve specialized higher-temperature industrial and chemical applications where PVC has operating limitations.
PE is projected to advance at a 6.24% CAGR through 2031. It supports trenchless rehabilitation, large-diameter fusion-welded water transmission, and agricultural drip systems. CHINA LESSO reported expanded specialized agricultural piping into Africa and Southeast Asia in the first half of 2026. The company also reported high-performance composite piping research and several associated patents during that period. Material selection, therefore, reflects the required pressure performance, installation method, temperature exposure, and expected service conditions.
Complete Report Scope:
- By Material
- Polyvinyl Chloride (PVC)
- Polyethylene (PE)
- Polypropylene (PP)
- Other Materials
- By End-User Industry
- Water and Wastewater Treatment
- Building and Construction
- Agriculture
- Oil and Gas
- Mining
- Industrial
- Other End-User Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 45.06% of the plastic pressure pipes market in 2025 and is projected to advance at a 6.39% CAGR through 2031. China and India are supported by municipal water, rural distribution, and agricultural-irrigation programs. JJM 2.0 gives India a long-term rural water procurement program through December 2028. China's GB/T 19796.1-2025 standard has applied to PE agricultural irrigation saddles since May 2026. Japan and South Korea provide replacement demand shaped by mature networks and high-quality requirements. Southeast Asia and South Asia add demand through urban expansion and water-network development.
In North America and Europe, demand is weighted toward rehabilitation, including PE100-RC and PVC-O grades that meet municipal and industrial specifications. The U.S. lead service line rule creates a defined replacement obligation over 10 years. ISO 11300-1:2026 provides a technical basis for PE use in trenchless renewal of underground water networks. European regulatory requirements influence the selection of EN 12201 PE and PVC-O in urban renewal projects. The United Kingdom also has a sustained water infrastructure investment program, which supports domestic demand for pressure pipe producers.
South America and the Middle East and Africa are emerging growth areas in the plastic pressure pipes market. GF Industry and Infrastructure Flow Solutions signed a CHF 100 million (approximately USD 126.5 million) contract with SABESP in April 2026 to modernize water distribution networks in 375 municipalities in Sao Paulo state. Saudi Arabia's water strategy targets more than 10,000 km of new water transmission infrastructure by 2030 and includes USD 30 billion of investment. CHINA LESSO inaugurated an Ethiopian production base in May 2025, while Polyfab Plastic Middle East FZC supplies several African markets through its export network. These regions combine water scarcity, infrastructure needs, and export-oriented supplier activity.
- Aliaxis Holdings SA
- APL Apollo
- ASTRAL PIPES
- CHINA LESSO
- Finolex Industries Limited
- GF Industry and Infrastructure Flow Solutions
- JM EAGLE, INC.
- KPT Piping System
- LUNA PLAST a.s. na EDB
- Martoni Group
- Molecor
- P&F Global
- Polyfab Plastic Middle East FZC
- Supreme
- TRUFLO
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Aging Water and Wastewater Networks Requiring Pressure-Pipe Replacement
- 4.2.2 Expansion of Efficient Irrigation and Water-Conservation Infrastructure
- 4.2.3 Corrosion Resistance and Lower Installed Cost Versus Metallic Alternatives
- 4.2.4 Trenchless Rehabilitation Enabled by Flexible PE and Fusion-Jointed Systems
- 4.2.5 Digital Leak Detection and Asset-Monitoring Compatibility of New Pipe Networks
- 4.3 Market Restraints
- 4.3.1 Polymer and Additive Price Volatility
- 4.3.2 Fragmented Certification and Pressure-Rating Requirements Across Countries
- 4.3.3 Limited Availability of Verified Recycled Resin for Pressure Applications
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Material
- 5.1.1 Polyvinyl Chloride (PVC)
- 5.1.2 Polyethylene (PE)
- 5.1.3 Polypropylene (PP)
- 5.1.4 Other Materials
- 5.2 By End-User Industry
- 5.2.1 Water and Wastewater Treatment
- 5.2.2 Building and Construction
- 5.2.3 Agriculture
- 5.2.4 Oil and Gas
- 5.2.5 Mining
- 5.2.6 Industrial
- 5.2.7 Other End-User Industries
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Aliaxis Holdings SA
- 6.4.2 APL Apollo
- 6.4.3 ASTRAL PIPES
- 6.4.4 CHINA LESSO
- 6.4.5 Finolex Industries Limited
- 6.4.6 GF Industry and Infrastructure Flow Solutions
- 6.4.7 JM EAGLE, INC.
- 6.4.8 KPT Piping System
- 6.4.9 LUNA PLAST a.s. na EDB
- 6.4.10 Martoni Group
- 6.4.11 Molecor
- 6.4.12 P&F Global
- 6.4.13 Polyfab Plastic Middle East FZC
- 6.4.14 Supreme
- 6.4.15 TRUFLO
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

 高純度PVDF管材市場:全球市場預測,2026-2032年
 水輸送聚乙烯(PE)管材市場規模、佔有率及成長分析:依產品類型、壓力等級、直徑、應用、最終用戶及地區分類-2026-2033年產業預測
 2026-2030年全球塑膠管道市場
 2026年全球塑膠管道及管件市場報告2026年全球外置管道柱帽市場報告PVC管材切割器市場按類型、應用和分銷管道分類,全球預測(2026-2032年)
 聚偏二氟乙烯(PVDF)塑膠管:全球市佔率及排名、總收入及需求預測(2025-2031年)
 塑膠管道市場:全球產業分析、規模、佔有率、成長、趨勢及預測(2025-2032)
 美國塑膠管道市場
 塑膠熱管&冷管市場:各材料,各用途,各地區,機會,預測,2017年~2031年