


 |
市場調查報告書
商品編碼
2155564
印度城市物流:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)India Urban Logistics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
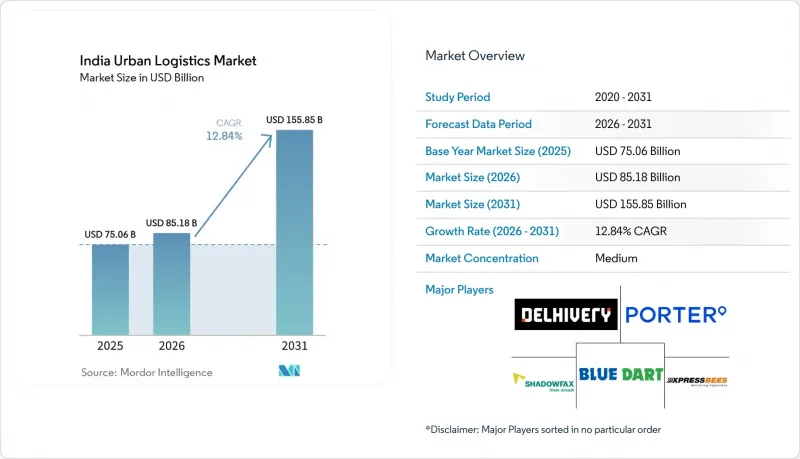
據 Mordor Intelligence 稱,2025 年印度城市物流市場價值為 750.6 億美元,預計到 2031 年將達到 1558.5 億美元,而 2026 年為 851.8 億美元,預測期(2026-2031 年)的複合年成長率為 12.84%。
印度城市物流市場正經歷變革,正規貨運網路、數位化零售需求以及人口密集城市對快速配送的需求(消費者和企業對所有配送的可靠性都有更高的要求)正在推動市場轉型。本報告按服務類型(運輸服務、履約服務等)、配送速度(即時/當日達、次日達等)、客戶類型(B2B、B2C、C2C)、終端用戶行業(電子商務/零售、食品飲料、其他)以及城市(德里、孟買、加爾各答、清奈、其他)進行細分。市場預測以美元計價。
印度城市物流市場趨勢與洞察
電子商務和數位零售的擴張
印度的城市物流市場正展現出來自數位零售的強勁需求。 2025年,B2C和C2C配送合計將佔印度快遞物流業務的55%以上。數位零售在擴大小包裹運輸、履約和退貨處理量的同時,也提升了服務跨城市消費者的賣家對精準訂單處理和可靠配送協調的重視程度。印度品牌股權基金會的報告顯示,2026年,電子商務商品交易總額(GMV)將達到800億美元,年增21%。這種擴張提升了能夠處理大量消費者訂單和波動退貨流的都市區物流中心的價值。能夠靈活運用樞紐輻射式營運模式的營運商,可以隨著需求向現有大都會圈區以外的地區擴展服務範圍。
快速交易和暗店的興起
隨著快消的興起,城市物流正從定時批量配送轉向持續補貨。 Blinkit在2026年9月季度新增了272個分店,使其暗店總數達到1816家。該公司計劃在2027年3月將網點數量擴展至3,000家。同期,Swiggy Instamart也將業務拓展至100個城市,門市數量超過1,100家。這些網路為支援暗店補貨的本地設施、配送車輛和供應商創造了更連續的營運模式,因為庫存需要更靠近消費者,並全天持續補貨。因此,印度城市物流市場需要更高密度的本地樞紐,包括對短程配送車輛和微型倉配的支援。掌握可靠都市區運輸能力的供應商可以確保履行那些透過間歇性外包協議難以實現的服務承諾。
都市區交通堵塞,道路通行受限。
交通堵塞限制了送貨司機和車輛在單次班次內能夠完成的配送數量。此外,即使交通狀況相同,壅塞對路線的影響也會因城區和時間段而異,從而降低了當日達和準時送達所需的可預測性。孟買大都會圈(MMR)、新德里(NCR)、班加羅爾和清奈的交通堵塞尤為突出,這些地區交通堵塞嚴重,裝卸空間有限,影響了商用車輛的通行。業者需要在配送目的地附近建立本地樞紐和暗倉,以降低長途市內運輸帶來的風險。在印度的城市物流市場,如果車輛無法有效率地利用路邊通道,則每次配送的成本就會增加。對於在擁擠城區營運的正規營運商而言,網路設計、本地庫存佈局和嚴格的配送時段管理仍然是應對這些限制的關鍵措施。
細分市場分析
到2025年,運輸服務將佔印度城市物流市場的55.73%。這一細分市場的成長主要得益於大都會圈公路小包裹和貨物運輸的規模。廣泛的陸路網路和現有的車輛運輸能力支撐著該細分市場目前的市場地位。當營運商透過成熟的樞紐運輸大量貨物,然後將其分發到各個城市配送區域時,其優勢尤為顯著。此細分市場也反映了在城市門戶、區域樞紐和最終配送區域之間持續存在的貨物運輸需求。隨著需求轉向更短的配送時限,運輸業者需要提升都市區路線規劃和區域運輸能力,以維持服務品質。
預計到2031年,履約服務將以14.76%的複合年成長率成長,成為成長最快的服務類別。該領域在印度城市物流市場涵蓋倉儲、揀貨包裝、訂單管理和最後一公里配送協調等環節。電商平台越來越傾向於尋找能夠全面負責整體相關營運的單一供應商。隨著快速電商模式的興起,都市區倉儲需求也不斷增加。逆向物流對於時尚和電子產品的退貨仍然至關重要,而增值物流則滿足了套件組裝、溫控和限時都市區配送等需求。
截至2025年,以配送速度分類,標準配送佔印度都市區物流市場規模的68.27%。這反映了網購消費者對價格的敏感度,尤其是在二、三線城市。許多訂單可以透過48至72小時的配送時間以較低的成本完成處理。標準配送並非一成不變;更快的配送方式正在改變人口密集都市區地區消費者的期望。此外,如果能夠提前規劃收件者的收貨時間,定時配送有助於提高配送效率。
預計到2031年,即時送達和當日送達服務將以13.93%的複合年成長率成長。快速商務、隨選食品配送和當日時尚配送服務是推動這項成長的主要動力。這些服務依賴合理的庫存管理和可靠的配送隊伍,因為只有當庫存、車輛裝載能力、調度能力和最終目的地的通行能力協調一致時,才能實現快速送達的承諾。隔日送達在高階消費性電子產品和B2B貨運領域仍發揮重要作用,因為在這些領域,保證送達比即時送達更為重要。更完善的調度系統和更密集的電動摩托車車隊的引入可以縮小都市區郵遞區號區域內標準服務和快遞服務之間的成本差距。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概況及城市物流的重要性
- 市場促進因素
- 電子商務和數位零售的擴張
- 快速交易和暗店的擴張
- 國家物流政策、PM Ghati Shakti計劃以及以商品和服務稅為主導的網路正式化
- 二、三線城市數位商務的擴張
- 透過可互通的物流網路實現的微型市場密度經濟學
- 電動摩托車的經濟性和電池更換。
- 市場限制因素
- 都市區交通堵塞,路肩通行受限。
- 燃料成本和營運費用的波動
- 暗店的土地使用限制以及與附近居民的摩擦
- 對平台的信任度低,非官方車輛運作分散。
- 產業法規結構
- 價值鍊和分銷管道的結構分析
- 城市物流技術的大趨勢和結構性變化
- 波特五力分析
- 成本結構分析
- 城市基礎設施評估
- 永續性和綠色物流
- 地緣政治事件對供應鏈變化的影響
第5章 市場規模及成長預測(價值,2026-2031 年)
- 按服務類型
- 交通運輸服務
- 倉儲和城市儲存服務
- 履約服務
- 逆向物流服務
- 加值物流(VAL)服務
- 配送速度
- 即時出貨及當日送達
- 隔日送達
- 預定交付
- 標準配送
- 依客戶類型
- 企業對企業 (B2B) 交易
- B2C(Business-to-Consumer)
- 個人對個人(C2C)交易
- 按最終用途行業分類
- 電子商務與零售
- 食品/飲料
- 醫療和藥品
- 家用電子產品
- 時尚與服裝
- 汽車零件
- 工業和製造業
- 其他
- 按城市
- 德里(國家首都轄區)
- 孟買(MMR地區)
- 加爾各答
- 班加羅爾
- 清奈
- 海得拉巴
- 艾哈默德巴德
- 板條
- 普納
- 其他城市
第6章 競爭情勢
- 市場集中度
- 關鍵策略趨勢
- 市佔率分析
- 公司簡介
- SmartShift Logistics Solutions Pvt. Ltd.(Porter)
- Delhivery Limited
- Shadowfax Technologies Limited
- Busybees Logistics Solutions Pvt. Ltd.(Xpressbees)
- Blue Dart Express Limited
- Ekart Logistics
- DTDC Express Limited
- LoadShare Networks Private Limited
- Lets Transport Private Limited
- Blowhorn Logistics Private Limited
- Allcargo Logistics Limited
- Safexpress Private Limited
- Aramex India
- Mahindra Logistics Limited
- TCI Express Limited
- FedEx Corporation
- NTEx Transportation Services Pvt Ltd.(ElasticRun)
- Easy Mobile Logistics Hong Kong Limited
- Borzo
- Celcius Logistics Solutions Private Limited
- Pidge Technologies Private Limited
- Pickkup Technologies Private Limited
第7章 市場機會與未來展望
According to Mordor Intelligence, the India urban logistics market size was valued at USD 75.06 billion in 2025 and is estimated to grow from USD 85.18 billion in 2026 to reach USD 155.85 billion by 2031, at a CAGR of 12.84% during the forecast period (2026-2031).
The India urban logistics market is being reshaped by formal freight networks, digital retail demand, and the need for faster delivery in dense cities where consumers and businesses expect greater reliability from every shipment. This report is Segmented by Service Type (Transportation Services, Fulfillment Services, and More), by Delivery Speed (Instant and Same-Day Delivery, Next-Day Delivery, and More), by Customer Type (B2B, B2C, and C2C), by End-Use Industry (E-Commerce and Retail, Food and Beverage, and More), and by City (Delhi, Mumbai, Kolkata, Chennai, and More). The Market Forecasts are Provided in Terms of Value (USD).
India Urban Logistics Market Trends and Insights
E-Commerce and Digital Retail Expansion
The India urban logistics market receives a major demand signal from digital retail. B2C and C2C shipments together represented more than 55% of India's express logistics activity in 2025. Digital retail broadens the addressable volume for parcel transport, fulfillment, and returns, while also increasing the importance of accurate order handling and reliable delivery coordination for sellers that serve consumers across multiple cities. India Brand Equity Foundation reported e-commerce gross merchandise value of USD 80 billion in FY 2026, with 21% year-over-year growth. This expansion places greater value on urban hubs that can serve both high-volume consumer orders and variable return flows. Providers with adaptable hub-and-spoke operations can extend coverage as demand expands beyond established metropolitan catchments.
Quick Commerce and Dark-Store Proliferation
Quick commerce is shifting urban logistics from scheduled batches toward continuous replenishment. Blinkit reached 1,816 dark stores after adding 272 locations in the September quarter of FY2026 and plans to reach 3,000 locations by March 2027. Swiggy Instamart crossed 1,100 stores and expanded to 100 cities during the period. These networks require inventory to be positioned close to consumers and replenished throughout the day, creating a more continuous operating pattern for local facilities, delivery fleets, and suppliers that support dark-store replenishment. The India urban logistics market, therefore, needs denser local capacity, including short-haul fleets and micro-fulfillment support. Providers that control reliable city capacity can support service commitments that are difficult to meet through intermittent subcontracting.
Urban Congestion and Limited Curb Access
Congestion limits the number of delivery stops that a rider or vehicle can complete in a shift. It also reduces the predictability needed for same-day and scheduled delivery commitments, because the same traffic conditions can affect routes differently across urban districts and at different times of the working day. The constraint is most significant in Mumbai MMR, Delhi NCR, Bengaluru, and Chennai, where dense traffic and limited loading space affect commercial vehicle movements. Providers need local spokes and dark stores close to delivery endpoints to reduce exposure to long urban trips. The India urban logistics market faces higher per-delivery costs when vehicles cannot access curbs efficiently. Network design, local inventory placement, and delivery-slot discipline remain important responses to this constraint for organized providers serving congested city centers.
Other drivers and restraints analyzed in the detailed report include:
- National Logistics Policy, PM GatiShakti and GST-Led Network Formalization
- Electric Two-Wheeler and Battery-Swapping Economics
- Fuel and Operating Cost Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Transportation services held 55.73% of the India urban logistics market share in 2025. The segment remains anchored by the scale of road-based parcel and freight movement across metropolitan areas. Large surface networks and existing fleet capacity support its current position, particularly where operators move high volumes through established hubs before distributing shipments into individual urban delivery zones. The segment also reflects the continuing need to move goods between city gateways, local hubs, and final delivery zones. Transportation providers need to improve urban routing and local capacity to protect service quality as demand shifts toward shorter delivery windows.
Fulfillment services are forecast to expand at a 14.76% CAGR through 2031, the fastest pace among service types. This part of the India urban logistics market size includes warehousing, pick-and-pack operations, order management, and last-mile coordination. E-commerce platforms increasingly seek a single accountable provider across these linked activities. Urban storage is growing alongside the quick-commerce dark-store model. Reverse logistics remains relevant for fashion and electronics returns, while value-added logistics supports requirements such as kitting, temperature control, and time-definite urban distribution.
Standard delivery held 68.27% of the India urban logistics market size by delivery speed in 2025. Its position reflects price sensitivity among online shoppers, especially in Tier 2 and Tier 3 cities. Many orders can be served within a 48-72-hour delivery window at a lower cost. Standard delivery is not static because faster options are changing customer expectations in dense urban areas. Scheduled delivery also improves the use of routes where recipient availability can be planned in advance.
Instant and same-day delivery is forecast to grow at a 13.93% CAGR through 2031. Quick commerce, on-demand food delivery, and same-day fashion services are driving this pace. These services require close inventory placement and dependable rider availability, because a short delivery promise depends on the coordinated availability of stock, vehicle capacity, dispatch capability, and access to the final address. Next-day delivery remains important for premium consumer electronics and B2B shipments where the delivery promise matters more than immediate arrival. Better dispatch systems and denser electric two-wheeler fleets can narrow the cost difference between standard and faster services in urban pin codes.
Complete Report Scope:
- By Service Type
- Transportation Services
- Warehousing and Urban Storage Services
- Fulfillment Services
- Reverse Logistics Services
- Value-Added Logistics (VAL) Services
- By Delivery Speed
- Instant and Same-Day Delivery
- Next-Day Delivery
- Scheduled Delivery
- Standard Delivery
- By Customer Type
- Business-to-Business (B2B)
- Business-to-Consumer (B2C)
- Consumer-to-Consumer (C2C)
- By End-Use Industry
- E-commerce and Retail
- Food and Beverage
- Healthcare and Pharmaceuticals
- Consumer Electronics
- Fashion and Apparel
- Automotive Parts
- Industrial and Manufacturing
- Others
- By City
- Delhi (NCR Region)
- Mumbai (MMR Region)
- Kolkata
- Bengaluru
- Chennai
- Hyderabad
- Ahmedabad
- Surat
- Pune
- Rest of Cities
List of Companies Covered in this Report:
- SmartShift Logistics Solutions Pvt. Ltd. (Porter)
- Delhivery Limited
- Shadowfax Technologies Limited
- Busybees Logistics Solutions Pvt. Ltd. (Xpressbees)
- Blue Dart Express Limited
- Ekart Logistics
- DTDC Express Limited
- LoadShare Networks Private Limited
- Lets Transport Private Limited
- Blowhorn Logistics Private Limited
- Allcargo Logistics Limited
- Safexpress Private Limited
- Aramex India
- Mahindra Logistics Limited
- TCI Express Limited
- FedEx Corporation
- NTEx Transportation Services Pvt Ltd. (ElasticRun)
- Easy Mobile Logistics Hong Kong Limited
- Borzo
- Celcius Logistics Solutions Private Limited
- Pidge Technologies Private Limited
- Pickkup Technologies Private Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview and Importance of Urban Logistics
- 4.2 Market Drivers
- 4.2.1 E-Commerce and Digital Retail Expansion
- 4.2.2 Quick Commerce and Dark-Store Proliferation
- 4.2.3 National Logistics Policy, PM Gati Shakti and GST-Led Network Formalization
- 4.2.4 Tier-2 and Tier-3 Digital Commerce Expansion
- 4.2.5 Micro-Market Density Economics Enabled by Interoperable Logistics Networks
- 4.2.6 Electric Two-Wheeler and Battery-Swapping Economics
- 4.3 Market Restraints
- 4.3.1 Urban Congestion and Limited Curb Access
- 4.3.2 Fuel and Operating Cost Volatility
- 4.3.3 Dark-Store Land-Use Constraints and Neighborhood Friction
- 4.3.4 Low Platform Trust and Fragmented Informal Fleet Operations
- 4.4 Industry Regulatory Framework
- 4.5 Value Chain and Distribution Channel Architecture Analysis
- 4.6 Technology Megatrends and Structural Shifts in Urban Logistics
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Rivalry Among Competitors
- 4.8 Cost Structure Analysis
- 4.9 Urban Infrastructure Assessment
- 4.10 Sustainability and Green Logistics
- 4.11 Impact of Geo-Political Events on Supply Chain Shifts
5 Market Size and Growth Forecasts (Value, 2026-2031)
- 5.1 By Service Type
- 5.1.1 Transportation Services
- 5.1.2 Warehousing and Urban Storage Services
- 5.1.3 Fulfillment Services
- 5.1.4 Reverse Logistics Services
- 5.1.5 Value-Added Logistics (VAL) Services
- 5.2 By Delivery Speed
- 5.2.1 Instant and Same-Day Delivery
- 5.2.2 Next-Day Delivery
- 5.2.3 Scheduled Delivery
- 5.2.4 Standard Delivery
- 5.3 By Customer Type
- 5.3.1 Business-to-Business (B2B)
- 5.3.2 Business-to-Consumer (B2C)
- 5.3.3 Consumer-to-Consumer (C2C)
- 5.4 By End-Use Industry
- 5.4.1 E-commerce and Retail
- 5.4.2 Food and Beverage
- 5.4.3 Healthcare and Pharmaceuticals
- 5.4.4 Consumer Electronics
- 5.4.5 Fashion and Apparel
- 5.4.6 Automotive Parts
- 5.4.7 Industrial and Manufacturing
- 5.4.8 Others
- 5.5 By City
- 5.5.1 Delhi (NCR Region)
- 5.5.2 Mumbai (MMR Region)
- 5.5.3 Kolkata
- 5.5.4 Bengaluru
- 5.5.5 Chennai
- 5.5.6 Hyderabad
- 5.5.7 Ahmedabad
- 5.5.8 Surat
- 5.5.9 Pune
- 5.5.10 Rest of Cities
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Key Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Geographic/Network Coverage, Products and Services, and Recent Developments)
- 6.4.1 SmartShift Logistics Solutions Pvt. Ltd. (Porter)
- 6.4.2 Delhivery Limited
- 6.4.3 Shadowfax Technologies Limited
- 6.4.4 Busybees Logistics Solutions Pvt. Ltd. (Xpressbees)
- 6.4.5 Blue Dart Express Limited
- 6.4.6 Ekart Logistics
- 6.4.7 DTDC Express Limited
- 6.4.8 LoadShare Networks Private Limited
- 6.4.9 Lets Transport Private Limited
- 6.4.10 Blowhorn Logistics Private Limited
- 6.4.11 Allcargo Logistics Limited
- 6.4.12 Safexpress Private Limited
- 6.4.13 Aramex India
- 6.4.14 Mahindra Logistics Limited
- 6.4.15 TCI Express Limited
- 6.4.16 FedEx Corporation
- 6.4.17 NTEx Transportation Services Pvt Ltd. (ElasticRun)
- 6.4.18 Easy Mobile Logistics Hong Kong Limited
- 6.4.19 Borzo
- 6.4.20 Celcius Logistics Solutions Private Limited
- 6.4.21 Pidge Technologies Private Limited
- 6.4.22 Pickkup Technologies Private Limited
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

 全球災害救援物流市場(2026-2030 年)
 寵物物流市場:全球市場預測,2026-2032年
 本地配送網路市場預測至2034年-按服務地點類型、網路模型、服務、技術、位置類型和區域分類的全球分析伸縮式整平機市場:全球市場預測,2026-2032年2026-2030年全球工業物流市場2026-2030年全球電子商務及物流市場城市物流市場預測至2034年-按服務類型、配送模式、車輛類型、技術、最終用戶和地區分類的全球分析智慧物流市場預測至2034年-按解決方案類型、技術、部署模式、組織規模、最終用戶和地區分類的全球分析
 JIT(即時)物流市場規模、佔有率和成長分析:按服務類型、運輸方式、最終用戶、公司規模、部署和地區分類 - 行業預測,2026-2033 年碼頭邊緣整平機市場:全球市場預測,2026-2032年