


 |
市場調查報告書
商品編碼
2155272
基於視覺的品質分析:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031)Vision-Based Quality Analytics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
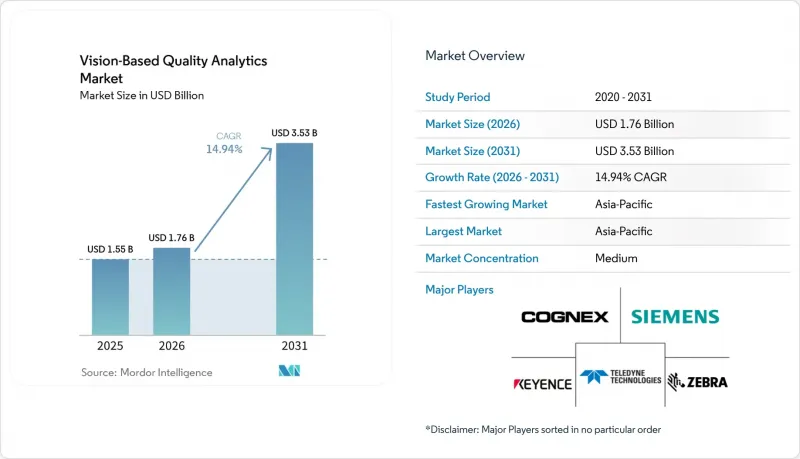
根據 Mordor Intelligence 預測,基於視覺的品質分析市場規模將從 2025 年的 15.5 億美元和 2026 年的 17.6 億美元成長到 2031 年的 35.3 億美元,2026 年至 2031 年的年複合成長率(CAGR)為 14.94%。
全球基於視覺的品質分析市場趨勢和洞察
從人工檢測迅速轉向人工智慧驅動的自動化缺陷檢測。
隨著產量增加和缺陷容差收窄,人工檢測變得越來越困難。一家消費品製造商旨在以基於邊緣的無監督異常檢測取代人工抽樣檢測,從而將工廠中從事檢測工作的員工比例從 40% 降低到 4%。由於時間和成本的限制,製造商將檢測範圍擴展到以前未充分覆蓋的流程,這帶動了基於視覺的品質分析市場的發展。台積電正在利用 NVIDIA Metropolis 和 NVIDIA TAO Toolkit 來提高奈米級缺陷分類的準確性,同時減少因條件變化而需要進行的迭代標註和重新訓練。一項使用 22,410 張影像對 VCSEL 進行檢測的研究表明,準確率達到了 98.7%,並將單件檢測時間從 17.7 秒縮短至 1.5 秒。研究還報告稱,檢測時間減少了 89%,硬體投資回收期為 4.5 個月。
電動車電池和半導體製造領域對高精度視覺分析的需求日益成長。
在電池和半導體製造中,嚴格的品質控制至關重要,因為即使是單一缺陷也可能危及整個批次、模組或成品的品質。因此,基於視覺的品質分析市場在這些生產環境中具有很高的應用價值。在 2026 年 CVPR 研討會上,研究人員提出了 AOI-SSL,這是一種用於焊線半導體檢測的自監督學習方法,它利用小規模檢測資料集對特定領域的視覺變壓器進行預訓練。 LIBAD 基準測試於 2026 年 8 月發布,包含來自真實卷對卷生產線的 744 個電極樣本,涵蓋 11 個缺陷類別。此基準測試結合了可見光成像、高解析度 X 光和線上 X 光成像技術。圓柱形、棱柱形和軟包等不同的電池形狀要求檢測系統能夠處理各種結構和缺陷模式。
前期實施成本高,且與原有設備整合複雜。
基於視覺的品質分析市場在採用過時PLC驅動設備和資料基礎設施有限的工廠中面臨許多實際障礙。通常,人工智慧檢測系統在部署到全面生產之前,需要在試點運行期間進行人工回退、評估里程碑以及與製造執行系統 (MES) 的連接。對於中小廠商而言,市售自動化光學檢測系統的成本是一大障礙。 VCSEL 的研究強調了硬體受限的架構,這些架構專為無法部署現有大規模平台的環境而設計。此外,老舊工廠可能缺乏整合攝影機、邊緣節點和企業系統所需的高吞吐量、低延遲連線。 Neurala 報告稱,其 L-DNN 技術無需雲端連接或 GPU 硬體即可進行訓練和推理,從而解決了部署能力有限的工廠所面臨的挑戰。
細分市場分析
到2025年,「缺陷和異常分析」將佔據32.67%的市場佔有率,成為基於視覺的品質分析市場中最大的分析類別。電子、汽車和食品加工產業的生產線利用這個類別來檢測表面和結構,以確定產品是否合格。已實施的自動化光學檢測系統會產生可與製造執行系統共用的分類記錄。尺寸和測量分析支持多品種、小批量生產中的精確測量。模式和分類分析有助於汽車和電子產品組裝過程中的組件識別和可追溯性。
預計到2031年,預測性品質分析將以15.56%的複合年成長率成長。在基於視覺的品質分析產業,預測工具正被廣泛採用,因為最終階段的檢測無法挽回已消耗的材料和加工成本。過程品質分析將檢測結果與上游製程變數關聯起來,以支援早期糾正措施。其他類型的分析包括在各個生產現場湧現的專用應用。 SECOM的一項研究表明,封閉回路型模型如何適應不斷變化的過程條件。
預計到2025年,傳統的基於規則的分析將佔據43.67%的市場佔有率,這反映了基於固定閾值、邊緣檢測濾波器和幾何規則的系統被廣泛採用。這些系統在產品和運作條件穩定的場景下仍然有效。基於視覺的品質分析市場仍然依賴基於規則的方法來檢驗任務。當光照、產品差異或程式參數改變時,其限制就會更加明顯。一項系統性綜述報告稱,基於YOLO演算法的方法在PCB缺陷資料集上實現了98.6%的mAP(平均準確率)。
預計到2031年,基於人工智慧/深度學習的分析市場將以15.63%的複合年成長率成長。在基於視覺的品質分析產業,當手動定義的規則無法充分應對多樣化或複雜的特徵時,深度學習便被廣泛應用。根據同一份報告,HSA-RTDETR在PCB檢測任務中實現了96.9%的平均精度均值(mAP),幀率為66.2 FPS,並檢測到了六個缺陷。混合人工智慧和基於規則的分析將人工智慧應用於不斷變化的環境,同時保留檢驗的規則以實現可預測的檢查。在「Vision 2026」展示會上,SICK宣布對其Nova平台進行功能更新,包括用於3D資料處理和基於神經網路的目標偵測的工具。
區域分析
預計到2025年,亞太地區將佔據36.12%的市場佔有率,並在2031年之前以16.21%的複合年成長率成長。由於中國、韓國、日本和台灣地區集中了半導體、電子和電池生產基地,亞太地區已成為基於視覺的品質分析市場最大的區域市場。中國正在擴大國內半導體產能,韓國擁有DRAM和OLED產業叢集。日本支持VCSEL和汽車感測器的製造,台灣擁有先進的晶圓代工廠業務。印度是一個需求正在興起的地區,半導體激勵措施和電子製造服務的擴張將推動未來檢測技術的應用。
LIBAD基準測試於2026年8月發布,該測試採用了實際的捲對卷生產數據和三種電池電極檢測成像技術。這項研究反映了隨著電池產能區域擴張,品質要求日益複雜化。越南、泰國和馬來西亞也隨著精密製造能力的加入,電池電極檢測的需求也不斷增加。北美是第二大需求區域,預計半導體製造、製藥、航太與國防以及汽車檢測等領域的需求將顯著增加。在美國,亞利桑那州和德克薩斯州的半導體產業叢集、五大湖地區的汽車產業走廊以及東海岸的製藥和生物技術設施都存在顯著的需求。
美國食品藥物管理局 (FDA) 的品質管理系統法規於 2026 年 2 月 2 日生效,該法規透過引用將 ISO 13485:2016 標準納入 21 CFR 第 820 部分。這確立了美國醫療設備設施中視覺測試系統的文件和驗證要求。在加拿大,安大略省的汽車零件供應商和魁北克省的航太製造商支撐著專業需求;而在墨西哥,電子製造業活動推動了需求成長。在歐洲,德國的汽車、機器人和精密工程產業發揮主導作用。法國、英國和義大利則透過航太零件、製藥和食品加工做出貢獻。南美洲、中東和非洲的需求相對小規模,主要集中在巴西、阿拉伯聯合大公國和南非,這些地區採用雲端和混合模式可以降低基礎設施需求。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 從人工品質檢驗迅速轉向人工智慧驅動的自動化缺陷檢測。
- 電動車電池和半導體製造領域對高精度視覺分析的需求日益成長。
- 邊緣運算平台的普及使得即時線上品質評估成為可能。
- 我們正在朝著預測性品質分析方向發展,以降低廢品率和返工成本。
- 醫療設備和藥品產業整體需要更嚴格的監管和可追溯性標準。
- 擴大混合人工智慧和基於規則的演算法在複雜表面和組裝檢測中的應用。
- 市場限制因素
- 前期實施成本高,且與現有機械設備整合複雜。
- 缺乏高品質的標籤的罕見工業缺陷模型訓練資料集。
- 高速生產線中影響模型精度的光學與環境脆弱性
- 缺乏維護邊緣機器學習工作流程所需的專業技術人員
- 宏觀經濟因素對市場的影響
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 按分析類型
- 缺陷和異常分析
- 尺寸和測量分析
- 模式和分類分析
- 過程品質分析
- 預測品質分析
- 其他分析類型
- 透過技術
- 利用人工智慧/深度學習進行分析
- 傳統基於規則的分析
- 混合人工智慧與基於規則的分析
- 不同的發展
- 邊緣/本地部署
- 基於雲端的
- 混合
- 按最終用戶行業分類
- 電子和半導體
- 電動車和電池製造
- 車
- 藥品和醫療設備
- 食品/飲料
- 航太/國防
- 物流和倉儲
- 其他終端用戶產業
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 智利
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 澳洲
- 其他亞太國家
- 中東
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 卡達
- 其他中東國家
- 非洲
- 南非
- 埃及
- 奈及利亞
- 其他非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Cognex Corporation
- Keyence Corporation
- Zebra Technologies Corporation
- Siemens AG
- Teledyne Technologies Incorporated
- Omron Corporation
- Basler AG
- SICK AG
- Landing AI
- Instrumental Inc.
- Sight Machine Inc.
- Neurala Inc.
- Pleora Technologies Inc.
- Elementary Robotics, Inc.
- Amazon Web Services, Inc.
- Google LLC
- Microsoft Corporation
- Kitov Systems Ltd.(Kitov.ai)
第7章 市場機會與未來展望
According to Mordor Intelligence, the vision-based quality analytics market size is projected to expand from USD 1.55 billion in 2025 and USD 1.76 billion in 2026 to USD 3.53 billion by 2031, registering a CAGR of 14.94% between 2026 to 2031.
Global Vision-Based Quality Analytics Market Trends and Insights
Rapid Transition From Manual Inspection to Automated AI-Powered Defect Recognition
Manual inspection is becoming harder to sustain when production volumes rise and defect tolerance narrows. A consumer goods manufacturer replaced manual spot checks with unsupervised edge-based anomaly detection and targeted a reduction in inspection labor from 40% to 4% of its plant workforce. The vision-based quality analytics market benefits when manufacturers extend inspection to steps that previously lacked full coverage due to time or cost constraints. TSMC uses NVIDIA Metropolis and the NVIDIA TAO Toolkit to improve nanometer-scale defect classification while reducing the need for repeated labeling and retraining as conditions change. A VCSEL inspection study using 22,410 images reported 98.7% accuracy and reduced per-unit inspection time from 17.7 seconds to 1.5 seconds. The same study reported an 89% reduction in inspection time and a 4.5-month hardware payback period.
Increasing Demand for High-Precision Visual Analytics in EV Battery and Semiconductor Fabrication
Battery and semiconductor production both require close control because a single defect can jeopardize an entire lot, module, or finished product. The vision-based quality analytics market, therefore, has high-value applications in these production environments. Researchers presented AOI-SSL at the CVPR 2026 workshop as a self-supervised approach for wire-bonded semiconductor inspection, using domain-specific vision transformer pretraining on smaller inspection datasets. The LIBAD benchmark, released in August 2026, includes 744 electrode samples from real roll-to-roll production lines and covers 11 defect categories. It combines visible-light imaging, high-resolution X-ray, and inline-compatible X-ray radiography. Cell formats, including cylindrical, prismatic, and pouch designs, require inspection systems that can adapt to different configurations and defect patterns.
High Upfront Deployment Costs and Integration Complexity with Legacy Machinery
The vision-based quality analytics market faces a practical barrier in facilities that use older, PLC-driven equipment and have limited data infrastructure. A pilot usually requires manual fallback, evaluation milestones, and connectivity to a manufacturing execution system before an AI inspection system is ready for full production. Smaller manufacturers find the cost of commercial automated optical inspection systems. A VCSEL study described hardware-constrained architectures designed for settings where larger incumbent platforms are not feasible. Older plants may also lack the high-throughput, low-latency connectivity needed to link cameras, edge nodes, and enterprise systems. Neurala reported that its L-DNN technology can train and infer without cloud connectivity or GPU hardware, which addresses facilities with limited deployment capacity.
Other drivers and restraints analyzed in the detailed report include:
- Proliferation of Edge Computing Platforms Enabling Real-Time In-Line Quality Assessment
- Rising Shift Toward Predictive Quality Analytics to Reduce Scrap Rates and Rework Costs
- Scarcity of High-Quality Labeled Training Datasets for Rare Industrial Defect Models
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Defect and Anomaly Analytics held 32.67% share in 2025, making it the largest analytics category in the vision-based quality analytics market. Electronics, automotive, and food-processing lines use this category for surface and structural checks to determine whether a unit passes or fails. Installed automated optical inspection systems generate classification records that can be shared with manufacturing execution systems. Dimensional and Measurement Analytics supports precision metrology in high-mix discrete manufacturing. Pattern and Classification Analytics supports component identification and traceability in automotive and electronics assembly.
Predictive Quality Analytics is forecast to expand at a 15.56% CAGR through 2031. The vision-based quality analytics industry is adopting predictive tools because end-of-line detection does not recover the cost of material or processing already consumed. Process Quality Analytics links inspection results with upstream process variables and supports earlier corrective action. Other Analytics Types include specialized applications that are emerging in individual production settings. The SECOM study showed how a closed-loop model could adapt as process conditions change.
Traditional Rule-Based Analytics commanded a 43.67% share in 2025, reflecting an installed base of systems built around fixed thresholds, edge-detection filters, and geometric rules. These systems remain useful where products and operating conditions are stable. The vision-based quality analytics market still depends on rule-based methods for validated tasks that require consistent logic. Their limits become clearer when lighting, product variants, or process parameters change. A systematic review reported that YOLO-based approaches achieved 98.6% mAP on PCB defect datasets.
AI/Deep Learning-Based Analytics is forecast to grow at a 15.63% CAGR through 2031. The vision-based quality analytics industry is using deep learning, where hand-configured rules struggle with varied or complex features. The same review reported that HSA-RTDETR reached 96.9% mAP at 66.2 FPS for a 6-defect PCB inspection task. Hybrid AI and Rule-Based Analytics preserves validated rules for predictable checks while applying AI to variable conditions. SICK announced updated capabilities for its Nova platform, including tools for 3D data processing and neural-network object detection, for its Vision 2026 showcase.
Complete Report Scope:
- By Analytics Type
- Defect and Anomaly Analytics
- Dimensional and Measurement Analytics
- Pattern and Classification Analytics
- Process Quality Analytics
- Predictive Quality Analytics
- Other Analytics Types
- By Technology
- AI / Deep Learning-Based Analytics
- Traditional Rule-Based Analytics
- Hybrid AI and Rule-Based Analytics
- By Deployment
- Edge / On-Premises
- Cloud-Based
- Hybrid
- By End-User Industry
- Electronics and Semiconductors
- EV and Battery Manufacturing
- Automotive
- Pharmaceutical and Medical Devices
- Food and Beverage
- Aerospace and Defense
- Logistics and Warehousing
- Other End-User Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East
- United Arab Emirates
- Saudi Arabia
- Qatar
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Rest of Africa
- North America
Geography Analysis
Asia-Pacific held 36.12% share in 2025 and is forecast to grow at a 16.21% CAGR through 2031. The vision-based quality analytics market has its largest regional base in Asia-Pacific because China, South Korea, Japan, and Taiwan have dense semiconductor, electronics, and battery production. China is expanding domestic semiconductor capacity, while South Korea has DRAM and OLED clusters. Japan supports VCSEL and automotive sensor manufacturing, and Taiwan has advanced foundry operations. India is an emerging demand location because semiconductor incentives and expanding electronics manufacturing services are supporting future inspection adoption.
The LIBAD benchmark released in August 2026 used real roll-to-roll production data and 3 imaging methods for battery electrode inspection. This work reflects the increasing complexity of quality requirements as regional battery capacity grows. Vietnam, Thailand, and Malaysia also contribute to demand as supply chains add precision production capacity. North America is the second-largest region, with demand across semiconductor manufacturing, pharmaceuticals, aerospace and defense, and automotive inspection. The United States has major demand in Arizona and Texas semiconductor clusters, the Great Lakes automotive corridor, and East Coast pharmaceutical and biotechnology facilities.
The FDA Quality Management System Regulation became effective on February 2, 2026, and incorporated ISO 13485:2016 by reference into 21 CFR Part 820. This creates documentation and validation requirements for vision inspection systems in U.S. medical device facilities. Canada supports specialized demand through Ontario automotive suppliers and Quebec aerospace manufacturers, while Mexico adds electronics manufacturing activity. Europe is led by Germany's automotive, robotics, and precision engineering sectors. France, the United Kingdom, and Italy contribute through aerospace components, pharmaceuticals, and food processing. South America, the Middle East, and Africa remain smaller demand areas centered on Brazil, the UAE, and South Africa, where cloud and hybrid models can lower infrastructure requirements.
- Cognex Corporation
- Keyence Corporation
- Zebra Technologies Corporation
- Siemens AG
- Teledyne Technologies Incorporated
- Omron Corporation
- Basler AG
- SICK AG
- Landing AI
- Instrumental Inc.
- Sight Machine Inc.
- Neurala Inc.
- Overview, Inc.
- Pleora Technologies Inc.
- Elementary Robotics, Inc.
- Amazon Web Services, Inc.
- Google LLC
- Microsoft Corporation
- Kitov Systems Ltd. (Kitov.ai)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Transition from Manual Quality Inspection to Automated AI-Powered Defect Recognition
- 4.2.2 Increasing Demand for High-Precision Visual Analytics in EV Battery and Semiconductor Fabrication
- 4.2.3 Proliferation of Edge Computing Platforms Enabling Real-Time In-Line Quality Assessment
- 4.2.4 Rising Shift Toward Predictive Quality Analytics to Reduce Scrap Rates and Rework Costs
- 4.2.5 Tightening Regulatory and Traceability Standards Across Medical Devices and Pharmaceuticals
- 4.2.6 Growing Implementation of Hybrid AI and Rule-Based Algorithms for Complex Surface and Assembly Inspection
- 4.3 Market Restraints
- 4.3.1 High Upfront Deployment Costs and Integration Complexity with Legacy Machinery
- 4.3.2 Scarcity of High-Quality Labeled Training Datasets for Rare Industrial Defect Models
- 4.3.3 Optical and Environmental Vulnerabilities Affecting Model Accuracy on High-Speed Production Lines
- 4.3.4 Shortage of Specialized Technical Talent to Maintain Edge Machine Learning Workflows
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Analytics Type
- 5.1.1 Defect and Anomaly Analytics
- 5.1.2 Dimensional and Measurement Analytics
- 5.1.3 Pattern and Classification Analytics
- 5.1.4 Process Quality Analytics
- 5.1.5 Predictive Quality Analytics
- 5.1.6 Other Analytics Types
- 5.2 By Technology
- 5.2.1 AI / Deep Learning-Based Analytics
- 5.2.2 Traditional Rule-Based Analytics
- 5.2.3 Hybrid AI and Rule-Based Analytics
- 5.3 By Deployment
- 5.3.1 Edge / On-Premises
- 5.3.2 Cloud-Based
- 5.3.3 Hybrid
- 5.4 By End-User Industry
- 5.4.1 Electronics and Semiconductors
- 5.4.2 EV and Battery Manufacturing
- 5.4.3 Automotive
- 5.4.4 Pharmaceutical and Medical Devices
- 5.4.5 Food and Beverage
- 5.4.6 Aerospace and Defense
- 5.4.7 Logistics and Warehousing
- 5.4.8 Other End-User Industries
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Chile
- 5.5.2.4 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 Qatar
- 5.5.5.4 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Egypt
- 5.5.6.3 Nigeria
- 5.5.6.4 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Cognex Corporation
- 6.4.2 Keyence Corporation
- 6.4.3 Zebra Technologies Corporation
- 6.4.4 Siemens AG
- 6.4.5 Teledyne Technologies Incorporated
- 6.4.6 Omron Corporation
- 6.4.7 Basler AG
- 6.4.8 SICK AG
- 6.4.9 Landing AI
- 6.4.10 Instrumental Inc.
- 6.4.11 Sight Machine Inc.
- 6.4.12 Neurala Inc.
- 6.4.13 Overview, Inc.
- 6.4.14 Pleora Technologies Inc.
- 6.4.15 Elementary Robotics, Inc.
- 6.4.16 Amazon Web Services, Inc.
- 6.4.17 Google LLC
- 6.4.18 Microsoft Corporation
- 6.4.19 Kitov Systems Ltd. (Kitov.ai)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 人工智慧害蟲檢測市場:全球市場預測(2026-2032年)
 2026-2030年全球人工智慧車輛偵測系統市場
 2026年全球車輛偵測系統市場報告人工智慧唇語辨識工具市場:全球市場預測,2026-2032年具身智慧模擬平台市場:全球市場預測,2026-2032年
 人工智慧電腦視覺市場機會、成長要素、產業趨勢分析及2026-2035年預測
 電腦視覺領域的人工智慧:市場規模、佔有率、成長、全球產業分析、區域趨勢及2026-2034年預測電腦視覺市場中的人工智慧:按組件、技術、功能、應用、部署模式和最終用戶產業分類——2026-2032年全球市場預測
 2026-2030年全球電腦視覺人工智慧市場
 人工智慧市場預測(電腦視覺方向)至2034年:全球組件、機器學習模型、功能、技術、應用、最終用戶和區域分析