


 |
市場調查報告書
商品編碼
2125623
綠色氫能:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Green Hydrogen - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,綠氫市場規模將從 2025 年的 25 萬噸和 2026 年的 47 萬噸成長到 2031 年的 1,078 萬噸,2026 年至 2031 年的年複合成長率(CAGR)為 87.12%。
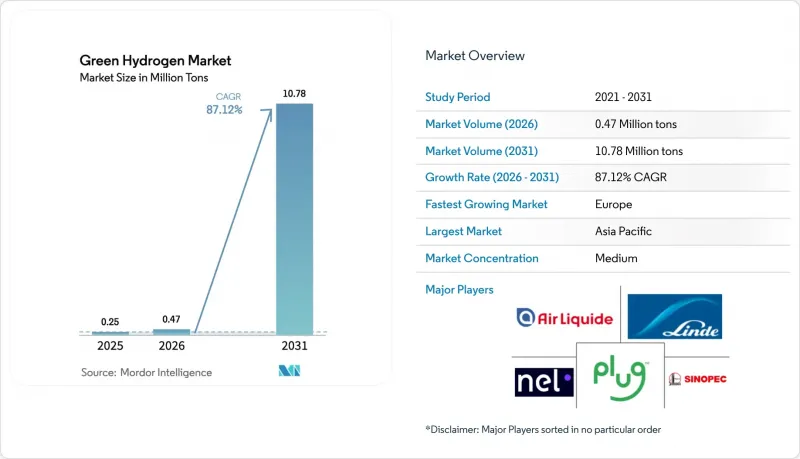
本報告按技術(鹼電解、PEM電解、固體氧化物電解、AEM電解)、終端用戶產業(煉油、化學、鋼鐵、交通運輸及其他)和地區(亞太、北美、歐洲、南美、中東和非洲)進行細分。市場預測以噸為單位。
全球綠氫能市場趨勢與洞察
在太陽輻射強度高的地區,可再生電成本(LCOE)下降。
到2025年,沙烏地阿拉伯、智利和澳洲的太陽能和陸上風發電工程已實現低發電成本。如果天然氣價格保持有利,這個價格水準將使電解氫能夠與蒸氣甲烷重整製氫競爭。 NEOM綜合設施擁有具競爭力的混合平準化度電成本(LCOE),且無需補貼即可運作。同時,智利麥哲倫風電叢集的目標是到2030年出口綠色氨。透過將電解設備與資源開採點集中建設,專案可以顯著降低輸電成本。皮爾巴拉地區的Fort Esk系統就是一個典型的例子,它展示了鐵礦石生產商如何將氫能融入其生產運作。這些努力加在一起,最終導致綠色溢價隨著時間的推移而降低。
歐盟工業脫碳義務(鋼鐵、化肥)
根據2026年至2030年的排放交易體系(ETS),碳價格將設定下限,這意味著除非採用碳捕獲或氫氣直接還原鐵(DRI)技術,否則高爐煉鋼將無利可圖。安賽樂米塔爾在漢堡的試點計畫印證了這一點,該計畫成功轉型為氫氣生產,顯著降低了範圍1的碳排放。德國已撥款協助化肥生產者降低綠色溢價,並推廣綠色氨的使用。碳邊境調節機制(CBAM)將這些挑戰擴展到歐盟以外,迫使土耳其和烏克蘭的鋼鐵廠要麼考慮採用電解工藝,要麼做好產品價值被徵收關稅的準備。
PEM電池堆的銥金和白金供應瓶頸
2025年全球銥產量相當可觀,但如果負載率不變,2028年PEM的需求可能會顯著成長。 2025年12月銥現貨價格的急遽上漲加劇了PEM成本的上升。回收銥的年供應量有限,而混合氧化物替代品的耐久性較差。供應商的目標是在2027年前降低負載率,但南非的供應集中以及勞資糾紛加劇了價格波動。
細分市場分析
到2025年,鹼性電解系統將佔銷售量的55.13%,因為其資本成本和使用壽命與煉油廠和化工廠接近最高效率運作的需求完美契合。同時,在電力快速成長的推動下,PEM電解系統預計將以92.35%的複合年成長率成長,使其成為利用間歇性電力的理想選擇。隨著綜合可再生能源整合策略的成熟,綠色氫能領域PEM專案的市場規模預計將顯著成長。另一方面,具有卓越發電效率的高溫固體氧化物電解池(SOEC)先導計畫面臨電堆壽命不到2萬小時的挑戰,阻礙了其即時部署。陰離子交換膜(AEM)裝置雖然成功避免了使用鉑族金屬,但在商業化之前,其膜耐久性不足2萬小時也面臨挑戰。
近期訂單趨勢凸顯了產業的轉型。 2025年,亞太地區的煉油商優先考慮降低資本支出,並大量訂購鹼性電解設備。相較之下,歐洲更傾向於PEM電解系統,並因其潛在的系統服務收入而認為更高的價格是合理的,最終獲得了大部分訂單。固體氧化物電解系統雖然在2025年的出貨量中所佔佔有率較小,但預計將實現強勁成長,這主要得益於鋼鐵廠將電解製程與廢熱流相結合。這一趨勢表明,技術選擇正發生重大轉變,即越來越受工廠具體經濟因素的驅動,而非對特定技術的統一偏好。
區域分析
預計到2025年,亞太地區將佔據48.23%的市場。這主要得益於中國和印度電解槽能的快速擴張,儘管依賴煤炭的電網給降低碳排放強度帶來了挑戰。中國的三峽集團利用成本效益高的離峰時段風電營運大規模電解槽。日本國內可再生能源資源有限,已簽署長期合約,成為最大的進口國。韓國在大量補貼的支持下,正在對其蔚山和仁川的氫能叢集維修,目標是在2029年之前全面轉型為綠氫能供應。同時,印度的「國家任務」正在獲得各方承諾,但需要投資加強其輸電網,以解決拉賈斯坦邦無功功率和諧波的限制。
歐洲的氫氣生產成長率最高,預計年複合成長率將達到94.19%。 CBAM政策迫使上游供應商轉向綠色氫氣,否則將面臨關稅。同時,德國正大力投資魯爾區離岸風電資源與工廠連接的管線計畫。伊維爾德羅拉公司在卡斯蒂利亞-拉曼恰的雄心勃勃的項目凸顯了該地區的潛力,該項目表明,透過價格具有競爭力的太陽能發電可以低成本生產氫氣。英國也在穩步推進,包括透過長期價格保證來刺激新設施的開發。法國道達爾能源公司也不甘示弱,正在擴建其位於拉梅德的工廠,旨在大幅減少可再生柴油的排放。
在北美,受美國45V稅額扣抵的推動,市場呈現強勁成長動能。空氣產品公司正採取重大舉措,包括在路易斯安那州建設一座大規模綜合設施,該設施整合了電解和可再生能源技術,旨在實現可觀的年產量並用於出口。在加拿大魁北克省,一座水力發電廠已運作,有效降低了生產成本。墨西哥也加入了這場競爭,其圖拉煉油廠的維修旨在用“灰氫”替代“灰氫”,預計這將顯著減少每年的二氧化碳排放。
到2030年,以NEOM和Masdar主導的中東和非洲地區預計將具備大量出口綠色氨的能力。同時,在南美洲的智利,大量投資正湧入風電走廊沿線的出口導向計畫。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 市場分析與定義的前提條件
- 分析範圍
第2章 分析方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 在太陽輻射強度高的地區,可再生能源成本(LCOE)有所下降
- 歐盟工業脫碳義務(鋼鐵、化肥)
- 船舶燃料法規正在推動對綠色氨燃料的需求。
- 電解槽的規模經濟
- 由於過剩電力輸出被削減,風能和太陽能發電的購電協議(PPA)在下半年可能會出現負價格。
- 市場限制因素
- PEM電池組中銥和鉑金的供應瓶頸
- 對輸電網接收超過 100 MW電解叢集的能力有限制。
- 運輸低溫液氫的高成本,運輸路線超過 7000 公里。
- 價值鏈分析
- 技術展望
- 波特五力分析
第5章:預測市場規模與成長率
- 透過技術
- 鹼性電解
- 質子交換膜(PEM)電解
- 固體氧化物電解法
- 陰離子交換膜(AEM)電解
- 按最終用戶行業分類
- 純化
- 化學
- 鋼
- 運輸
- 其他終端用戶產業(發電、玻璃、半導體)
- 按地區
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 其他亞太國家
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 其他歐洲國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 南非
- 其他中東和非洲國家
- 亞太地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率/排名分析
- 公司簡介
- Air Liquide
- Air Products and Chemicals Inc.
- BP PLC
- CHARBONE Hydrogen Corporation
- China Petroleum & Chemical Corporation(Sinopec)
- China Three Gorges Corporation
- Cummins Inc.
- Engie SA
- Fortescue Future Industries
- Green Hydrogen International Corp.
- Iberdrola SA
- Intercontinental Energy
- ITM Power PLC
- Lhyfe SA
- Linde PLC
- McPhy Energy SA
- Nel
- Ningxia Baofeng Energy Group Co. Ltd.
- Orsted A/S
- Plug Power Inc.
- Reliance Industries Limited
- Shell PLC
- Siemens Energy AG
- thyssenkrupp nucera
- Tidewater Renewables Ltd.
- Uniper SE
- Yara
第7章 市場機會與未來展望
According to Mordor Intelligence, the green hydrogen market size is projected to expand from 0.25 million tons in 2025 and 0.47 million tons in 2026 to 10.78 million tons by 2031, registering a CAGR of 87.12% between 2026 to 2031.
This report is Segmented by Technology (Alkaline, PEM, Solid Oxide, and AEM Electrolysis), End-User Industry (Refining, Chemicals, Iron and Steel, Transportation, and Other), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). Market Forecasts are Provided in Terms of Volume (Tons).
Global Green Hydrogen Market Trends and Insights
Declining LCOE of Renewables in High-Irradiance Regions
In 2025, solar and onshore wind projects in Saudi Arabia, Chile, and Australia achieved low generation costs. This pricing enables electrolytic hydrogen to compete with steam methane reforming, provided natural gas prices remain favorable. The NEOM complex enjoys a competitive blended LCOE, allowing it to operate without subsidies. Meanwhile, Chile's Magallanes wind cluster aims to export green ammonia by 2030. By co-locating electrolyzers with resource sites, projects can significantly reduce transmission costs. A case in point is Fortescue's system in Pilbara, which showcases how iron-ore producers are integrating hydrogen into their operations . Collectively, these initiatives have narrowed the green premium over time.
EU Industrial Decarbonization Mandates (Steel, Fertilizer)
Under the 2026-2030 ETS, a carbon price floor renders blast-furnace steel unviable unless carbon capture or hydrogen-based DRI is employed. This is underscored by ArcelorMittal's trials in Hamburg, where a shift to hydrogen achieved a significant reduction in Scope 1 emissions. Germany allocated funds to help fertilizer producers mitigate the green premium, facilitating the offtake of green ammonia. The Carbon Border Adjustment Mechanism amplifies these challenges beyond the EU, leading Turkish and Ukrainian mills to either explore electrolytic methods or brace for tariffs on their product's value.
Iridium and Platinum Supply Bottlenecks for PEM Stacks
Global iridium output was significant in 2025, yet PEM demand may increase substantially in 2028 if loading rates stay constant. Spot iridium prices rose sharply in December 2025, adding to PEM costs. Recycling provides only a limited amount annually, and mixed-oxide substitutes lag in durability. Suppliers aim to cut loadings by 2027, but supply concentration in South Africa and labor strikes heighten price volatility.
Other drivers and restraints analyzed in the detailed report include:
- Maritime Fuel Rules Spurring Green-Ammonia Bunkering Demand
- Electrolyzer-Gigafactory Economies of Scale
- Limited Grid-Hosting Capacity for Large Electrolyzers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Alkaline systems controlled 55.13% of 2025 volume, thanks to capital costs and lifetimes aligning perfectly with the demands of refiners and chemical plants operating at near-maximum efficiency. Meanwhile, PEM systems are set to climb at a 92.35% CAGR, bolstered by their rapid ramp rates, making them ideal for harnessing intermittent power. As strategies for renewable integration mature, the market size for PEM projects in the green hydrogen sector is set for a pronounced uptick. On the other hand, high-temperature SOEC pilots, boasting impressive electrical efficiency, face a hurdle: their stack life, falling short of 20,000 hours, curtails immediate adoption. AEM units, while successfully sidestepping the use of platinum group metals, grapple with a challenge of membrane durability, also under the 20,000-hour mark, before they can hit the commercial stage.
Recent orders highlight this industry shift. In 2025, refiners in the Asia-Pacific region secured a significant amount of alkaline equipment, prioritizing lower capital expenditures. Conversely, Europe, leaning towards PEM, captured a dominant share of those orders, justifying the premium with potential grid-service revenue. Solid oxide systems, though holding a smaller share of the 2025 volume, are on track for robust growth, driven by iron and steel plants merging electrolysis with their waste heat streams. This trend underscores a pivotal shift: the choice of technology is increasingly dictated by plant-specific economics rather than a blanket preference for one technology over another.
Complete Report Scope:
- By Technology
- Alkaline Electrolysis
- Proton Exchange Membrane (PEM) Electrolysis
- Solid Oxide Electrolysis
- Anion Exchange Membrane (AEM) Electrolysis
- By End-user Industry
- Refining
- Chemicals
- Iron and Steel
- Transportation
- Other End-user Industries (Power Generation, Glass, Semiconductors)
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific's 48.23% share in 2025, driven by the rapid expansion of electrolyzer capacity in China and India, even as coal-dominated grids pose challenges to carbon intensity improvements. China Three Gorges operates a large electrolyzer, harnessing cost-effective off-peak wind power. With limited domestic renewable resources, Japan emerges as the top prospective importer, securing long-term agreements. South Korea, bolstered by substantial subsidies, is retrofitting the Ulsan and Incheon clusters, targeting a complete transition to green supply by 2029. Meanwhile, India's National Mission has rallied commitments, but to address reactive power and harmonic constraints in Rajasthan, an investment is needed for grid enhancements.
Europe records the highest growth rate at a projected 94.19% CAGR. The CBAM policy compels upstream suppliers to pivot to green hydrogen or incur tariffs. Concurrently, Germany is channeling significant funding into a pipeline initiative, connecting offshore wind resources to plants in the Ruhr Valley. Highlighting the region's potential, Iberdrola's ambitious project in Castilla-La Mancha demonstrates that competitively priced solar energy can yield hydrogen at a low cost. The UK is making strides too, with a long-term guarantee of a strike price, facilitating the development of new capacity. Not to be outdone, France's TotalEnergies has augmented its La Mede facility, aiming for a substantial reduction in renewable diesel emissions.
North America, buoyed by the U.S. 45V tax credit, is witnessing robust growth. Air Products is making a significant move with a large complex in Louisiana, integrating electrolysis with renewable energy, targeting substantial annual output for export. In Quebec, Canada, a plant is capitalizing on hydro energy, translating to a low production cost. Mexico is also in the fray, with Tula refinery's retrofit set to substitute gray hydrogen, leading to significant annual CO2 savings.
By 2030, the Middle East and Africa, spearheaded by NEOM and Masdar, are poised to export a large volume of green ammonia. Meanwhile, South America's Chilean wind corridor is attracting substantial investment for projects aimed at exports.
- Air Liquide
- Air Products and Chemicals Inc.
- BP PLC
- CHARBONE Hydrogen Corporation
- China Petroleum & Chemical Corporation (Sinopec)
- China Three Gorges Corporation
- Cummins Inc.
- Engie SA
- Fortescue Future Industries
- Green Hydrogen International Corp.
- Iberdrola SA
- Intercontinental Energy
- ITM Power PLC
- Lhyfe SA
- Linde PLC
- McPhy Energy S.A.
- Nel
- Ningxia Baofeng Energy Group Co. Ltd.
- Orsted A/S
- Plug Power Inc.
- Reliance Industries Limited
- Shell PLC
- Siemens Energy AG
- thyssenkrupp nucera
- Tidewater Renewables Ltd.
- Uniper SE
- Yara
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Declining LCOE of renewables in high-irradiance regions
- 4.2.2 EU industrial decarbonization mandates (steel, fertilizer)
- 4.2.3 Maritime fuel rules spurring green-ammonia bunkering demand
- 4.2.4 Electrolyzer-gigafactory economies of scale
- 4.2.5 Surplus curtailed wind/solar PPAs enabling negative-price H2
- 4.3 Market Restraints
- 4.3.1 Iridium and platinum supply bottlenecks for PEM stacks
- 4.3.2 Limited grid-hosting capacity for greater than 100 MW electrolysis clusters
- 4.3.3 High cost of cryogenic LH2 shipping over 7,000 km routes
- 4.4 Value Chain Analysis
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitute Products
- 4.6.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Technology
- 5.1.1 Alkaline Electrolysis
- 5.1.2 Proton Exchange Membrane (PEM) Electrolysis
- 5.1.3 Solid Oxide Electrolysis
- 5.1.4 Anion Exchange Membrane (AEM) Electrolysis
- 5.2 By End-user Industry
- 5.2.1 Refining
- 5.2.2 Chemicals
- 5.2.3 Iron and Steel
- 5.2.4 Transportation
- 5.2.5 Other End-user Industries (Power Generation, Glass, Semiconductors)
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle-East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle-East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share/Ranking Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 Air Liquide
- 6.4.2 Air Products and Chemicals Inc.
- 6.4.3 BP PLC
- 6.4.4 CHARBONE Hydrogen Corporation
- 6.4.5 China Petroleum & Chemical Corporation (Sinopec)
- 6.4.6 China Three Gorges Corporation
- 6.4.7 Cummins Inc.
- 6.4.8 Engie SA
- 6.4.9 Fortescue Future Industries
- 6.4.10 Green Hydrogen International Corp.
- 6.4.11 Iberdrola SA
- 6.4.12 Intercontinental Energy
- 6.4.13 ITM Power PLC
- 6.4.14 Lhyfe SA
- 6.4.15 Linde PLC
- 6.4.16 McPhy Energy S.A.
- 6.4.17 Nel
- 6.4.18 Ningxia Baofeng Energy Group Co. Ltd.
- 6.4.19 Orsted A/S
- 6.4.20 Plug Power Inc.
- 6.4.21 Reliance Industries Limited
- 6.4.22 Shell PLC
- 6.4.23 Siemens Energy AG
- 6.4.24 thyssenkrupp nucera
- 6.4.25 Tidewater Renewables Ltd.
- 6.4.26 Uniper SE
- 6.4.27 Yara
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

 全球綠色氫能市場(2027-2037 年)
 綠氫能市場預測至2034年-按再生能源來源、技術、分銷模式、應用、終端用戶和地區分類的全球分析
 綠色氫能市場-2026-2032年全球市場預測
 綠氫能:全球市場綠色氫能經濟市場預測—全球生產技術、可再生能源、儲存方法、分銷模式、應用、終端用戶和地區分析—2034年
 2026年全球廢棄物製氫市場報告2026年全球綠色氫能市場報告
 綠色氫能市場規模、佔有率和成長分析:按技術、再生能源來源、通路、最終用途和地區分類-2026-2033年產業預測
 日本綠色氫能市場規模、佔有率、趨勢及預測(按技術、應用、通路和地區分類,2026-2034年)
 綠色氫氣市場按類型、通路、最終用戶和地區分類