


 |
市場調查報告書
商品編碼
2125562
歐洲紙張:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Europe Paper - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,歐洲紙張市場規模預計在 2025 年達到 7,114 萬噸,2026 年達到 7,372 萬噸,到 2031 年達到 9,008 萬噸,2026 年至 2031 年的複合年成長率為 4.09%。
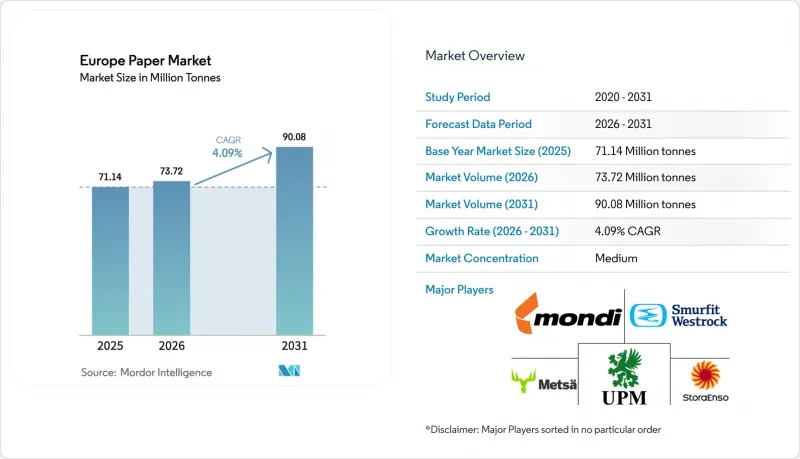
本報告依產品類型(印刷用紙、紙箱材料、衛生及家庭用紙製品等)、原料來源(原生紙漿、再生紙漿、農業廢棄物紙漿等)、紙張重量(小於90克/平方公尺等)、終端用戶產業(包裝及工業、印刷出版、衛生用品等)及國家/地區進行細分。市場預測以噸為單位。
歐洲紙張市場趨勢與洞察
擴大永續包裝材料的使用
日常消費品和電商產業的品牌所有者正在向完全可回收的紡織包裝轉型,以符合歐盟關於所有包裝材料到2030年必須可回收的要求。德國的《包裝法》(VerpackG)降低了紙質包裝的生產者延伸責任(EPR)費用,使得採購可回收的認證紙板和特殊等級紙板更具經濟效益。 Mondi公司的MailerBAG包裝袋於2024年被一家大型電商零售商採用,其紙基材採用水性阻隔技術,使其抗撕裂性能與聚乙烯郵寄袋相當。因此,製造商正在擴大其脫墨、除雜和阻隔塗層設施,並接受更高的資本投入以確保長期競爭力。與零售商建立循環供應鏈的造紙企業,不僅能夠獲得穩定的再生纖維來源,還能在具有永續發展意識的消費者面前獲得優先展示。
電子商務和餐飲服務業的需求不斷成長。
2024年,歐洲線上零售額佔總銷售額的23%,由於單件小包裹比托盤式門市配送消耗更多紙板,瓦楞紙箱的需求量也隨之成長。同時,《一次性塑膠指令》逐步淘汰了聚苯乙烯外帶餐盒,迫使速食店改用模塑纖維翻蓋式容器和紙吸管。 2024年,Hootamäki在西班牙將其模塑纖維一次性產品的產能提高了1.5萬噸,從而為在歐洲標準化紡織品的跨國連鎖企業建立了供應體系。小包裹物流和餐飲服務業的雙重需求,使得傳統印刷生產線的生產時間得以轉移,從而擴大了歐洲紙張市場對箱板紙和功能性特種紙的需求。此外,電子商務對可變資料印刷的偏好也進一步提升了數位預印卷材的利潤率。
木漿和再生紙價格波動劇烈
2024年,受加拿大山火和巴西物流問題導致的供應中斷影響,北美漂白軟木牛皮紙的交易價格為每噸1000至1100美元。德國再生紙(OCC)的價格則在每噸80至120歐元(86.4至129.6美元)之間波動,具體價格取決於亞洲出口需求的波動。成本的劇烈波動正在擠壓那些不生產紙漿的造紙企業的利潤空間,迫使它們要么犧牲短期利潤,要么冒著客戶流失的風險將高昂的價格轉嫁給消費者。垂直整合到資本密集型紙漿資產中可以保護大型成熟企業,但也會增加其資產負債表的槓桿率。而那些無法自給自足紙漿生產的小規模獨立企業,每次投入成本週期性飆升時,都會面臨生存危機。
細分市場分析
在歐洲造紙市場,瓦楞紙板原紙在2025年的產量佔比將達到33.78%,反映了瓦楞紙箱在電子商務和工業運輸中的核心地位。受食品接觸阻隔襯紙、矽塗層離型紙和過濾材料等需求的推動,特種紙預計將以5.16%的複合年成長率引領行業發展,直至2031年。印刷用紙的產量在2024年下降了8%,進一步下滑,凸顯了其長期的下降趨勢。由於箱板紙數位預印和不含PFAS的塗層等創新技術的出現,特種紙仍然對品牌商具有吸引力。
Sappi公司斥資4,320萬美元建造阻隔塗層生產線,這清楚地表明了造紙企業積極開拓高利潤細分市場的決心。歐盟關於非纖維素組件可回收性的法規有利於單一材料瓦楞紙箱的生產,從而提振了對紙箱材料的需求。倉儲自動化也使箱板受益,推動了單元化瓦楞紙解決方案的發展。同時,印刷用紙生產線面臨關閉或維修,衛生紙的需求依然強勁,這得益於市場對高檔紙巾的需求。
到2025年,再生纖維預計將佔總產量的60.32%,這得益於歐洲成熟的71.4%的回收率。農業殘餘纖維雖然目前規模較小,但預計將以6.03%的複合年成長率成長,因為造紙企業正在嘗試將麥秸和麻混紡以降低紙漿價格風險。原生纖維仍繼續用於衛生紙和高強度紙,但在循環經濟的指南下,其市場佔有率正在下降。
根據德國包裝法(VerpackG)的收費結構,使用再生纖維的包裝材料具有明顯的成本優勢。同時,斯道拉恩佐位於奧盧的工廠正在將其年產量中的50萬噸轉化為再生箱板紙。西班牙的先導計畫利用農業廢棄物,將20%的稻草與OCC(再生紙板)混合,且不影響紙箱的抗壓強度,這顯示未來具有擴大規模的潛力。儘管由於NBSK價格持續波動,人們仍然關注原料的多樣性,但由於衛生紙等級對白度和強度的要求,原生牛皮紙仍然是歐洲紙張市場產量分配的關鍵組成部分。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 擴大永續包裝材料的使用
- 電子商務的擴張和外出用餐需求的增加
- 歐盟關於紡織品包裝的循環經濟要求
- 新冠疫情後衛生紙消耗量增加
- 3D模塑纖維包裝的商業化
- 按需噴墨瓦楞紙板印刷的實施現狀
- 市場限制因素
- 木漿和再生紙價格波動
- 數位媒體取代繪圖紙
- 能源和碳權價格上漲
- 加強對造紙廠用水限制
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 宏觀經濟因素對市場的影響
- 波特五力分析
第5章 市場規模與成長預測
- 依產品類型
- 繪圖紙
- 報紙紙張
- 其他繪圖紙
- 案例材料
- 衛生/家庭用紙製品
- 包裝紙
- 紙板
- 特種紙
- 繪圖紙
- 按原料來源
- 原生紙漿
- 再生紙漿
- 農業殘餘物漿
- 按紙張重量
- 小於90克/平方公尺(輕量級)
- 90-200 克/平方公尺(中等劑量)
- 超過 200 克/平方米(重量)
- 按最終用途行業分類
- 包裝/工業用途
- 用於印刷/出版
- 衛生用品
- 餐飲服務業的一次性用品
- 其他終端用戶產業
- 國家
- 德國
- 法國
- 瑞典
- 義大利
- 西班牙
- 其他歐洲國家
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Stora Enso Group
- UPM-Kymmene Corporation
- Smurfit Westrock
- Mondi plc
- Metsa Group
- Holmen AB
- Svenska Cellulosa Aktiebolaget SCA
- Mayr-Melnhof Karton AG
- PRINZHORN HOLDING GmbH
- Norske Skog ASA
- Burgo Group SpA
- Lecta Group
- Reno de Medici SpA
- Sappi Limited
- Grigeo AB
- Iberpapel Gestion SA
- Heinzel Group
- Fedrigoni SpA
- Arctic Paper SA
- International Paper Company
第7章 市場機會與未來展望
According to Mordor Intelligence, the Europe paper market size is projected to be 71.14 million tonnes in 2025, 73.72 million tonnes in 2026, and reach 90.08 million tonnes by 2031, growing at a CAGR of 4.09% from 2026 to 2031.
This report is Segmented by Product Type (Graphic Papers, Case Materials, Sanitary and Household, and More), Raw-Material Source (Virgin Fiber, Recycled Fiber, and Agro-Residue Fiber), Basis Weight (Below 90 Gsm, and More), End-Use Industry (Packaging and Industrial, Printing and Publishing, Hygiene and Sanitary, and More), and Country. The Market Forecasts are Provided in Terms of Volume (Tonnes).
Europe Paper Market Trends and Insights
Growth in Use of Sustainable Packaging
Brand owners in fast-moving consumer goods and e-commerce are migrating to fully recyclable fiber packaging to comply with the EU requirement that all packaging be recyclable by 2030. Germany's VerpackG assigns lower extended producer responsibility fees to paper solutions, tilting procurement economics toward containerboard and specialty grades certified for recyclability. Mondi's MailerBAG, adopted by major e-retailers in 2024, showcases paper substrates engineered with water-based barrier chemistry that rivals polyethylene mailers in tear resistance. Producers are therefore scaling de-inking, contaminant removal, and barrier-coating assets, accepting higher capital intensity to secure long-run competitiveness. Mills that close the loop with retailers gain a stable recovered-fiber supply and preferential shelf placement with sustainability-minded consumers.
Expansion of E-commerce and Food-service Demand
Online retail accounted for 23% of total European sales in 2024, boosting corrugated-box demand because single-item parcels consume more containerboard per dollar of merchandise than palletized store deliveries. Simultaneously, the Single-Use Plastics Directive eliminated polystyrene take-out ware, steering quick-service restaurants toward molded-fiber clamshells and paper straws. Huhtamaki's 2024 Spanish capacity addition of 15,000 tonnes for molded-fiber disposables positions it to serve multinational chains as they standardize fiber formats across Europe. The combined pull from parcel logistics and food service reallocates machine time away from legacy graphic lines, widening the Europe paper market demand pool for containerboard and functional specialty papers. E-commerce's tendency to favor variable-data printing further underpins the higher margins of digital pre-print rolls.
Volatile Wood-Pulp and Recovered Paper Prices
Northern bleached softwood kraft traded between USD 1,000 and USD 1,100 per tonne in 2024 as Canadian wildfires and Brazilian logistics hiccups disrupted supply. Recovered OCC in Germany swung from EUR 80 to EUR 120 per tonne (USD 86.4-129.6) as export demand from Asia ebbed and flowed. Cost whiplash compresses spreads for mills lacking captive pulp, forcing short-term margin sacrifice or abrupt price pass-throughs that risk customer churn. Capital-heavy vertical integration into pulp assets insulates large incumbents but raises balance-sheet leverage. Smaller independents without pulp self-sufficiency face existential risk whenever the input-cost cycle spikes.
Other drivers and restraints analyzed in the detailed report include:
- EU Circular-Economy Mandates on Fiber Packaging
- Rising Hygiene-Paper Consumption Post-COVID
- Digital Media Substitution of Graphic Papers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Case materials held 33.78% of 2025 volume within the Europe paper market, reflecting corrugated boxes' central role in e-commerce and industrial shipping. Specialty papers are forecast to pace the field at a 5.16% CAGR to 2031, catalyzed by food-contact barrier liners, silicone-coated release carriers, and filtration media. Graphic papers slumped further in 2024, with an 8% production contraction, underscoring secular decline. Innovations such as digital pre-print on containerboard, plus PFAS-free coatings, keep specialty grades attractive for brand owners.
Sappi's USD 43.2 million barrier-coating line in Germany exemplifies mills' offensive push into higher-margin niches. EU recyclability caps on non-cellulosic constituents reward monomaterial cartons, fortifying demand for case materials. Containerboard also benefits from warehousing automation that favors unitized corrugated solutions. Conversely, graphic-paper lines face closure or retrofits, while sanitary grades hold steady on premium tissue demand.
Recycled fiber contributed 60.32% of tonnage in 2025, leveraging Europe's mature 71.4% recycling rate. Agro-residue fiber, though a small base, is projected to expand 6.03% CAGR as mills trial wheat-straw and hemp blends to buffer pulp-price risk. Virgin fiber use persists in hygiene and high-strength grades but loses share under circular-economy directives.
Germany's VerpackG fee matrix grants recycled-fiber packaging a clear cost edge, while Stora Enso's Oulu conversion pivots half-a-million tonnes into recycled containerboard. Agro-residue pilots in Spain blend 20% straw with OCC without compromising box compression, signaling future scalability. Persistent NBSK volatility keeps the spotlight on diversified feedstocks, but hygiene-grade brightness and strength requirements ensure virgin kraft remains a crucial component in the Europe paper market size allocation.
Complete Report Scope:
- By Product Type
- Graphic Papers
- Newsprint
- Other Graphic Papers
- Case Materials
- Sanitary and Household
- Wrappings
- Carton Board
- Specialty Papers
- Graphic Papers
- By Raw-Material Source
- Virgin Fiber
- Recycled Fiber
- Agro-Residue Fiber
- By Basis Weight
- Below 90 gsm (Lightweight)
- 90-200 gsm (Mediumweight)
- Above 200 gsm (Heavyweight)
- By End-use Industry
- Packaging and Industrial
- Printing and Publishing
- Hygiene and Sanitary
- Food-service Disposables
- Other End-use Industries
- By Country
- Germany
- France
- Sweden
- Italy
- Spain
- Rest of Europe
List of Companies Covered in this Report:
- Stora Enso Group
- UPM-Kymmene Corporation
- Smurfit Westrock
- Mondi plc
- Metsa Group
- Holmen AB
- Svenska Cellulosa Aktiebolaget SCA
- Mayr-Melnhof Karton AG
- PRINZHORN HOLDING GmbH
- Norske Skog ASA
- Burgo Group S.p.A
- Lecta Group
- Reno de Medici S.p.A
- Sappi Limited
- Grigeo AB
- Iberpapel Gestion S.A
- Heinzel Group
- Fedrigoni SpA
- Arctic Paper S.A
- International Paper Company
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growth in Use of Sustainable Packaging
- 4.2.2 Expansion of E-commerce and Food-service Demand
- 4.2.3 EU Circular-Economy Mandates on Fiber Packaging
- 4.2.4 Rising Hygiene-Paper Consumption Post-COVID
- 4.2.5 Commercialization of 3-D Molded-Fiber Packaging
- 4.2.6 On-demand Ink-jet Corrugated Printing Adoption
- 4.3 Market Restraints
- 4.3.1 Volatile Wood-Pulp and Recovered Paper Prices
- 4.3.2 Digital Media Substitution of Graphic Papers
- 4.3.3 Energy and Carbon-credit Price Inflation
- 4.3.4 Tighter Water-Use Regulations for Mills
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VOLUME)
- 5.1 By Product Type
- 5.1.1 Graphic Papers
- 5.1.1.1 Newsprint
- 5.1.1.2 Other Graphic Papers
- 5.1.2 Case Materials
- 5.1.3 Sanitary and Household
- 5.1.4 Wrappings
- 5.1.5 Carton Board
- 5.1.6 Specialty Papers
- 5.1.1 Graphic Papers
- 5.2 By Raw-Material Source
- 5.2.1 Virgin Fiber
- 5.2.2 Recycled Fiber
- 5.2.3 Agro-Residue Fiber
- 5.3 By Basis Weight
- 5.3.1 Below 90 gsm (Lightweight)
- 5.3.2 90-200 gsm (Mediumweight)
- 5.3.3 Above 200 gsm (Heavyweight)
- 5.4 By End-use Industry
- 5.4.1 Packaging and Industrial
- 5.4.2 Printing and Publishing
- 5.4.3 Hygiene and Sanitary
- 5.4.4 Food-service Disposables
- 5.4.5 Other End-use Industries
- 5.5 By Country
- 5.5.1 Germany
- 5.5.2 France
- 5.5.3 Sweden
- 5.5.4 Italy
- 5.5.5 Spain
- 5.5.6 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share, Products and Services, and Recent Developments)
- 6.4.1 Stora Enso Group
- 6.4.2 UPM-Kymmene Corporation
- 6.4.3 Smurfit Westrock
- 6.4.4 Mondi plc
- 6.4.5 Metsa Group
- 6.4.6 Holmen AB
- 6.4.7 Svenska Cellulosa Aktiebolaget SCA
- 6.4.8 Mayr-Melnhof Karton AG
- 6.4.9 PRINZHORN HOLDING GmbH
- 6.4.10 Norske Skog ASA
- 6.4.11 Burgo Group S.p.A
- 6.4.12 Lecta Group
- 6.4.13 Reno de Medici S.p.A
- 6.4.14 Sappi Limited
- 6.4.15 Grigeo AB
- 6.4.16 Iberpapel Gestion S.A
- 6.4.17 Heinzel Group
- 6.4.18 Fedrigoni SpA
- 6.4.19 Arctic Paper S.A
- 6.4.20 International Paper Company
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 封紙市場分析及至2035年預測:類型、產品類型、技術、應用、形狀、材料類型、製造流程、最終用戶、功能、設備對位芳香聚醯胺紙市場分析及至2035年預測:類型、產品、技術、組件、應用、材料類型、過程、最終用戶、解決方案
 香蕉紙市場:全球市場預測,2026-2032年
 2026-2030年全球裝飾紙市場
 貼紙紙市場:按材料、產品類型、印刷技術、應用、黏合劑和地區分類。無塗布機械用紙市場:2026-2032年全球市場預測(依產品類型、製程、紡織原料、等級、銷售管道及最終用途分類)貼紙市場:按產品類型、黏合劑類型、印刷技術、應用和終端用戶產業分類-2026-2032年全球市場預測
 塗佈機械紙捲市場規模、佔有率和成長分析:按塗佈、紙張類型、表面處理/光澤度、最終用途和地區分類-2026-2033年產業預測咖啡濾紙市場:依材質、形狀、產品類型、尺寸、相容性、通路和最終用途分類-全球預測,2026-2032年
 2026年全球紙張、塑膠、橡膠、木材和紡織品市場報告