


 |
市場調查報告書
商品編碼
2125513
工業攪拌機:市佔率分析、產業趨勢與統計、成長預測(2026-2031)Industrial Mixers - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,工業攪拌機市場規模將從 2025 年的 28.8 億美元成長到 2026 年的 31 億美元,然後在 2031 年達到 44.8 億美元,2026 年至 2031 年的複合年成長率為 7.64%。
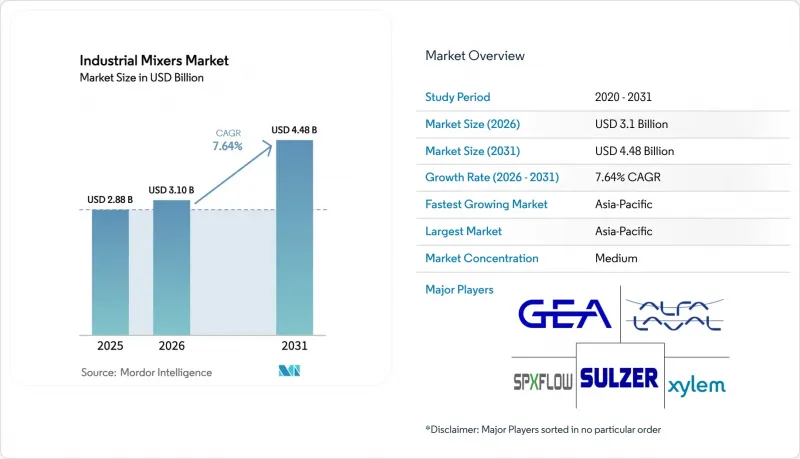
本報告按產品類型(攪拌器、專用攪拌機、潛水式攪拌機等)、終端用戶行業(化學、用水和污水、食品飲料、石油化學、製藥、能源等)、額定功率(小於5kW、5-15kW、其他)和地區(北美、南美、歐洲、亞太、其他)進行細分。市場預測以美元計價。
全球工業攪拌機市場趨勢與洞察
食品和製藥業更嚴格的衛生標準
食品和製藥廠現在必須遵守更新後的 EHEDG 2024 和 FDA 21 CFR 110.35 要求,這些要求規定了電解錶面、無縫焊接和檢驗的CIP(就地清洗)規程。提供經認證的衛生級設備的供應商可以獲得更高的價格,而小規模製造商則面臨更高的合規成本。在製藥業,連續生產線中混合均勻性的記錄是必需的,這加快了在良好生產規範 (GMP) 審核下採購經過驗證的高剪切磁力驅動攪拌機的速度。改造後的舊式攪拌機經常無法通過驗證,導致需要加速進行全面更換。這一趨勢加劇了競爭,並鞏固了衛生級設備的長期服務合約。
推出具有卓越能效的高扭力電機
透過將IE5同步磁阻馬達與變頻器結合使用,可以在提供高黏度漿料所需扭矩的同時,與傳統感應馬達相比,將攪拌機能耗降低高達20%。目前,相關法規已強制要求功率超過0.75千瓦的馬達必須達到IE4或更高的效率,印度和巴西也正在考慮制定類似規定,預計這將加速設備升級。工廠工程師透過將逆變器與邊緣分析技術整合,在低負載下降低轉速,從而延長密封件壽命並降低工業攪拌機市場的電力成本。銷售馬達和數位控制面板套裝的供應商正在獲得更高的利潤率,並擴巨量資料驅動型業務收益。
原物料價格波動(不鏽鋼、合金)
2024年,鎳價在每噸16,500美元至20,000美元之間波動,不鏽鋼價格也隨之波動15%至20%,對攪拌機製造商的利潤率帶來壓力。哈氏合金C-276等特種合金的價格也因航太需求而出現類似上漲,迫使原始設備製造商(OEM)重新談判長期合約或對沖採購風險。雖然主要供應商正透過利用全球採購和庫存共享來緩解成本衝擊,但區域性契約製造製造商(加工車間)卻難以將上漲的成本轉嫁到產品價格上,這阻礙了工業攪拌機行業新增產能的擴張。將供應鏈多元化至印尼和美國或許能夠穩定價格,但這會增加基本成本,最終轉嫁到設備價格上。
細分市場分析
憑藉數十年來在散裝化學品、礦物加工和水處理等領域累積的卓越性能數據,Agitator 預計到 2025 年將佔據工業攪拌機市場 35.85% 的佔有率。其堅固的框架和模組化葉輪庫可經濟高效地客製化適用於任何超過 100 立方米容器的攪拌機。隨著更換週期與日益嚴格的衛生和能源標準相符,Agitator 的工業攪拌機市場規模預計將穩定成長。同時,受生物技術和先進材料領域對乳化需求的推動,高剪切攪拌機預計將以 8.05% 的複合年成長率成長。線上轉子-定子設計可實現微米級顆粒細化,從而實現上游工程設備無法處理的連續濕磨和預分散製程。供應商正在整合即時扭矩和溫度感測器,將數據傳輸到數位孿生模型中,從而提高放大精度,並縮短製藥等受監管行業的驗證時間。
數位化整合正在改變每一條產品線。攪拌機供應商正在將振動感測器整合到齒輪箱殼體和軸中,並將數據傳輸到人工智慧模型,以預測軸承壽命。潛水式攪拌機製造商正在重新設計一個有複合材料護罩的殼體,以減輕重量,同時也能承受海水淡化廠中氯化物所造成的應力開裂。通常不消耗能源的靜態攪拌機和噴射式攪拌機現在標配差壓變送器,使操作人員無需使用穿刺探針即可檢查混合強度。在所有類別中,物聯網框架都支援按次付費的服務模式,使原始設備製造商 (OEM) 能夠透過不僅對設備本身收費,而且對其運作時間收費,來拓展其在工業攪拌機市場的經常性收入收費。
區域分析
亞太地區佔全球銷售額的29.55%,預計2031年將以8.18%的複合年成長率成長。這反映了中國和印度政府主導的化工廠擴建、藥品出口成長以及地方政府對廢水處理的積極投資。在中國,煉油廠尾氣氫氣回收催生了對符合ATEX標準的噴射式攪拌器的需求,而大規模膜生物反應器(MBR)專案則指定使用高效潛水式攪拌器。印度針對活性藥物成分(API)的生產連結獎勵計畫計劃正在推動線上高剪切攪拌器的升級,而東南亞棕櫚油下游產業叢集則正在採用專用攪拌器進行脫臭工藝。雖然本地製造降低了成本,但在需要文件檢驗的高階市場,國際OEM製造商仍然佔據主導地位。
在北美,以波士頓、聖地牙哥和多倫多等生技產業叢集為中心,已實現了大規模部署。連續生技藥品生產線需要配備一次性流路的衛生級高剪切混合器,而噴射式混合器則用於頁岩氣加工和原油海水淡化。美國食品藥物管理局 (FDA) 和環境保護署 (EPA) 的嚴格監管正在推動設備升級,優先考慮節能設計。墨西哥的化學和食品製造業正從美國進口模組化混合撬裝設備,利用近岸供應鏈最大限度地縮短前置作業時間。根據美國《通貨膨脹控制法案》資助的數位化維修正在推動工業混合器市場對傳統設備進行預測性維護模組的投資。
在歐洲,永續性和卓越營運受到歐盟綠色交易的指南。本廠採用IE5馬達、磁力耦合密封件和經環境產品聲明(EPD)認證的低碳不鏽鋼合金。在德國和荷蘭的化工園區,整合整廠數位孿生模型的攪拌機被優先考慮。雖然針對氫電解的ATEX和IECEx法規增加了認證成本,但它們也透過完善的文件管理系統保護了現有供應商。循環經濟計劃正在推動塑膠回收再利用、厭氧消化和有機肥料生產領域對攪拌機的需求成長。這些因素共同造就了歐洲工業攪拌機市場平衡且技術密集的發展前景。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 食品和製藥業更嚴格的衛生標準
- 採用高效率、高扭力電機
- 污水回收處理能力正快速擴張。
- 為培養肉先導計畫改造生物反應器
- 電池材料的現場化學混合
- 適用於偏遠礦區的模組化「按需混合」撬裝設備
- 市場限制因素
- 原物料價格波動(不鏽鋼、合金)
- 與其他線上管理系統相比,資本投入較高。
- 氫能樞紐的ATEX/IECEx認證成本不斷增加。
- 大直徑攪拌器熟練操作人員短缺
- 供應鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 宏觀經濟因素的影響
- 投資分析
第5章 市場規模與成長預測
- 依產品類型
- 攪拌器
- 專用攪拌機
- 潛水式攪拌器
- 高剪切混合器
- 靜態混合器
- 噴射混合器
- 其他產品類型
- 按最終用戶行業分類
- 化學品
- 水和污水處理
- 食品/飲料
- 石油化學產品
- 製藥
- 紙漿和造紙
- 能源(電力和可再生能源)
- 採礦和礦產
- 其他流程工業
- 額定功率
- 小於5千瓦
- 5~15kW
- 15~50kW
- 超過50千瓦
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 東南亞
- 其他亞太國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 其他中東國家
- 非洲
- 南非
- 埃及
- 其他非洲國家
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- SPX FLOW Inc.
- Sulzer Ltd.
- Alfa Laval AB
- Xylem Inc.
- GEA Group AG
- EKATO HOLDING GmbH
- Philadelphia Mixing Solutions Ltd.
- Charles Ross & Son Company
- Silverson Machines Inc.
- IKA-Werke GmbH & Co. KG
- amixon GmbH
- Komax Systems Inc.
- Landia A/S
- Satake Chemical Equipment Mfg. Ltd.
- Dynamix Agitators Inc.
- Statiflo International Ltd.
- Scott Turbon Mixer Inc.
- INOXPA SAU
- Enviropax Inc.
- Arde Barinco Inc.
- ITT Bornemann GmbH
- Zhejiang Great Wall Mixers Co., Ltd.
第7章 市場機會與未來展望
According to Mordor Intelligence, the industrial mixers market size is expected to grow from USD 2.88 billion in 2025 to USD 3.1 billion in 2026 and is forecast to reach USD 4.48 billion by 2031 at 7.64% CAGR over 2026-2031.
This report is Segmented by Product Type (Agitators, Special Mixers, Submersible Mixers, and More), End-User Industry (Chemicals, Water and Wastewater, Food and Beverage, Petrochemicals, Pharmaceuticals, Energy, and More), Power Rating (< 5 KW, 5-15 KW, and More), and Geography (North America, South America, Europe, Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Industrial Mixers Market Trends and Insights
Stricter Sanitary Mandates in Food and Pharma
Food-grade and pharmaceutical plants now specify electropolished surfaces, crevice-free welds, and validated clean-in-place protocols to satisfy EHEDG 2024 updates and FDA 21 CFR 110.35 requirements. Equipment suppliers that deliver certified hygienic designs secure premium pricing while smaller fabricators face rising compliance costs. In pharmaceuticals, continuous production lines rely on documented mixing uniformity, driving the procurement of high-shear and magnetically driven mixers that are validated under good manufacturing practice audits. Retrofits to legacy agitators often fail validation, accelerating outright replacement. This dynamic strengthens competitive barriers and cements long-term service contracts around sanitary assets.
Energy-Efficient High-Torque Motor Adoption
IE5 synchronous reluctance motors, paired with variable-frequency drives, reduce mixer energy draw by up to 20% compared to legacy induction units, while delivering the torque needed for high-viscosity slurries. Regulations already mandate IE4 minimum efficiency above 0.75 kW, and similar rules under discussion in India and Brazil will accelerate fleet renewal. Plant engineers link drives to edge analytics that reduce speed during low-load phases, extending seal life and lowering power bills across the industrial mixer market. Vendors that bundle motors with digital control panels command higher margins and cultivate data-driven service revenues.
Raw-Material Price Volatility (Stainless Steel, Alloys)
Stainless steel prices fluctuated by 15-20% in 2024 as nickel prices traded between USD 16,500 and USD 20,000 per metric ton, eroding margins for mixer fabricators. Specialty alloys, such as Hastelloy C-276, followed similar spikes tied to aerospace demand, forcing OEMs to renegotiate long-term frame contracts and hedge their purchases. Larger vendors leverage global procurement and inventory pooling to buffer cost shocks, but regional job shops struggle to pass increases through, curbing new capacity additions in the industrial mixers industry. Supply-chain diversification into Indonesia and the United States may stabilize pricing, but it introduces higher baseline costs that will be passed through to equipment prices.
Other drivers and restraints analyzed in the detailed report include:
- Surge in Wastewater Recycling Capacity Additions
- Bioreactor Retrofits for Cultivated-Meat Pilots
- High Capex vs. Alternative Inline Dosing Systems
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Agitators commanded a 35.85% share of the industrial mixers market in 2025, underpinned by decades of performance data in bulk chemical, mineral processing, and water treatment operations. Their robust frames and modular impeller libraries allow economical customization across vessel sizes exceeding 100 m3. The industrial mixers market size for agitators is expected to grow steadily as replacement cycles align with increasingly stringent sanitary and energy norms. High-shear mixers, however, are expected to grow at an 8.05% CAGR, driven by demand for emulsification in biotechnology and advanced materials. Inline rotor-stator designs deliver micron-level particle reduction, supporting continuous wet-milling and pre-dispersion tasks that upstream equipment cannot meet. Suppliers integrate real-time torque and temperature sensors that feed digital twins, thereby improving scale-up accuracy and reducing validation time in regulated segments, such as the pharmaceutical industry.
Digital integration reshapes every product line. Agitator vendors embed vibration sensors on gearbox housings and shafts, feeding AI models that forecast bearing life. Submersible mixer makers redesign housings with composite shrouds that cut weight while resisting chloride stress cracking in seawater desalination plants. Static and jet mixers, which are normally energy-neutral, now ship with differential-pressure transmitters that allow operators to verify mixing intensity without intrusive probes. Across categories, IoT frameworks enable pay-per-mix service models, where OEMs bill for uptime rather than equipment alone, thereby expanding recurring revenue streams within the industrial mixers market.
Complete Report Scope:
- By Product Type
- Agitators
- Special Mixers
- Submersible Mixers
- High-shear Mixers
- Static Mixers
- Jet Mixers
- Other Product Types
- By End-User Industry
- Chemicals
- Water and Wastewater
- Food and Beverage
- Petrochemicals
- Pharmaceuticals
- Pulp and Paper
- Energy (Power and Renewables)
- Mining and Minerals
- Other Process Industries
- By Power Rating
- < 5 kW
- 5 - 15 kW
- 15 - 50 kW
- > 50 kW
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- South-East Asia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific holds 29.55% of global revenue and is on track for an 8.18% CAGR through 2031, reflecting government-backed chemical capacity additions, expanding pharmaceutical exports, and aggressive municipal wastewater spending in China and India. In China, refinery off-gas hydrogen recycling creates demand for ATEX-compliant jet mixers, while mega-sized membrane bioreactor projects specify high-efficiency submersible units. India's production-linked incentive scheme for active pharmaceutical ingredients stimulates upgrades to inline high-shear mixers, and Southeast Asia's palm-oil downstream clusters adopt special agitators for deodorization stages. Local fabrication lowers cost, but international OEMs dominate premium tiers that demand documented validation.
North America commands a sizable installed base anchored by biotech clusters in Boston, San Diego, and Toronto. Continuous biologic manufacturing lines require sanitary high-shear mixers with single-use flow paths, while shale gas processing relies on jet mixers for crude desalting. Stringent FDA and EPA regulations promote replacement cycles that favor energy-efficient designs. Mexico's chemical and food manufacturing industries import modular mixing skids from the United States, utilizing near-shore supply chains to minimize lead times. Digital retrofits funded under the U.S. Inflation Reduction Act channel investment toward predictive maintenance modules across legacy fleets within the industrial mixers market.
Europe emphasizes sustainability and operational excellence, guided by the EU Green Deal. Plants adopt IE5 motors, magnetically coupled seals, and low-carbon stainless alloys certified under environmental product declarations. Chemical parks in Germany and the Netherlands prioritize mixers that integrate with plant-wide digital twins. ATEX and IECEx mandates for hydrogen electrolysis units increase certification costs, yet they also protect incumbent suppliers with robust documentation systems. Circular economy initiatives are expanding demand for mixers in plastic recycling, anaerobic digestion, and organic fertilizer production. Collectively, these drivers promote a balanced yet technologically intensive outlook for the industrial mixer market in Europe.
- SPX FLOW Inc.
- Sulzer Ltd.
- Alfa Laval AB
- Xylem Inc.
- GEA Group AG
- EKATO HOLDING GmbH
- Philadelphia Mixing Solutions Ltd.
- Charles Ross & Son Company
- Silverson Machines Inc.
- IKA-Werke GmbH & Co. KG
- amixon GmbH
- Komax Systems Inc.
- Landia A/S
- Satake Chemical Equipment Mfg. Ltd.
- Dynamix Agitators Inc.
- Statiflo International Ltd.
- Scott Turbon Mixer Inc.
- INOXPA S.A.U.
- Enviropax Inc.
- Arde Barinco Inc.
- ITT Bornemann GmbH
- Zhejiang Great Wall Mixers Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Stricter sanitary mandates in food and pharma
- 4.2.2 Energy-efficient high-torque motor adoption
- 4.2.3 Surge in wastewater recycling capacity additions
- 4.2.4 Bioreactor retrofits for cultivated-meat pilots
- 4.2.5 On-site chemical blending for battery-grade materials
- 4.2.6 Modular "mix-on-demand" skids for remote mining camps
- 4.3 Market Restraints
- 4.3.1 Raw-material price volatility (stainless steel, alloys)
- 4.3.2 High capex vs. alternative inline dosing systems
- 4.3.3 Rising ATEX/IECEx certification costs for hydrogen hubs
- 4.3.4 Skilled-operator shortage for large-diameter agitators
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors
- 4.9 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Agitators
- 5.1.2 Special Mixers
- 5.1.3 Submersible Mixers
- 5.1.4 High-shear Mixers
- 5.1.5 Static Mixers
- 5.1.6 Jet Mixers
- 5.1.7 Other Product Types
- 5.2 By End-User Industry
- 5.2.1 Chemicals
- 5.2.2 Water and Wastewater
- 5.2.3 Food and Beverage
- 5.2.4 Petrochemicals
- 5.2.5 Pharmaceuticals
- 5.2.6 Pulp and Paper
- 5.2.7 Energy (Power and Renewables)
- 5.2.8 Mining and Minerals
- 5.2.9 Other Process Industries
- 5.3 By Power Rating
- 5.3.1 < 5 kW
- 5.3.2 5 - 15 kW
- 5.3.3 15 - 50 kW
- 5.3.4 > 50 kW
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Rest of Europe
- 5.4.4 Asia-Pacific
- 5.4.4.1 China
- 5.4.4.2 Japan
- 5.4.4.3 India
- 5.4.4.4 South Korea
- 5.4.4.5 South-East Asia
- 5.4.4.6 Rest of Asia-Pacific
- 5.4.5 Middle East and Africa
- 5.4.5.1 Middle East
- 5.4.5.1.1 Saudi Arabia
- 5.4.5.1.2 United Arab Emirates
- 5.4.5.1.3 Rest of Middle East
- 5.4.5.2 Africa
- 5.4.5.2.1 South Africa
- 5.4.5.2.2 Egypt
- 5.4.5.2.3 Rest of Africa
- 5.4.5.1 Middle East
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 SPX FLOW Inc.
- 6.4.2 Sulzer Ltd.
- 6.4.3 Alfa Laval AB
- 6.4.4 Xylem Inc.
- 6.4.5 GEA Group AG
- 6.4.6 EKATO HOLDING GmbH
- 6.4.7 Philadelphia Mixing Solutions Ltd.
- 6.4.8 Charles Ross & Son Company
- 6.4.9 Silverson Machines Inc.
- 6.4.10 IKA-Werke GmbH & Co. KG
- 6.4.11 amixon GmbH
- 6.4.12 Komax Systems Inc.
- 6.4.13 Landia A/S
- 6.4.14 Satake Chemical Equipment Mfg. Ltd.
- 6.4.15 Dynamix Agitators Inc.
- 6.4.16 Statiflo International Ltd.
- 6.4.17 Scott Turbon Mixer Inc.
- 6.4.18 INOXPA S.A.U.
- 6.4.19 Enviropax Inc.
- 6.4.20 Arde Barinco Inc.
- 6.4.21 ITT Bornemann GmbH
- 6.4.22 Zhejiang Great Wall Mixers Co., Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 全球工業攪拌機市場:市場規模、佔有率、趨勢和成長分析(2026-2034)
 預混合料攪拌機市場預測-按類型、產能、應用和地區分類的全球分析-2034年
 工業攪拌機市場規模、佔有率和趨勢分析報告:按技術、額定功率、類型、最終用途、地區和細分市場分類(2026-2033 年)
 全球高剪切混合機市場:依系統類型、配置、混合應用、應用領域和地區分類-預測(至2031年)
 攪拌機市場機會、成長要素、產業趨勢分析及2026-2035年預測。
 2026年全球電動可攜式水泥攪拌機市場報告
 工業攪拌機市場:按類型、容量、運作模式、速度、產量、最終用途和應用分類-2026-2032年全球市場預測磁耦合攪拌機市場:按攪拌機類型、應用、最終用戶和分銷管道分類 - 全球預測(2026-2032 年)V型乾粉混合機市場:按操作類型、產能、材料和應用分類,全球預測(2026-2032年)家用和麵機市場:按技術、控制類型、容量和分銷管道分類,全球預測(2026-2032年)