


 |
市場調查報告書
商品編碼
2125334
齒輪幫浦:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Gear Pumps - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,齒輪幫浦市場規模將從 2025 年的 49 億美元成長到 2026 年的 50.4 億美元,然後在 2031 年達到 58.2 億美元,2026 年至 2031 年的複合年成長率為 2.93%。
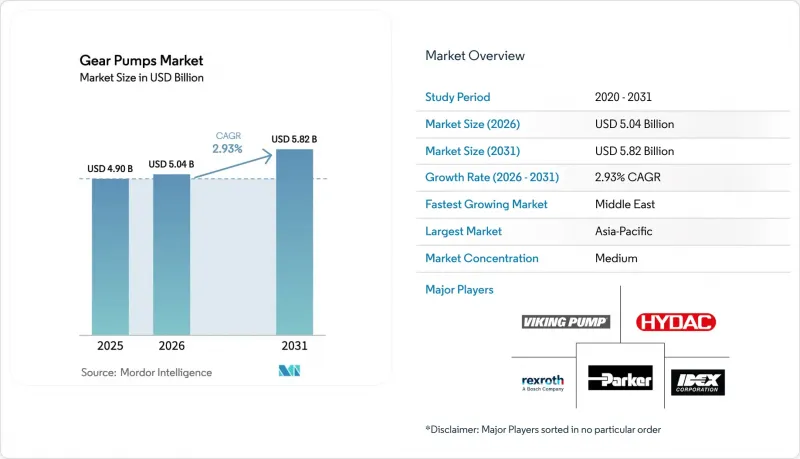
本報告按類型(外部嚙合齒輪泵、內嚙合齒輪泵)、材質(鑄鐵、不銹鋼等)、終端用戶行業(石油天然氣、化學、食品飲料、製藥、發電等)、排氣量(定排量、變排量)和地區(北美、歐洲、亞太等)進行細分。市場預測以美元計價。
全球齒輪幫浦市場趨勢及洞察
上游油氣專案需求增加
傳統型頁岩油氣和海上開發項目的資本投資復甦,推動了對能夠承受高磨蝕性鑽井泥漿和高腐蝕性壓裂液的高壓外嚙合齒輪泵的訂單成長。浮體式生產儲卸油船(FPSO)依賴滿足高可靠性要求的可靠液壓系統。鑽井公司正在指定採用先進的表面處理流程和更嚴格的公差,以延長高腐蝕性和高溫油井中的使用壽命,這推動了設計的不斷改進。
石化聯合企業產能快速擴張
亞太地區數十億美元的裂解裝置和聚合物計畫正在推動全球產能的成長,每個計畫都需要數百台專用齒輪幫浦用於催化劑循環、聚合物輸送和計量操作。中國的在地採購政策和中東的優惠融資進一步刺激了需求,而美國墨西哥灣沿岸地區瓶頸問題的解決則是另一個成長來源。
工業資本投資週期的波動
能源、採礦和化學產業的投資波動導致累積訂單,對生產計畫和現金流管理造成壓力。原物料價格上漲和前置作業時間延長進一步加劇了不確定性,迫使供應商增加庫存並設定更靈活的交貨日期。
細分市場分析
2025年,外嚙合齒輪幫浦佔據了齒輪幫浦市場61.78%的佔有率。這反映了其卓越的耐壓性能(超過3000 psi)和對污染流體的高耐受性。其固定的齒形簡化了製造流程並降低了維護成本,使其在鑽井、水力壓裂和重工業領域保持領先地位。內嚙合齒輪幫浦雖然市佔率較小,但由於其高容積效率、運轉噪音低和無脈動排放等優點,正以4.55%的複合年成長率成長。隨著食品、製藥和精細化工行業的用戶對衛生、低噪音性能的需求不斷成長,預計內嚙合齒輪泵的市場規模將進一步擴大。
為了符合衛生法規,製藥公司擴大指定使用採用 316L 不銹鋼製成的無縫內部結構。派克漢尼芬 (Parker Hanifin) 符合 FDA 標準的系列產品正是這一轉變的象徵,它將磁力驅動與拋光內部結構相結合,從而實現了與 CIP(就地清洗)兼容的輸送操作。在石油和天然氣行業,外置泵仍然佔據主導地位,因為在該行業,堅固耐用的材質和豐富的現場經驗往往比噪音和效率更為重要。同時,航太原始設備製造商 (OEM) 正在探索使用緊湊型內建泵,以減輕下一代飛行控制系統的重量並降低能耗。
由於鑄鐵成本低、加工性能優異,且在非腐蝕性應用中具有足夠的機械強度,預計到2025年,鑄鐵將佔總銷售額的50.88%。鑄鐵齒輪幫浦市場涵蓋工業液壓、鑽井泥漿循環和一般工廠運作等領域。不銹鋼預計將以每年4.01%的速度成長,其在生物製程、乳製品和特種化學品等行業的應用日益廣泛,這些行業的腐蝕和衛生管理對總擁有成本有著顯著影響。雙相不銹鋼合金憑藉其優異的耐腐蝕性和價格優勢,在海上和水面設備領域逐漸佔有一席之地。
此次材料升級旨在滿足更嚴格的檢驗要求,特別是FDA 21 CFR Part 11的電子記錄要求,其中不銹鋼零件更受青睞,因為它可以降低清潔程序的複雜性。鑄鐵在惡劣環境下使用的移動機械中仍然是一種強力的選擇,因為在這些環境中,磨損和衝擊而非腐蝕決定了設備的生命週期經濟性。將鑄鐵外殼與不銹鋼齒輪相結合的混合組件為尋求分階段升級的中型化工廠提供了一種折衷方案。
區域分析
亞太地區35.29%的市佔率凸顯了其作為石化、電子和重型機械製造中心的地位。中國沿海工業區的大型計畫以及印度新建的專用貨運走廊為液壓設備的持續應用奠定了堅實的基礎。東南亞國家正吸引來自高成本地區的工廠,進一步擴大了小型齒輪幫浦的部署規模。政府對清潔能源的支持,包括太陽能晶片製造廠和電池工廠的建設,對泵浦提出了更高的衛生性和耐化學腐蝕性要求。
受沙烏地阿拉伯「2030願景」下200億美元石化投資的推動,中東地區預計將實現3.41%的複合年成長率。這將帶動乙烯、聚乙烯和特種化學品工廠對耐腐蝕齒輪泵的需求成長。阿拉伯聯合大公國(阿拉伯聯合大公國)致力於成為該地區的製造地,營運鋁、鋼和模組化住宅工廠,並運作分散式液壓網路。卡達的港口擴建和工業城建設需要配備高壓外置泵的強勁施工機械。
北美和歐洲是成熟的市場,但仍湧現出創新發展。美國頁岩氣鑽探商訂購高耐磨泵組的同時,也在部署預測性維護感測器,將即時資料傳輸到雲端平台。歐洲的噪音和能源效率法規正推動原始設備製造商(OEM)採用可變和低噪音設計,這刺激了研發活動。德國機械製造商正將智慧齒輪泵整合到自動化生產線中,以響應該國的「工業4.0」計劃。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 上游油氣專案需求增加
- 石化聯合企業產能快速擴張
- 移動機械向模組化液壓系統過渡
- 非公路用設備的電氣化需要安靜可靠的液壓動力來源。
- 智慧工廠的引入正在加速水泵的維修,以實現預測性維護。
- 要過渡到使用生物基液壓油,需要使用相容的齒輪泵。
- 市場限制因素
- 工業資本投資週期的波動性
- 螺旋泵和葉片泵在高黏度應用中的擴展
- 對連續運轉馬達的能效規定更加嚴格。
- 特種合金鑄件供應鏈中斷
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 宏觀經濟因素的影響
第5章 市場規模與成長預測
- 按類型
- 外齒輪泵浦
- 內齒輪泵浦
- 材料
- 鑄鐵
- 不銹鋼
- 其他材料
- 按最終用戶行業分類
- 石油和天然氣
- 化學品
- 食品/飲料
- 製藥
- 發電
- 其他終端用戶產業
- 按引擎排氣量
- 固定位移
- 可變排氣量
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 澳洲
- 其他亞太國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 其他中東國家
- 非洲
- 南非
- 埃及
- 其他非洲國家
- 中東
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Bosch Rexroth AG
- Parker-Hannifin Corporation
- Hydac International GmbH
- Viking Pump, Inc.
- IDEX Corporation
- Haight Pump Company, Inc.
- Danfoss A/S
- Kawasaki Heavy Industries Ltd.
- Bailey International, LLC
- Flowserve Corporation
- Albany Pumps Ltd.
- Sumitomo Heavy Industries, Ltd.
- Eaton Corporation plc
- Bucher Hydraulics GmbH
- Marzocchi Pompe SpA
- Yuken Kogyo Co., Ltd.
- Liquiflo Equipment Corporation
- Cascon, Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the gear pumps market size is expected to grow from USD 4.9 billion in 2025 to USD 5.04 billion in 2026 and is forecast to reach USD 5.82 billion by 2031 at 2.93% CAGR over 2026-2031.
This report is Segmented by Type (External Gear Pump, and Internal Gear Pump), Material (Cast Iron, Stainless Steel, and More), End-User Industry (Oil and Gas, Chemical, Food and Beverage, Pharmaceutical, Power Generation, and More), Displacement (Fixed Displacement, and Variable Displacement), and Geography (North America, Europe, Asia Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Gear Pumps Market Trends and Insights
Increasing Demand from Oil and Gas Upstream Projects
Rebounding capital spending across unconventional shale and offshore plays is driving orders for high-pressure external gear pumps that can withstand abrasive drilling muds and aggressive fracturing fluids. Floating production, storage, and offloading vessels rely on robust hydraulic packages, which maintain high reliability requirements. Drillers specify advanced surface treatments and tighter tolerances to prolong service life in corrosive, high-temperature wells, driving continued design upgrades.
Rapid Capacity Expansion in Petrochemical Complexes
Asia-Pacific's multi-billion-dollar cracker and polymer projects dominate global capacity additions, each requiring hundreds of specialty gear pumps for catalyst circulation, polymer transfer, and metering duties. Local content policies in China and preferential financing in the Middle East further stimulate demand, while U.S. Gulf Coast debottlenecking secures a secondary growth stream.
Volatility in Industrial Capex Cycles
Boom-and-bust investment patterns in energy, mining, and chemicals result in uneven project backlogs, which tax production planning and cash-flow management. Inflationary raw material spikes and lengthening lead times add further uncertainty, prompting suppliers to hold larger inventories and offer more flexible delivery schedules.
Other drivers and restraints analyzed in the detailed report include:
- Shift Toward Modular Hydraulic Systems in Mobile Machinery
- Electrification of Off-Highway Equipment Requires Silent Hydraulic Sources
- Growing Penetration of Screw and Vane Pumps in High-Viscosity Duties
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
External gear pumps accounted for 61.78% of the gear pumps market in 2025, reflecting superior pressure capability above 3,000 psi and robust tolerance of contaminated fluids. Fixed-tooth geometry simplifies machining and lowers service costs, sustaining dominance in drilling, fracturing, and heavy manufacturing. Internal gear pumps, although smaller in share, advance at a 4.55% CAGR due to their higher volumetric efficiency and quiet, pulse-free delivery. The gear pumps market size for internal variants is set to widen as food, pharma, and fine-chemical operators demand sanitary, low-noise performance.
Pharmaceutical facilities are increasingly specifying crevice-free internal designs in 316L stainless steel to comply with hygiene regulations. Parker Hannifin's FDA-compliant series exemplifies this pivot, pairing magnetic drives with polished internals for CIP-compatible transfer duties. External units retain primacy in the oil and gas industry, where rugged metallurgy and field-service familiarity often trump noise or efficiency. Aerospace OEMs, however, are exploring compact internal pumps to reduce weight and power draw in next-generation flight control systems.
Cast iron accounted for 50.88% of 2025 revenue due to its low cost, proven machinability, and ample mechanical strength in non-corrosive applications. The gear pumps market size derived from cast iron applications spans industrial hydraulics, drilling mud circulation, and general factory service. Stainless steel, projected to grow at a 4.01% annual rate, is capturing adoption across bioprocess, dairy, and specialty chemicals, where corrosion or hygiene drives total cost of ownership. Duplex alloys are gaining a foothold in offshore topside packages, striking a balance between resistance and price.
Material upgrades track stricter validation demands, especially FDA 21 CFR Part 11 electronic record requirements that favor stainless units to reduce cleaning protocol complexity. Cast iron's share endures in rugged mobile machines, where abrasion and impact, not corrosion, govern lifecycle economics. Hybrid assemblies that combine cast iron housings with stainless gears offer a compromise for mid-tier chemical plants pursuing incremental upgrades.
Complete Report Scope:
- By Type
- External Gear Pumps
- Internal Gear Pumps
- By Material
- Cast Iron
- Stainless Steel
- Other Materials
- By End-User Industry
- Oil and Gas
- Chemical
- Food and Beverage
- Pharmaceutical
- Power Generation
- Other End-User Industries
- By Displacement
- Fixed Displacement
- Variable Displacement
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
Asia-Pacific's 35.29% share underscores its role as the center of gravity for petrochemical, electronics, and heavy equipment manufacturing. Large-scale projects in China's coastal industrial zones and India's new dedicated freight corridors underpin a steady pipeline of hydraulic installations. Southeast Asian nations attract factory relocations from higher-cost locales, further expanding the installed base of smaller gear pumps. Government incentives for clean energy, including solar wafer fabs and battery plants, introduce new hygienic and chemical-resistant pump requirements.
The Middle East is projected to record a 3.41% CAGR, driven by USD 20 billion in petrochemical investments under Saudi Vision 2030, which will demand corrosion-resistant gear pumps for ethylene, polyethylene, and specialty chemical units. The UAE aims to establish itself as a regional manufacturing hub, commissioning aluminum, steel, and modular housing factories that utilize decentralized hydraulic networks. Qatar's harbor expansions and industrial cities require robust construction machinery equipped with high-pressure external pumps.
North America and Europe remain mature yet innovative. U.S. shale drillers order abrasion-tolerant pumping packages while embracing predictive maintenance sensors that feed real-time data to cloud platforms. European regulations on noise and efficiency are pushing OEMs toward variable, low-decibel designs, thereby bolstering R&D. Germany's machine builders are embedding smart gear pumps into automated lines, aligning with the country's Industry 4.0 blueprint.
- Bosch Rexroth AG
- Parker-Hannifin Corporation
- Hydac International GmbH
- Viking Pump, Inc.
- IDEX Corporation
- Haight Pump Company, Inc.
- Danfoss A/S
- Kawasaki Heavy Industries Ltd.
- Bailey International, LLC
- Flowserve Corporation
- Albany Pumps Ltd.
- Sumitomo Heavy Industries, Ltd.
- Eaton Corporation plc
- Bucher Hydraulics GmbH
- Marzocchi Pompe S.p.A.
- Yuken Kogyo Co., Ltd.
- Liquiflo Equipment Corporation
- Cascon, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Demand from Oil and Gas Upstream Projects
- 4.2.2 Rapid Capacity Expansion in Petrochemical Complexes
- 4.2.3 Shift Toward Modular Hydraulic Systems in Mobile Machinery
- 4.2.4 Electrification of Off-Highway Equipment Requires Silent Hydraulic Sources
- 4.2.5 Smart Factory Adoption Driving Predictive-Maintenance Retrofit Pumps
- 4.2.6 Transition to Bio-Based Hydraulic Fluids Necessitates Compatible Gear Pumps
- 4.3 Market Restraints
- 4.3.1 Volatility in Industrial Capex Cycles
- 4.3.2 Growing Penetration of Screw and Vane Pumps in High-Viscosity Duties
- 4.3.3 Stricter Energy-Efficiency Regulations for Continuous-Duty Motors
- 4.3.4 Supply Chain Disruptions in Specialty Alloy Castings
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 External Gear Pumps
- 5.1.2 Internal Gear Pumps
- 5.2 By Material
- 5.2.1 Cast Iron
- 5.2.2 Stainless Steel
- 5.2.3 Other Materials
- 5.3 By End-User Industry
- 5.3.1 Oil and Gas
- 5.3.2 Chemical
- 5.3.3 Food and Beverage
- 5.3.4 Pharmaceutical
- 5.3.5 Power Generation
- 5.3.6 Other End-User Industries
- 5.4 By Displacement
- 5.4.1 Fixed Displacement
- 5.4.2 Variable Displacement
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Russia
- 5.5.2.5 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 Middle East
- 5.5.4.1.1 Saudi Arabia
- 5.5.4.1.2 United Arab Emirates
- 5.5.4.1.3 Rest of Middle East
- 5.5.4.2 Africa
- 5.5.4.2.1 South Africa
- 5.5.4.2.2 Egypt
- 5.5.4.2.3 Rest of Africa
- 5.5.4.1 Middle East
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Bosch Rexroth AG
- 6.4.2 Parker-Hannifin Corporation
- 6.4.3 Hydac International GmbH
- 6.4.4 Viking Pump, Inc.
- 6.4.5 IDEX Corporation
- 6.4.6 Haight Pump Company, Inc.
- 6.4.7 Danfoss A/S
- 6.4.8 Kawasaki Heavy Industries Ltd.
- 6.4.9 Bailey International, LLC
- 6.4.10 Flowserve Corporation
- 6.4.11 Albany Pumps Ltd.
- 6.4.12 Sumitomo Heavy Industries, Ltd.
- 6.4.13 Eaton Corporation plc
- 6.4.14 Bucher Hydraulics GmbH
- 6.4.15 Marzocchi Pompe S.p.A.
- 6.4.16 Yuken Kogyo Co., Ltd.
- 6.4.17 Liquiflo Equipment Corporation
- 6.4.18 Cascon, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 齒輪幫浦市場:按類型、材質、排氣量和終端應用產業分類-2026-2032年全球市場預測
 2026-2030年全球高壓熔體幫浦市場磁力耦合內嚙合齒輪幫浦市場:按類型、黏度、材料、驅動機構、壓力、流量、分配通道、應用、終端用戶產業分類-全球預測,2026-2032年
 齒輪幫浦市場-策略分析與預測(2026-2031)磁力耦合外嚙合齒輪幫浦市場:依驅動力、幫浦排量、壓力範圍、材料和終端應用產業分類,全球預測,2026-2032年磁力耦合齒輪幫浦市場按產品類型、結構材料、流量、驅動類型、最終用途產業和銷售管道,全球預測,2026-2032年行星式旋轉幫浦市場:依產品類型、驅動類型、材料、產業和銷售管道,全球預測(2026-2032年)
 液壓齒輪幫浦市場分析及預測(至2035年):依類型、產品、應用、技術、組件、最終用戶、部署、功能、安裝類型及設備分類齒輪幫浦市場分析及預測(至2035年):依類型、產品類型、應用、技術、材質、組件、最終用戶、製程、安裝類型及功能分類
 2026年全球內齒輪幫浦市場報告