


 |
市場調查報告書
商品編碼
2124757
美國落水槽防護罩:市場佔有率分析、行業趨勢和統計數據以及成長預測(2026-2031 年)United States Gutter Guards - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,2025 年美國雨水槽防護罩市值為 11.1 億美元,預計到 2031 年將從 2026 年的 11.6 億美元成長至 14.3 億美元,預測期(2026-2031 年)的複合年成長率為 4.24%。
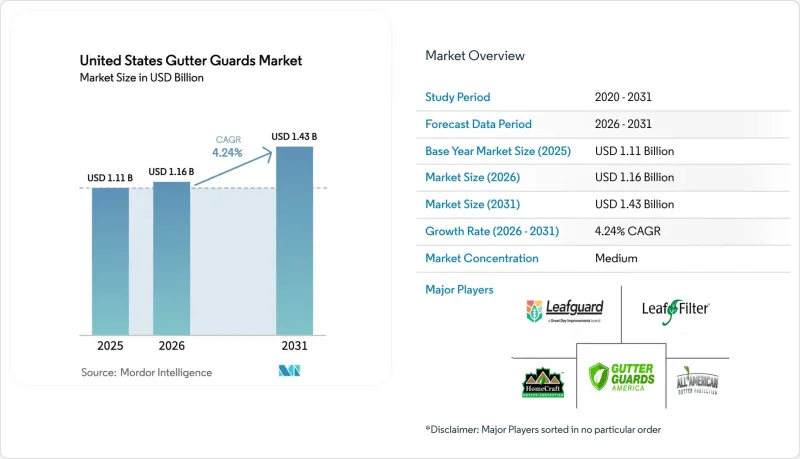
本報告按產品類型(微孔篩網、標準篩網及其他)、材料(鋁、不銹鋼、乙烯基/塑膠、發泡材及其他,包括銅)、最終用戶(住宅、商業、工業/機構)和地區(東北部、中西部、東南部及其他地區)進行細分。市場預測以美元計價。
美國雨水槽防護罩市場的趨勢與洞察
住宅維修和屋頂更換方面的支出增加
根據哈佛大學住宅研究聯合中心發布的《房屋修繕活動領先指標》(LIRA),預計到2026年初,住宅維修支出將達到5,240億美元。這將創下歷史新高,儘管預計成長將從2024年7%的峰值放緩至2025年的5%和2026年的3%。低利率抵押房屋抵押貸款的鎖定效應持續推動房屋翻新而非搬家。因此,能夠提升房產價值和增強房屋耐久性的屋頂及相關外部工程被視為極具吸引力的短期投資選擇。據報道,更換屋頂是屋主在住宅翻新中最滿意的投資,這也印證了承包商在屋頂提升銷售項目中提案排水溝防護裝置,以防止新系統中出現堵塞和溢水的情況。這一趨勢與疫情後重新評估後房屋修繕活動的穩定成長相吻合,表明存在比傳統週期性指標先前所反映的更大、更持久的支出基礎。隨著承包商在現場搭建鷹架並安排工人,安裝效率得以提高,美國落水槽防護網市場也因此受益。這縮短了額外安裝所需的時間,並有助於提高客戶對其他防護網產品的轉換率。因此,屋頂更換仍是擴大微網產品應用範圍、維持美國整個落水槽防護網市場升級產品組合的關鍵途徑。
極端降雨和颶風頻率增加
2025年,氣候變遷將推動市場需求,預計屆時將發生多起造成數十億美元損失的風暴災害,以及持續強降雨,將考驗主要都會大都會圈的屋頂排水能力。對美國罕見極端降雨設計值的預測表明,隨著氣候變暖,降雨強度將進一步增加,這將對傳統排水溝系統構成挑戰,同時也凸顯了防雜物裝置的重要性,這些裝置即使在暴雨期間也能確保水流順暢。物理學表明,極端降雨的強度往往與大氣中的水蒸氣含量成正比,而分析和教育材料也強調,氣候變暖將增加大氣中的水蒸氣含量,從而導致更強烈、持續時間更短的降雨。 2025年大西洋颶風季僅出現了13個命名風暴(低於年均14.4個),但累積氣旋能量(ACE)高達132.4個單位,比1991年至2020年的基準值高出9%,並產生了三個五級颶風(艾琳、亨伯特和梅麗莎)。科羅拉多州立大學熱帶氣象計畫檢驗,這是有史以來第二高的數字,僅次於2005年的四個。為了因應保險業的需求,佛羅裡達州和墨西哥灣沿岸各州實施了風災減免補貼計畫。根據佛羅裡達州保險監理部門資訊披露,這些地區的住宅如果安裝排水溝系統以防止樹葉和雜物進入房屋,即可享受5%至8%的風災保險費減免,這項經濟獎勵可在10年保單期內抵消15%至20%的安裝成本。
高昂的初始安裝成本與自行清潔的比較
高品質的微網系統與低成本的DIY防護罩和不定期的專業清潔服務競爭,前期投入成本成為價格敏感型家庭的一大障礙。大型量販店以專業套裝的形式銷售鋁製和不銹鋼網,凸顯了價格差異,因為精打細算的買家需要在耐用性和維護成本節省之間進行權衡。住宅在安裝防護罩之前通常還需要承擔更換排水溝或維修簷板等額外費用,這增加了總成本,並迫使他們將防護罩的安裝與其他老舊房屋的維修放在一起優先考慮。在商業建築中,較長的屋頂線和複雜的施工條件增加了工期和安全措施,使得安裝成本在預算核准討論中成為更為重要的考慮因素。明確的性能保證和對過濾及集水功能的獨立檢驗有助於消除人們成本績效的疑慮,但投資回報的前景仍然更多地取決於避免維護和降低風險,而不是短期節省。這些因素可能會減緩那些優先考慮短期現金流的消費者的接受速度,儘管高級產品的普及率不斷提高,但仍會給美國排水溝防護罩市場帶來持續的阻力。
細分市場分析
到2025年,標準網狀和篩網將佔據美國落水槽防護網市場的41.23%。這反映了承包商對它們的熟悉程度,以及它們在注重成本控制、優先考慮基本碎屑防護的項目中的經濟實惠。整合系統在新建築和住宅整體外牆維修中越來越受歡迎。這是因為其改造的複雜性較低,並且提供終身保修,使其成為尋求單一品牌解決方案的屋主的理想選擇。同時,表面張力蓋板和泡沫刷嵌件在預算有限和DIY專案中仍然發揮作用,但它們的更換週期和性能限制抵消了其較低的初始成本優勢。屋頂工和改造工在搭建鷹架時增加防護網的銷售,使得防護網的普及範圍更廣,價格區間也更廣,從而進一步提升了美國落水槽防護網市場中高級產品的佔比。
不同產品類型的成長差異取決於其卓越的性能和品牌定位。微網產品的供應商正著重強調產品的耐用性和第三方檢驗結果,以增強消費者對長期防止堵塞的信心。產品可靠性訊息,包括獎項和實驗室耐久性測試結果,有助於消除此前因種種原因推遲購買或依賴定期清潔的住宅的疑慮。建築商和改造商也在尋求能夠避免與屋頂保固條款衝突的產品,在建築商保固有效的市場,他們更傾向於選擇能夠安裝在屋簷和簷板上而不會損壞屋頂材料或底層防水層的款式。這種分銷管道正被全國性的承包商所採用,他們在屋頂和外牆項目中交叉銷售防護罩,同時也受到私營供應商的推動,這些供應商正在擴大業務範圍,並將產品和安裝整合到單一服務體系中。這些變化使得人們更加關注成熟的設計和一體化的安裝網路,這一趨勢正持續影響著美國屋簷防護罩市場的產品組合和利潤率。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 住宅維修和屋頂更換方面的支出增加
- 異常強降雨和颶風發生頻率增加
- 美國老舊住宅存量亟需維修
- 微網高級系統日益普及
- 雨水槽防護罩與智慧雨水收集系統的整合
- 鋁屏生產能力回流
- 市場限制因素
- 高昂的初始安裝成本與DIY清潔方法的比較。
- 熟練安裝工人季節性人手不足
- 關於屋頂保固的擔憂
- 一種無需排水溝的新型自清潔屋頂的替代方案。
- 產業價值鏈分析
- 監理情勢
- 波特五力模型
- 洞察最新市場趨勢與創新
- 近期市場趨勢分析(新產品發布、策略性舉措、投資、合作、合資、業務擴張、併購等)
第5章 市場規模與成長預測
- 依產品類型
- 微網篩
- 標準網眼
- 反向彎曲/表面張力蓋
- 刷毛/刷芯
- 泡棉襯墊
- 一體成型無縫雨水槽防護系統
- 材料
- 鋁
- 不銹鋼
- 乙烯基/塑膠
- 其他(發泡材、銅)
- 最終用戶
- 住宅
- 商業
- 產業和設施
- 按地區
- 東北
- 中西部
- 東南部
- 西南
- 西
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- LeafGuard
- LeafFilter North, Inc.
- Gutter Guards America
- All American Gutter Protection
- HomeCraft Gutter Protection
- MasterShield(Major Marketing Group)
- Gutterglove Inc./Raptor
- Amerimax Building Products
- FlexxPoint, Inc.
- GutterStuff
- Gutter Helmet(EMCO)
- Klean Gutter
- Waterlock Gutter Guards
- EZ Gutter Guard
- GutterTopper
- CopperCraft(OMNIMAX)
- Spectra Gutter Systems
- Senox Corporation
- Cornerstone Building Brands
- Gibraltar Industries
第7章 市場機會與未來展望
According to Mordor Intelligence, the United States gutter guards market size was valued at USD 1.11 billion in 2025 and is estimated to grow from USD 1.16 billion in 2026 to reach USD 1.43 billion by 2031, at a CAGR of 4.24% during the forecast period (2026-2031).
This report is Segmented by Product Type (Micro-Mesh Screens, Standard Mesh and Screens, and More), Material (Aluminum, Stainless Steel, Vinyl or Plastic, Others Including Foam and Copper), End User (Residential, Commercial, Industrial, and Institutional), and Geography (Northeast, Midwest, South, and More). The Market Forecasts are Provided in Terms of Value in USD.
United States Gutter Guards Market Trends and Insights
Increasing Home-Improvement & Reroofing Spend
Home improvement expenditures are projected to reach USD 524 billion in early 2026, marking a record high despite a deceleration from 2024's 7% growth peak to an estimated 5% in 2025 and 3% in 2026, according to the Harvard Joint Center for Housing Studies' Leading Indicator of Remodeling Activity (LIRA). The lock-in effect around low-rate mortgages continues to favor remodeling over moving, which keeps roofing and related exterior projects on the shortlist for near-term investment, given their property value signaling and durability benefits. Within remodels that involve roofing, new roofs delivered the highest reported homeowner satisfaction, reinforcing the upsell path for guards as contractors bundle gutter protection with reroofing jobs to prevent clogs and overflow on new systems. This acceptance aligns with steady remodeling activity following pandemic-era re-benchmarking, which points to a larger and more durable base of spending than previously captured in cyclical indicators. The United States gutter guards market benefits from this pattern through increased attachment rates when installers have scaffolding and crews on site, reducing incremental install time and contributing to higher close rates on guard add-ons. As a result, reroofing remains a critical pathway to expand micro-mesh penetration and sustain an upgrade mix across the United States gutter guards market.
Rising Frequency of Extreme Rainfall & Hurricanes
Weather volatility is amplifying demand, as 2025 featured multiple billion-dollar severe storm disasters and sustained periods of heavy rainfall that tested roof drainage capacity across major metropolitan areas. Projections for rare extreme precipitation design values in the United States indicate higher intensity events under warming, which challenge legacy gutter systems and elevate the value of debris-resistant guards that preserve flow during downpours. Physical science indicates extreme precipitation tends to increase with atmospheric moisture content, with analyses and educational materials highlighting how a warmer climate can load more moisture and intensify short-duration rainfall. The 2025 Atlantic hurricane season, while producing only 13 named storms (below the 14.4 annual average), generated 132.4 units of Accumulated Cyclone Energy (ACE), 9% above the 1991-2020 baseline, and notably spawned three Category 5 hurricanes (Erin, Humberto, Melissa), the second-highest count on record behind 2005's four, per Colorado State University's Tropical Meteorology Project verification. Insurance industry responses are materializing through wind-mitigation credits in Florida and Gulf Coast states, where homeowners installing debris-blocking gutter systems can qualify for 5-8% premium reductions on windstorm coverage, creating a financial incentive that offsets 15-20% of installation costs over a 10-year policy horizon, per Florida Office of Insurance Regulation disclosures.
High Upfront Installed Cost Versus DIY Cleaning
Premium micro-mesh systems compete with low-cost DIY guards and intermittent professional cleanings, which makes the initial outlay a barrier for price-sensitive households. Big-box retailers offer aluminum and stainless mesh options in contractor-grade packs, and those options reinforce the visible price gap that budget-conscious buyers weigh against longevity and maintenance savings. Households in older homes often face added costs for gutter replacement or fascia repair before guards can be installed, which increases the all-in ticket and forces sequencing decisions with other age-related projects. In commercial properties, longer rooflines and access requirements can add labor hours and safety controls, which further push installed costs into budget approval discussions. Clear performance warranties and independent validation for filtration and water-capture roles help address value questions, yet the payback narrative still depends on maintenance avoidance and risk reduction rather than short-term savings. These considerations can slow conversion in cohorts that prioritize near-term cash flow, which creates a persistent headwind for the United States gutter guards market even as premium adoption grows.
Other drivers and restraints analyzed in the detailed report include:
- Aging United States Housing Stock Requiring Retrofits
- Smart Rain-Harvesting Integration with Gutter Guards
- Seasonal Labor Shortages in Skilled Installers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Standard mesh and screens commanded 41.23% of the United States gutter guards market share in 2025, reflecting contractor familiarity and price accessibility for cost-driven projects that prioritize basic debris control. Integrated one-piece systems are gaining traction in new builds and whole-home exterior upgrades because they reduce retrofit complexity and come with lifetime warranties, which positions them as a premium alternative for owners who want a single-brand solution. In parallel, surface-tension covers, and foam or brush inserts retain a role in budget-conscious and DIY projects, yet their replacement cycles and performance constraints are balanced against lower upfront cost expectations. As roofers and remodelers standardize guard upsells when scaffolding is already in place, adoption spreads across more price points, which further supports the premium mix within the United States gutter guards market.
Performance credentials and brand positioning are differentiating growth within product types, as micro-mesh suppliers market durability and third-party validations to bolster trust in long-term clog prevention. Product pedigrees that include awards and lab-tested resilience help reduce skepticism among homeowners who previously deferred purchase or relied on periodic cleanings. Builders and remodelers also look for options that avoid roof warranty conflicts, favoring designs that mount to gutters or fascia without disturbing shingles or roof decking in markets where builder warranties remain active. The channel is adapting with national installers that cross-sell guards in roofing and exterior envelope projects, reinforced by private providers that expand geographic reach and unify product and install under one service umbrella. These shifts concentrate visibility around proven designs and integrated installation networks, a pattern that continues to influence product mix and margins across the United States gutter guards market.
Complete Report Scope:
- By Product Type
- Micro-Mesh Screens
- Standard Mesh & Screens
- Reverse-Curve / Surface-Tension Covers
- Brush / Bristle Inserts
- Foam Inserts
- Integrated Seamless Gutter-Guard Systems
- By Material
- Aluminum
- Stainless Steel
- Vinyl / Plastic
- Others (Foam,Copper)
- By End User
- Residential
- Commercial
- Industrial & Institutional
- By Region
- Northeast
- Midwest
- Southeast
- Southwest
- West
List of Companies Covered in this Report:
- LeafGuard
- LeafFilter North, Inc.
- Gutter Guards America
- All American Gutter Protection
- HomeCraft Gutter Protection
- MasterShield (Major Marketing Group)
- Gutterglove Inc. / Raptor
- Amerimax Building Products
- FlexxPoint, Inc.
- GutterStuff
- Gutter Helmet (EMCO)
- Klean Gutter
- Waterlock Gutter Guards
- E-Z Gutter Guard
- GutterTopper
- CopperCraft (OMNIMAX)
- Spectra Gutter Systems
- Senox Corporation
- Cornerstone Building Brands
- Gibraltar Industries
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing home-improvement & reroofing spend
- 4.2.2 Rising frequency of extreme rainfall & hurricanes
- 4.2.3 Aging United States housing stock requiring retro-fits
- 4.2.4 Growing popularity of micro-mesh premium systems
- 4.2.5 Smart rain-harvesting integration with gutter guards
- 4.2.6 Reshoring of aluminum screen manufacturing capacity
- 4.3 Market Restraints
- 4.3.1 High upfront installed cost versus DIY cleaning
- 4.3.2 Seasonal labor shortages in skilled installers
- 4.3.3 Roof-warranty conflict concerns
- 4.3.4 Emerging self-cleaning "gutter-less" roof alternatives
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Porter's Five Forces
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Suppliers
- 4.6.3 Bargaining Power of Buyers
- 4.6.4 Threat of Substitutes
- 4.6.5 Competitive Rivalry
- 4.7 Insights into the Latest Trends and Innovations in the Market
- 4.8 Insights into Recent Developments (New Product Launches, Strategic Initiatives, Investments, Partnerships, JVs, Expansion, M&As, etc.) in the Market
5 Market Size & Growth Forecasts
- 5.1 By Product Type
- 5.1.1 Micro-Mesh Screens
- 5.1.2 Standard Mesh & Screens
- 5.1.3 Reverse-Curve / Surface-Tension Covers
- 5.1.4 Brush / Bristle Inserts
- 5.1.5 Foam Inserts
- 5.1.6 Integrated Seamless Gutter-Guard Systems
- 5.2 By Material
- 5.2.1 Aluminum
- 5.2.2 Stainless Steel
- 5.2.3 Vinyl / Plastic
- 5.2.4 Others (Foam,Copper)
- 5.3 By End User
- 5.3.1 Residential
- 5.3.2 Commercial
- 5.3.3 Industrial & Institutional
- 5.4 By Region
- 5.4.1 Northeast
- 5.4.2 Midwest
- 5.4.3 Southeast
- 5.4.4 Southwest
- 5.4.5 West
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 LeafGuard
- 6.4.2 LeafFilter North, Inc.
- 6.4.3 Gutter Guards America
- 6.4.4 All American Gutter Protection
- 6.4.5 HomeCraft Gutter Protection
- 6.4.6 MasterShield (Major Marketing Group)
- 6.4.7 Gutterglove Inc. / Raptor
- 6.4.8 Amerimax Building Products
- 6.4.9 FlexxPoint, Inc.
- 6.4.10 GutterStuff
- 6.4.11 Gutter Helmet (EMCO)
- 6.4.12 Klean Gutter
- 6.4.13 Waterlock Gutter Guards
- 6.4.14 E-Z Gutter Guard
- 6.4.15 GutterTopper
- 6.4.16 CopperCraft (OMNIMAX)
- 6.4.17 Spectra Gutter Systems
- 6.4.18 Senox Corporation
- 6.4.19 Cornerstone Building Brands
- 6.4.20 Gibraltar Industries
7 Market Opportunities & Future Outlook
- 7.1 Heat-trace integrated guards for ice-dam prone zones
- 7.2 Subscription-based monitoring & cleaning-alert IoT add-ons

 雨水槽市場-2026-2032年全球市場預測
 2026年全球雨水槽市場報告
 全球雨水槽市場
 排水溝防護裝置市場 - 全球產業規模、佔有率、趨勢、機會和預測,按材料(鋁、鋼、塑膠、其他)、應用(住宅、商業)、地區和競爭細分,2020-2030 年預測全球排水溝防護罩市場