


 |
市場調查報告書
商品編碼
2124650
北美農藥包裝市場:市佔率分析、產業趨勢與統計及成長預測(2026-2031 年)North America Agricultural Chemical Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
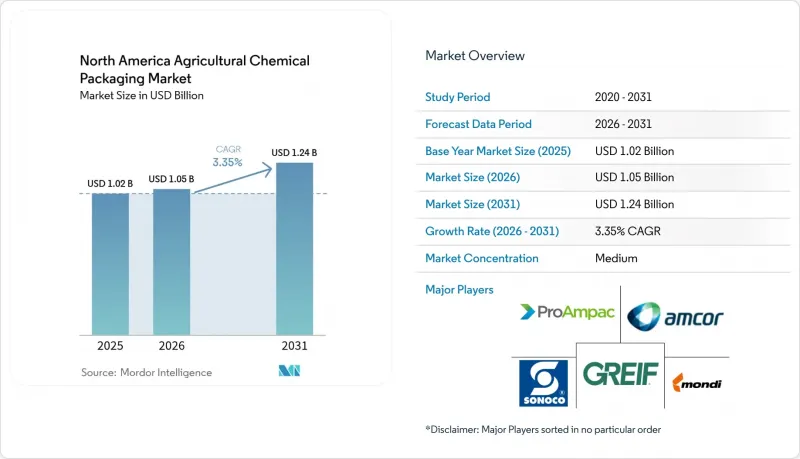
根據 Mordor Intelligence 預測,北美農藥包裝市場規模將從 2025 年的 10.2 億美元成長到 2026 年的 10.5 億美元,然後在 2031 年達到 12.4 億美元,2026 年至 2031 年的複合年成長率為 3.35%。
本報告按材料(塑膠、紙/紙板、其他)、產品類型(袋/包裝袋、容器/罐、其他)、應用(肥料、農藥、其他)、容量範圍(20公升以下、21-200公升、200公升以上)和地區(美國、加拿大、墨西哥)進行細分。市場預測以美元(USD)計價。
北美農藥包裝市場的趨勢與洞察
緩釋膜和水溶性膜的廣泛應用
緩釋包裝透過延長活性成分的有效時間並減少人工投入,滿足了北美大型農場對營運效率的需求。水溶性薄膜可在噴霧罐中完全溶解,免去了容器處理的麻煩,提高了安全性和田間作業效率。這對於除草劑和殺菌劑的施用尤其有利,因為施用精度直接影響產量和法規遵循。隨著農民更傾向於選擇與GPS導航系統和可變噴灑量地圖相容的包裝,精密農業軟體的應用正在加速普及。因此,包裝正從被動的容器轉變為融入農場管理工作流程的數位化整合噴灑組件。
以永續性為驅動力,轉型為可回收和生物基材料。
美國五個州的「生產者延伸責任制」(EPR)法規為含有回收和可再生資源的材料提供環保定價激勵,鼓勵加工商轉向聚乳酸(PLA)、聚羥基烷酯(PHA)和其他生物基樹脂。隨著商業規模工廠(例如Citroniq在內布拉斯加州投資1,200萬美元建設的聚丙烯生產線)的供應量增加,成本溢價正在下降。品牌永續性承諾也帶來了下行壓力,碳足跡揭露和可回收性已成為生產商和農業用品經銷商的重要採購標準。目前,研發重點在於實現與傳統樹脂相當的防潮、防氧和防紫外線性能,從而使對穩定性要求較高的除草劑和生技藥品即使在多季儲存期間也能保持穩定。
聯合國和美國運輸部正在收緊危險品管制條例。
對桶裝和IBC(中型散裝容器)性能測試的加強,導致每條產品線的認證成本增加5萬至10萬美元,小規模加工商難以承擔這筆費用。不合格庫存的逐步淘汰正在擾亂供應鏈,並加速產業重組,因為一些小眾供應商正尋求被擁有成熟的合格評定實驗室和測試預算的公司收購。
細分市場分析
由於塑膠具有優異的耐化學性和成本績效,預計到2025年,塑膠將佔北美農業化學品包裝市場64.65%的佔有率。儘管該細分市場的複合年成長率仍然較為溫和,但生物基材料和複合材料的成長率高達4.35%,這主要得益於生產者延伸責任制(EPR)獎勵和農場層面的永續性舉措。複合層壓材料兼具機械強度及減薄潛力,可在不影響抗穿刺性的前提下,減少高達15%的聚合物用量。源自非食用生質能的生物基聚丙烯正日益滿足防潮和防氧標準,並逐漸成為高價特種除草劑和生技藥品的理想包裝材料。
市場需求日益多元化。例如,化學肥料包裝採用堅固耐用的高密度聚乙烯(HDPE)瓶以提高成本效益,而活性微生物產品則需要具有除氧功能的多層結構。因此,加工商正在拓展其材料組合,以應對政策變革和客戶群結構轉變的影響。在北美農藥包裝市場,生物基包裝目前仍屬於小眾市場,但隨著採購中永續性評估標準的標準化,先行進入者在產品規格方面正獲得競爭優勢。
到2025年,袋裝和包裝袋將佔銷售額的43.92%。這主要得益於它們與現有填充線的兼容性、便於扁平運輸以及與水溶性和緩釋薄膜的兼容性。然而,隨著散裝中間商整合貨量以降低運輸和人事費用,預計到2031年,IBC(中型散裝容器)將以4.67%的複合年成長率實現最高成長。隨著配備2D碼板和低功耗感測器的數位化IBC的出現,容器正從單純的靜態儲存轉變為分銷網路中活躍且可見的節點。
軟性中型散貨箱(FIBC)和硬質組合式噸桶的使用量正在增加,尤其是在顆粒狀肥料領域,因為托盤堆疊時的穩定性至關重要。同時,包裝袋也在不斷發展,採用多層結構,並添加表面活性劑以提高其在噴霧罐中的分散性。在北美農藥包裝市場,由於包裝袋在精準計量方面發揮重要作用,因此仍佔據相當大的佔有率。而貨櫃(IBC)共享專案提供的基於服務的經濟效益,正吸引那些尋求減少廢棄物和成本可預測性的大型零售商。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 緩釋製劑和水溶性薄膜的廣泛應用
- 向可回收和生物基形式轉型,以永續性為驅動力。
- 精密農業對小體積、阻隔性包裝的需求
- 主要經銷商的散裝容器回收計劃
- 數位化可追溯包裝,用於管理和合規
- 對北美樹脂和加工能力的投資
- 市場限制因素
- 聯合國和美國運輸部正在收緊對危險物品的監管。
- 聚合物和金屬原料價格波動劇烈
- 農民反對包裝廢棄物處理成本
- 2023年起經銷商庫存削減週期
- 產業價值鏈分析
- 波特五力分析
- 宏觀經濟因素對市場的影響
- 監理情勢
- 技術展望
第5章 市場規模與成長預測
- 材料類型
- 塑膠
- 紙張和紙板
- 金屬
- 複合材料和生物基材料
- 依產品類型
- 袋子和小袋
- 容器和罐頭
- 中型散貨箱(IBC)
- 鼓
- 其他產品類型
- 按應用程式類型
- 肥料
- 殺蟲劑
- 除草劑
- 生技藥品及植物生長調節劑
- 按生產能力範圍分類
- 20公升或以下
- 21~200 L
- 超過200公升
- 國家
- 美國
- 加拿大
- 墨西哥
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Amcor plc
- Greif Inc.
- Mondi plc
- Sonoco Products Company
- ProAmpac LLC
- LC Packaging International BV
- Mauser Packaging Solutions Holding Co.
- Silgan Holdings Inc.
- NNZ BV
- International Paper Company
- Smurfit WestRock
- Sealed Air Corporation
- Uflex Limited
- Constantia Flexibles Group GmbH
- Schutz GmbH & Co. KGaA
- Hoover CS LLC
- FlexPak Services LLC
- Intertape Polymer Group Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the North America agricultural chemical packaging market size is expected to grow from USD 1.02 billion in 2025 to USD 1.05 billion in 2026 and is forecast to reach USD 1.24 billion by 2031 at 3.35% CAGR over 2026-2031.
This report is Segmented by Material Type (Plastic, Paper and Paperboard, and More), Product Type (Bags and Pouches, Containers and Cans, and More), Application Type (Fertilizers, Pesticides, and More), Capacity Range (<= 20 L, 21 - 200 L, > 200 L), and Geography (United States, Canada, and Mexico). The Market Forecasts are Provided in Terms of Value (USD).
North America Agricultural Chemical Packaging Market Trends and Insights
Growth in Controlled-Release and Water-Soluble Film Adoption
Controlled-release packaging extends active ingredient efficacy and lowers labor inputs, answering the operational efficiency needs of large North American farms. Water-soluble films dissolve entirely in spray tanks and remove container-disposal headaches, improving safety and field productivity. Herbicide and fungicide applications benefit most because dosing precision directly affects yields and regulatory compliance. Precision-farming software accelerates uptake, as farmers favor packs that align with GPS-guided systems and variable-rate maps. As a result, packaging shifts from passive containment to a digitally integrated delivery component embedded in farm management workflows.
Sustainability-Driven Shift to Recyclable and Bio-Based Formats
EPR rules in five U.S. states impose eco-modulated fees that reward materials with recycled or renewable content, nudging converters toward polylactic acid (PLA), polyhydroxyalkanoate (PHA), and other bio-based resins. Cost premiums are narrowing as commercial-scale plants, such as Citroniq's USD 12 million polypropylene line in Nebraska, increase supply. Brand sustainability pledges add downstream pressure, making carbon-footprint disclosure and recyclability critical purchase criteria for growers and input distributors. R&D now focuses on matching the moisture, oxygen, and UV barriers of conventional resins so that sensitive herbicides and biologicals remain stable throughout multi-season storage.
Tightening UN and DOT Hazardous-Goods Regulations
Enhanced performance tests for drums and IBCs raise certification expenses by USD 50,000-100,000 per product line, a burden that smaller converters struggle to absorb. Inventory phase-outs of non-compliant stock disrupt supply chains and accelerate consolidation as niche suppliers seek acquisition by firms with established compliance laboratories and testing budgets.
Other drivers and restraints analyzed in the detailed report include:
- Precision-Farming Demand for Smaller-Dose, High-Barrier Packs
- Bulk-Container Re-usability Programs by Large Distributors
- Volatile Polymer and Metal Feedstock Prices
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Plastic captured 64.65% of the North America agricultural chemical packaging market in 2025 owing to its high chemical resistance and favorable cost-to-performance ratio. The segment's CAGR remains modest as bio-based and composite substrates outpace at 4.35%, propelled by EPR incentives and farm-level sustainability pledges. Composite laminates marry mechanical strength with downgauging potential, cutting polymer mass by up to 15% without forfeiting puncture resistance. Bio-based polypropylene sourced from non-food biomass increasingly meets moisture and oxygen protection criteria, positioning it for premium-priced specialty herbicide and biological packs.
Demand heterogeneity is widening: fertilizers rely on rugged HDPE jugs for cost efficiency, whereas living microbial products require oxygen-scavenging multilayers. Consequently, converters diversify material portfolios to hedge against policy changes and customer mix volatility. The North America agricultural chemical packaging market size devoted to bio-based formats is still niche, but early movers gain specification lock-ins as sustainability scorecards become standard in procurement.
Bags and pouches delivered 43.92% revenue in 2025 because they fit existing filling lines, ship flat, and support water-soluble or controlled-release films. Yet IBCs register the highest 4.67% CAGR through 2031 as bulk intermediaries consolidate volumes to trim freight and labor. Digital-ready IBCs, fitted with QR plates or low-power sensors, shift containers from static storage to active visibility nodes in distributor networks.
Flexible intermediate bulk containers (FIBCs) and rigid combo totes broaden applications, especially for granular fertilizers where pallet-layer stability matters. Conversely, pouches evolve toward multilayer formats with built-in surfactants that improve spray-tank dispersion. The North America agricultural chemical packaging market share of pouches stays meaningful due to their role in precision dosing, yet the service-based economics of pooled IBC programs attract large retailers seeking waste-reduction credits and cost predictability.
Complete Report Scope:
- By Material Type
- Plastic
- Paper and Paperboard
- Metal
- Composite and Bio-Based Materials
- By Product Type
- Bags and Pouches
- Containers and Cans
- Intermediate Bulk Containers (IBCs)
- Drums
- Other Product Types
- By Application Type
- Fertilizers
- Pesticides
- Herbicides
- Biologicals and Plant Growth Regulators
- By Capacity Range
- <= 20 L
- 21 - 200 L
- > 200 L
- By Country
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- Amcor plc
- Greif Inc.
- Mondi plc
- Sonoco Products Company
- ProAmpac LLC
- LC Packaging International BV
- Mauser Packaging Solutions Holding Co.
- Silgan Holdings Inc.
- NNZ B.V.
- International Paper Company
- Smurfit WestRock
- Sealed Air Corporation
- Uflex Limited
- Constantia Flexibles Group GmbH
- Schutz GmbH & Co. KGaA
- Hoover CS LLC
- FlexPak Services LLC
- Intertape Polymer Group Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growth in Controlled-Release and Water-Soluble Film Adoption
- 4.2.2 Sustainability-Driven Shift to Recyclable and Bio-Based Formats
- 4.2.3 Precision-Farming Demand for Smaller-Dose, High-Barrier Packs
- 4.2.4 Bulk-Container Re-usability Programs by Large Distributors
- 4.2.5 Digitally Traceable Packaging for Stewardship and Compliance
- 4.2.6 Investments in North-American Resin and Conversion Capacity
- 4.3 Market Restraints
- 4.3.1 Tightening UN/DOT Hazardous-Goods Regulations
- 4.3.2 Volatile Polymer and Metal Feedstock Prices
- 4.3.3 Farmer Push-Back on Packaging Waste Fees
- 4.3.4 Distributor Destocking Cycles Post-2023
- 4.4 Industry Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Intensity of Competitive Rivalry
- 4.5.5 Threat of Substitute Products
- 4.6 The Impact of Macroeconomic Factors on the Market
- 4.7 Regulatory Landscape
- 4.8 Technological Outlook
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material Type
- 5.1.1 Plastic
- 5.1.2 Paper and Paperboard
- 5.1.3 Metal
- 5.1.4 Composite and Bio-Based Materials
- 5.2 By Product Type
- 5.2.1 Bags and Pouches
- 5.2.2 Containers and Cans
- 5.2.3 Intermediate Bulk Containers (IBCs)
- 5.2.4 Drums
- 5.2.5 Other Product Types
- 5.3 By Application Type
- 5.3.1 Fertilizers
- 5.3.2 Pesticides
- 5.3.3 Herbicides
- 5.3.4 Biologicals and Plant Growth Regulators
- 5.4 By Capacity Range
- 5.4.1 <= 20 L
- 5.4.2 21 - 200 L
- 5.4.3 > 200 L
- 5.5 By Country
- 5.5.1 United States
- 5.5.2 Canada
- 5.5.3 Mexico
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 Amcor plc
- 6.4.2 Greif Inc.
- 6.4.3 Mondi plc
- 6.4.4 Sonoco Products Company
- 6.4.5 ProAmpac LLC
- 6.4.6 LC Packaging International BV
- 6.4.7 Mauser Packaging Solutions Holding Co.
- 6.4.8 Silgan Holdings Inc.
- 6.4.9 NNZ B.V.
- 6.4.10 International Paper Company
- 6.4.11 Smurfit WestRock
- 6.4.12 Sealed Air Corporation
- 6.4.13 Uflex Limited
- 6.4.14 Constantia Flexibles Group GmbH
- 6.4.15 Schutz GmbH & Co. KGaA
- 6.4.16 Hoover CS LLC
- 6.4.17 FlexPak Services LLC
- 6.4.18 Intertape Polymer Group Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

