


 |
市場調查報告書
商品編碼
2124644
東南亞廣告市場:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Southeast Asia Advertising - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
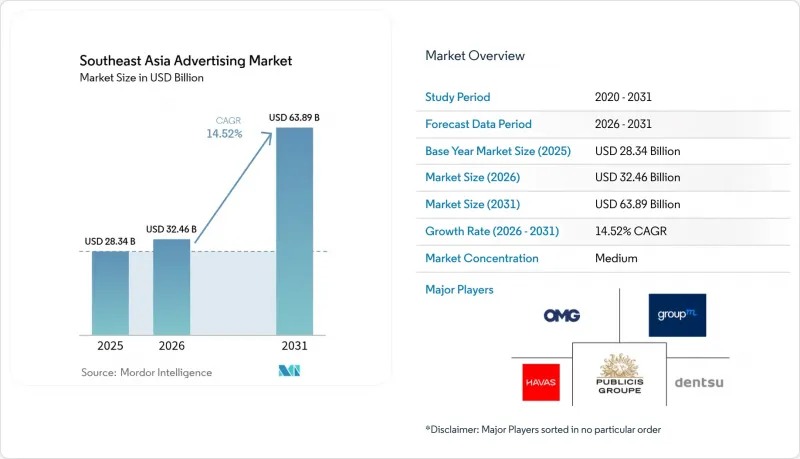
據 Mordor Intelligence 稱,東南亞廣告市場在 2025 年的價值為 283.4 億美元,預計到 2031 年將達到 638.9 億美元,而 2026 年為 324.6 億美元,預測期(2026-2031 年)的複合成長率為 14.52%。
本報告按通路類型(傳統媒體和數位媒體)、廣告媒介(電視、數位廣告、印刷品等)、交易類型(程序化和非程序化)、終端用戶行業(快速消費品、零售/電子商務、汽車、銀行、金融服務和保險、電信/IT等)以及國家/地區進行細分。市場預測以美元(USD)計價。
東南亞廣告市場趨勢與洞察
行動寬頻普及率不斷上升
行動連線正在重塑東南亞廣告市場的覆蓋範圍。 GSMA預測,到2030年,月數據使用量將成長四倍以上,這將為先前受頻寬限制的高位元率影片和身臨其境型內容格式鋪平道路。由於印尼的固定寬頻普及率不足20%,行動網路已成為預設的數位入口,廣告商也擴大採用基於位置的定向投放和「影片優先」的創新。通訊速度的提升也提高了程式化平台可用的數據質量,使即時互動指標成為購買和最佳化廣告資源的主要機制。
程序化戶外數位廣告的普及速度正在加快。
如今,數位廣告看板能夠根據即時天氣和交通資訊產生動態廣告。 2024年7月,Moving Walls與GroupM簽署協議,使馬來西亞的廣告主能夠獲得檢驗的數位戶外廣告資源,從而緩解了先前對廣告可見度的擔憂。在新加坡和曼谷等人口稠密的城市,演算法排期功能使品牌能夠根據一天中的時間、交通路線或從行動裝置捕捉到的市場行為模式來輪換創新。諸如戶外廣告開放測量組織(Open Measurement in Out-of-Home Group)等標準化機構發布了開放原始碼的展示框架,使廣告主能夠獲得他們期望從線上管道獲得的課責。
出版商庫存的高級碎片化
馬來西亞擁有超過300家廣告看板所有者,導致廣告主只能以零散的方式拼湊宣傳活動。 CtrlShift的AMP市場目前整合了七家主要出版商的廣告資源,但規模仍然有限。分散在印尼和菲律賓的小規模數位出版商加劇了這個問題,他們缺乏通用的廣告科技堆疊和定價透明度。這種分散化推高了交易成本,阻礙了新進者,並減緩了東南亞廣告市場程式化廣告支出的成長速度。
細分市場分析
2025年,傳統通路在東南亞廣告市場仍佔據60.12%的佔有率,主要得益於農村和老年族群中電視觀看率的持續成長。然而,這一領域的成長速度與數位媒體15.05%的複合年成長率形成鮮明對比,顯示智慧型手機和價格親民的資料方案正在推動消費模式發生不可逆轉的轉變。數位媒體的快速成長歸功於程式化採購的高效性和精準定位,而這些是電視或紙媒無法實現的。 2024年,泰國數位廣告支出超過了電視廣告支出(45%對35%),反映出消費者行為正顯著轉向線上影片和社群媒體。
跨境電商宣傳活動需要即時在地化,而這只有演算法管道才能提供,這進一步加速了數位轉型。同時,在高階受眾更注重沉浸式和品牌安全感的大都會圈,電影院和傳統戶外廣告形式仍扮演著至關重要的角色。然而,績效指標、歸因分析和受眾數據的差異正促使預算大幅轉向數位化,而這種回饋循環正在重塑東南亞廣告市場的支出結構,並將在預測期內持續影響市場走向。
預計到2025年,電視將佔據29.35%的市場佔有率,繼續保持其作為最盈利單一媒體的地位。這不僅反映了傳統的收視習慣,也體現了電視在觸達大眾方面的高效性。然而,數位戶外廣告(DOOH)的成長勢頭最為強勁,年複合成長率(CAGR)高達15.72%,這得益於螢幕成本的降低、5G網路連接的普及以及標準化的曝光聚合框架。廣告商非常重視DOOH能夠根據一天中的不同時間更新創新,並根據天氣和交通堵塞等本地因素投放廣告。
傳統紙媒和廣播電台仍保持著一定的市場吸引力,例如報紙插頁廣告針對老年讀者,以及高峰時段堵塞路段的廣播廣告,但隨著衡量指標不確定性的增加,它們的市場佔有率正在萎縮。電影院提供優質的廣告位,可以充分利用熱門影片的上映,但影院容量限制了其成長。數位廣告,包括搜尋、社群媒體廣告、展示廣告和OTT影片廣告,憑藉更完善的歸因模型和人工智慧驅動的創新測試,正在最佳化品牌在東南亞廣告市場的營運績效,並持續蠶食傳統廣播廣告的預算。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 行動寬頻普及率不斷上升
- 程序化戶外數位廣告的普及速度正在加快。
- 政府主導的「數位化優先」扶持中小企業的措施
- 利用人工智慧最佳化動態創新
- 超應用程式廣告生態系統(Grab、Gojek)
- 跨境電子商務的蓬勃發展
- 市場限制因素
- 出版商庫存的高級碎片化
- 機構回扣做法不透明
- 嚴格的個人資料法規(PDPA 的各種變體)
- 數位戶外廣告缺乏衡量標準
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 宏觀經濟因素對市場的影響
第5章 市場規模與成長預測
- 按頻道類型
- 傳統媒體
- 數位媒體
- 透過廣告媒介
- 電視機
- 數位廣告
- 印刷品
- 收音機
- 電影院
- 戶外廣告(OOH)
- 數位戶外廣告 (DOOH)
- 按交易類型
- 程式化
- 非程式化
- 按最終用戶行業分類
- 日常消費品(FMCG)
- 零售與電子商務
- 車
- BFSI
- 通訊/IT
- 醫療和製藥
- 觀光觀光
- 其他終端用戶產業
- 國家
- 新加坡
- 馬來西亞
- 印尼
- 泰國
- 越南
- 菲律賓
- 其他國家(柬埔寨、寮國、緬甸、汶萊、東帝汶)
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Dentsu International Asia Pte. Ltd.
- GroupM Asia Pacific Holdings Ltd.
- Omnicom Media Group Asia Pacific Pte. Ltd.
- Publicis Groupe SA
- Havas Media Asia Pacific Pte. Ltd.
- IPG Mediabrands Singapore Pte. Ltd.
- JCDecaux Singapore Pte. Ltd.
- Clear Channel Singapore Pte. Ltd.
- XCO Media Pte. Ltd.
- Mediacorp OOH Media Pte. Ltd.
- Moove Media Pte. Ltd.
- SPH Media Limited(SPHMBO)
- Moving Walls Sdn. Bhd.
- Spectrum Outdoor Sdn. Bhd.
- TAC Media Sdn. Bhd.
- VGI Global Media Public Co. Ltd.
- Sea Digital Media Pte. Ltd.
- AdColony(Digital Turbine Singapore Pte. Ltd.)
- GrabAds Holdings Pte. Ltd.
- Gojek Ads(PT Dompet Anak Bangsa)
- Kantar Media Singapore Pte. Ltd.
- Innity Corporation Berhad
第7章 市場機會與未來展望
According to Mordor Intelligence, the south East Asia advertising market size was valued at USD 28.34 billion in 2025 and estimated to grow from USD 32.46 billion in 2026 to reach USD 63.89 billion by 2031, at a CAGR of 14.52% during the forecast period (2026-2031).
This report is Segmented by Channel Type (Traditional Media and Digital Media), Advertising Medium (Television, Digital Advertising, Print, and More), Transaction Type (Programmatic and Non-Programmatic), End-User Industry (FMCG, Retail and E-Commerce, Automotive, BFSI, Telecom and IT, and More), and Country. The Market Forecasts are Provided in Terms of Value (USD).
Southeast Asia Advertising Market Trends and Insights
Rising Mobile Broadband Penetration
Mobile connectivity is redefining ad reach across the Southeast Asia Advertising market. GSMA projects that monthly data usage will surge more than fourfold by 2030, opening space for high-bit-rate video and immersive formats that were previously bandwidth-constrained. With Indonesia's fixed broadband penetration below 20%, mobile is the default digital gateway, prompting advertisers to adopt location-based targeting and video-first creative. Faster speeds also enrich the data available to programmatic platforms, turning real-time engagement metrics into the primary mechanism for buying and optimizing inventory.
Accelerated Uptake of Programmatic DOOH
Digital billboards now stream dynamic ads shaped by live weather or traffic feeds. A July 2024 deal between Moving Walls and GroupM gave Malaysian buyers verified DOOH inventory, mitigating historical viewability doubts. In dense Singapore and Bangkok, algorithmic scheduling lets brands rotate creative by daypart, congested routes, or in-market behaviors pulled from mobile devices. Standard-setting bodies such as the Open Measurement in Out-of-Home Group released open-source impression frameworks, bringing the accountability that advertisers expect from online channels.
High Fragmentation of Publisher Inventory
Malaysia counts more than 300 billboard owners, forcing buyers to stitch together campaigns piecemeal. CtrlShift's AMP marketplace now aggregates inventory from seven major publishers, but scale remains limited. Smaller digital publishers across Indonesia and the Philippines compound the problem, lacking common ad-tech stacks or transparency in pricing. Fragmentation raises transaction costs, deters new entrants, and slows the growth trajectory of programmatic spend within the Southeast Asia Advertising market.
Other drivers and restraints analyzed in the detailed report include:
- Government-Led Digital-First SME Incentives
- AI-Driven Dynamic Creative Optimization
- Opaque Agency Rebate Practices
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Traditional channels retained a 60.12% share of the South East Asia Advertising market in 2025, buoyed by entrenched TV viewership among rural and older audiences. Yet the segment's modest growth contrasts with digital media's 15.05% CAGR, signaling an irreversible consumption pivot fueled by smartphones and cheaper data plans. Rapid gains stem from programmatic buying efficiencies and granular targeting that television or print cannot match. Thailand marked a pivotal moment in 2024 when digital ad spend surpassed TV, taking 45% versus 35%, underlining consumer migration to online video and social feeds.
Digital's advance is accelerated further by cross-border e-commerce campaigns demanding real-time localization, a capability only algorithmic channels can deliver. Meanwhile, cinema and classic outdoor formats remain relevant in dense metros, where premium audiences value immersive, brand-safe settings. Still, the differential in performance metrics, attribution, and audience data tilts budgets heavily toward digital, reinforcing a feedback loop that reshapes the spending mix of the Southeast Asia Advertising market over the forecast period.
Television's 29.35% stake in 2025 still positions it as the most lucrative single medium, reflecting both legacy habit and mass-reach efficiency. However, Digital Out-of-Home exhibits the highest trajectory at 15.72% CAGR, aided by falling screen costs, 5G connectivity, and standardized impression counting frameworks. Advertisers appreciate DOOH's ability to refresh creative by daypart or trigger ads based on localized stimuli such as weather or traffic congestion.
Traditional print and radio keep niche appeal, newspaper inserts among older readers, and commuter-time radio ads on high-congestion routes, but their share contracts as measurement gaps widen. Cinema capitalizes on blockbuster releases for premium placements, yet venue capacity caps growth. Digital advertising covering search, social, display, and OTT video continues to siphon dollars from broadcast budgets, riding on better attribution models and AI-enhanced creative testing that optimize in-flight performance for brands across the Southeast Asia Advertising market.
Complete Report Scope:
- By Channel Type
- Traditional Media
- Digital Media
- By Advertising Medium
- Television
- Digital Advertising
- Radio
- Cinema
- Out-of-Home (OOH)
- Digital OOH (DOOH)
- By Transaction Type
- Programmatic
- Non-Programmatic
- By End-User Industry
- Fast-Moving Consumer Goods (FMCG)
- Retail and E-commerce
- Automotive
- BFSI
- Telecom and IT
- Healthcare and Pharma
- Travel and Tourism
- Other End-User Industries
- By Country
- Singapore
- Malaysia
- Indonesia
- Thailand
- Vietnam
- Philippines
- Other Countries (Cambodia, Laos, Myanmar, Brunei, Timor-Leste)
List of Companies Covered in this Report:
- Dentsu International Asia Pte. Ltd.
- GroupM Asia Pacific Holdings Ltd.
- Omnicom Media Group Asia Pacific Pte. Ltd.
- Publicis Groupe SA
- Havas Media Asia Pacific Pte. Ltd.
- IPG Mediabrands Singapore Pte. Ltd.
- JCDecaux Singapore Pte. Ltd.
- Clear Channel Singapore Pte. Ltd.
- XCO Media Pte. Ltd.
- Mediacorp OOH Media Pte. Ltd.
- Moove Media Pte. Ltd.
- SPH Media Limited (SPHMBO)
- Moving Walls Sdn. Bhd.
- Spectrum Outdoor Sdn. Bhd.
- TAC Media Sdn. Bhd.
- VGI Global Media Public Co. Ltd.
- Sea Digital Media Pte. Ltd.
- AdColony (Digital Turbine Singapore Pte. Ltd.)
- GrabAds Holdings Pte. Ltd.
- Gojek Ads (PT Dompet Anak Bangsa)
- Kantar Media Singapore Pte. Ltd.
- Innity Corporation Berhad
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising mobile broadband penetration
- 4.2.2 Accelerated uptake of programmatic DOOH
- 4.2.3 Government-led digital-first SME incentives
- 4.2.4 AI-driven dynamic creative optimisation
- 4.2.5 Super-app advertising ecosystems (Grab, Gojek)
- 4.2.6 Cross-border e-commerce boom
- 4.3 Market Restraints
- 4.3.1 High fragmentation of publisher inventory
- 4.3.2 Opaque agency rebate practices
- 4.3.3 Stringent personal-data regulations (PDPA variants)
- 4.3.4 Limited measurement standards for DOOH
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Buyers
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Channel Type
- 5.1.1 Traditional Media
- 5.1.2 Digital Media
- 5.2 By Advertising Medium
- 5.2.1 Television
- 5.2.2 Digital Advertising
- 5.2.3 Print
- 5.2.4 Radio
- 5.2.5 Cinema
- 5.2.6 Out-of-Home (OOH)
- 5.2.7 Digital OOH (DOOH)
- 5.3 By Transaction Type
- 5.3.1 Programmatic
- 5.3.2 Non-Programmatic
- 5.4 By End-User Industry
- 5.4.1 Fast-Moving Consumer Goods (FMCG)
- 5.4.2 Retail and E-commerce
- 5.4.3 Automotive
- 5.4.4 BFSI
- 5.4.5 Telecom and IT
- 5.4.6 Healthcare and Pharma
- 5.4.7 Travel and Tourism
- 5.4.8 Other End-User Industries
- 5.5 By Country
- 5.5.1 Singapore
- 5.5.2 Malaysia
- 5.5.3 Indonesia
- 5.5.4 Thailand
- 5.5.5 Vietnam
- 5.5.6 Philippines
- 5.5.7 Other Countries (Cambodia, Laos, Myanmar, Brunei, Timor-Leste)
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Dentsu International Asia Pte. Ltd.
- 6.4.2 GroupM Asia Pacific Holdings Ltd.
- 6.4.3 Omnicom Media Group Asia Pacific Pte. Ltd.
- 6.4.4 Publicis Groupe SA
- 6.4.5 Havas Media Asia Pacific Pte. Ltd.
- 6.4.6 IPG Mediabrands Singapore Pte. Ltd.
- 6.4.7 JCDecaux Singapore Pte. Ltd.
- 6.4.8 Clear Channel Singapore Pte. Ltd.
- 6.4.9 XCO Media Pte. Ltd.
- 6.4.10 Mediacorp OOH Media Pte. Ltd.
- 6.4.11 Moove Media Pte. Ltd.
- 6.4.12 SPH Media Limited (SPHMBO)
- 6.4.13 Moving Walls Sdn. Bhd.
- 6.4.14 Spectrum Outdoor Sdn. Bhd.
- 6.4.15 TAC Media Sdn. Bhd.
- 6.4.16 VGI Global Media Public Co. Ltd.
- 6.4.17 Sea Digital Media Pte. Ltd.
- 6.4.18 AdColony (Digital Turbine Singapore Pte. Ltd.)
- 6.4.19 GrabAds Holdings Pte. Ltd.
- 6.4.20 Gojek Ads (PT Dompet Anak Bangsa)
- 6.4.21 Kantar Media Singapore Pte. Ltd.
- 6.4.22 Innity Corporation Berhad
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


