


 |
市場調查報告書
商品編碼
2124362
終端用戶計算:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)End User Computing - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
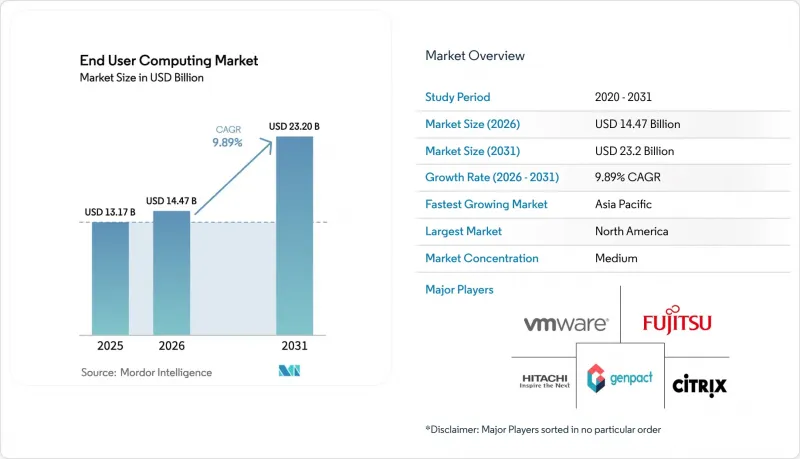
據 Mordor Intelligence 稱,2025 年終端用戶計算市場價值為 131.7 億美元,預計到 2031 年將達到 232 億美元,而 2026 年為 144.7 億美元,預測期(2026-2031 年)的複合年成長率為 9.89%。
本報告按產品類型(例如,虛擬桌面基礎架構)、組織規模(例如,大型企業)、部署模式(本地部署、雲端部署、混合部署)、最終用戶產業(例如,IT和電信、銀行、金融服務和保險)、交付模式(例如,虛擬桌面基礎架構)以及地區進行細分。市場預測以美元計價。
全球終端用戶運算市場趨勢與洞察
透過數位化工作空間提高員工生產力的舉措
企業正透過將虛擬桌面、協作套件和人工智慧助理整合到單一的數位化工作空間中,重新定義生產力的概念。工作場所成熟度較高的企業報告稱,由於能夠更快地存取資源、使用自助服務應用程式和統一的安全控制,員工體驗相關積極指標提升了 57.8%。微軟的早期現場數據顯示,人工智慧助理每月可為每位員工節省約 10 小時,從而顯著提高生產力。因此,無縫的設備切換和自動化工作流程減少了摩擦和倦怠,進而顯著提升了創新能力、包容性和員工福祉。
雲端桌面和應用程式虛擬化的普及應用
基於使用量的桌面託管正迅速普及,因為它無需資本投入,並將部署時間從數月縮短至數天。在受訪的組織中,26% 的組織已全面部署 Azure 虛擬桌面,另有 58% 的組織計劃在未來兩年內實施。這主要得益於其基於策略的擴展、付費使用制以及與 Microsoft 365 的原生整合。醫療保健機構已充分展現了其優勢。透過瀏覽器存取的桌面,使用者只需不到一分鐘即可登錄,從而減少了 IT 相關等待時間,使醫護人員能夠騰出更多時間服務病患。
將最終用戶計算 (EUC) 與舊有應用程式和基礎設施整合的複雜性
銀行、醫院和政府機構仍然依賴與特定作業系統版本、硬編碼的驅動器映射或透過串列連接的周邊設備綁定的複雜型用戶端應用程式。虛擬桌面必須複製這些依賴關係,同時也要確保關鍵任務工作流程的毫秒級回應時間。這為整合專案增加了中間件、API 和並行測試環境,導致工期延長和成本增加。糟糕的變更管理會進一步損害投資報酬率。 73% 的員工在沒有接受系統培訓的情況下遷移到數位化工作空間,導致工作投入度下降,並面臨專案回溯的風險。企業正在透過分階段遷移工作負載、將單體系統重構為模組化服務以及實施使用者體驗分析來及早發現部署瓶頸,從而緩解這些延誤。
細分市場分析
該解決方案在2025年仍保持終端用戶計算市場60.45%的佔有率。這得歸功於成熟的虛擬桌面基礎架構(VDI)平台、裝置管理套件和軟體資產管理工具,這些工具共同創造了約80億美元的經常性收入。供應商正在使用整合式主機編配終端、應用程式和安全,從而簡化了對數千個資產的合規性審計。目前,成長主要集中在託管服務領域,複合年成長率(CAGR)為10.05%。這是因為企業更傾向於基於結果的契約,將補丁管理、擴展和體驗監控等工作委託給專家。
託管服務供應商正在整合人工智慧驅動的可觀測性和自癒功能,使客戶能夠從被動的工單處理模式轉變為主動的最佳化模式。例如,醫療產業的客戶正在採用設備即服務 (DaaS) 套餐,將資本支出 (Capex) 轉化為可預測的營運成本 (OpEx),並提供預先配置的臨床工作站,續約週期為 36 個月,從而將服務台諮詢量減少兩位數。
到2025年,大型企業將佔據終端用戶運算市場45.85%的佔有率,它們依靠客製化整合、零信任安全網路和全球聯合身分來保護數萬用戶。雖然同步授權和內部專業知識能夠降低單一使用者營運成本,但硬體更新需求和人工智慧升級週期卻需要持續的再投資。
同時,中小企業 (SME) 正以 10.25% 的複合年成長率快速成長,因為雲端原生桌面無需資料中心空間和專業人員。基於瀏覽器的桌面工作區可在 48 小時內部署完畢,並配備自動擴充、備份和合規性範本。對於許多中小企業而言,Windows 10 停止支援促使他們避免硬體支出,直接遷移到雲端桌面,從而即時存取與 Windows 11 相容的環境。
區域分析
預計到2025年,亞太地區將佔據終端用戶計算市場62.40%的佔有率,並在2026年至2031年全部區域保持10.72%的複合年成長率。根據Zoho的研究,亞太地區企業的數位化工作場所成熟度得分達到66.35%,比全球平均高出5個百分點,其中76%的企業達到「高階」水準。人工智慧工具(54%)和團隊聊天(72%)的普及率清楚地體現了「行動優先」的理念,而5G的穩定部署也為邊緣增強型虛擬桌面創造了有利環境。
在北美,虛擬桌面基礎架構 (VDI) 環境在受監管行業中已相當成熟,引領了人工智慧 (AI) 輔助駕駛技術的早期應用,每月可為每位使用者節省約 10 小時的工作時間。隨著 Windows 10 停止支持,一波即時升級浪潮湧現,重點轉向現代化的終端管理和桌面即服務 (DaaS)。歐洲也呈現類似的趨勢,但由於 GDPR 法規的嚴格要求,跨國公司正轉向混合部署模式,以平衡本地資料保存和全球雲端擴展。
在中東、非洲和拉丁美洲等新興市場,雲端桌面被視為跨越傳統基礎架構的絕佳機會。使用模式可根據預算限制進行客製化,與電信運營商的邊緣整合預計將在沉浸式現場維護和遠端援助場景中實現低於 20 毫秒的延遲。各國政府正將資料在地化規則合法化,並推廣可與全球平台互通的區域雲區和自主身臨其境型桌面基礎架構 (VDI) 堆疊。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場概覽
- 市場概覽
- 市場促進因素
- 透過數位化工作空間提高員工生產力的舉措
- 雲端桌面和應用程式虛擬化的普及應用
- 自帶設備辦公室 (BYOD) 政策的日益普及以及越來越多的行動工作者需要統一的終端管理。
- Windows 10 停止支援正在加速企業 PC 的更換週期。
- 人工智慧終端的出現使得在設備上執行生成式人工智慧工作負載成為可能。
- 電信業者與邊緣雲端供應商之間的合作,為現場 AR/VR 應用實現了超低延遲的 EUC。
- 市場限制因素
- 將最終用戶計算 (EUC) 與舊有應用程式和基礎設施整合的複雜性
- 遷移到 VDI 和 DaaS 的初始實施成本很高。
- 由於供應商合併(例如 VMware 出售其 EUC 業務),許可方面存在不確定性。
- 對資料主權的擔憂阻礙了雲端運算在終端用戶運算中的全面應用。
- 宏觀經濟因素的影響
- 產業價值/價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 依產品類型
- 解決方案
- 虛擬桌面基礎架構
- 設備管理
- 整合通訊
- 軟體資產管理
- 服務
- 解決方案
- 按組織規模
- 大公司
- 小型企業
- 部署模式
- 現場
- 雲
- 混合
- 按最終用戶行業分類
- IT/通訊
- 銀行業、金融服務業及保險業
- 衛生保健
- 零售
- 政府
- 教育
- 運輸/物流
- 按型號提供
- 虛擬桌面基礎架構
- Desktop-as-a-Service
- 雲端工作區
- 企業行動管理
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 英國
- 德國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 東南亞
- 其他亞太國家
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 北非
- 其他非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Omnissa(VMware EUC)
- Citrix Systems Inc.
- Microsoft Corporation
- Amazon Web Services Inc.
- Dell Technologies Inc.
- Lenovo Group Ltd.
- HP Inc.
- Nutanix Inc.
- Fujitsu Ltd.
- Genpact Ltd.
- HCL Infosystems Ltd.
- Infosys Ltd.
- LTIMindtree Ltd.
- NetApp Inc.
- Tech Mahindra Ltd.
- Hitachi
- IGEL Technology GmbH
- Parallels International GmbH
- Nerdio Inc.
- ControlUp Inc.
- Cisco Systems Inc.
- Google LLC
第7章 市場機會與未來展望
According to Mordor Intelligence, the end-User computing market size was valued at USD 13.17 billion in 2025 and estimated to grow from USD 14.47 billion in 2026 to reach USD 23.2 billion by 2031, at a CAGR of 9.89% during the forecast period (2026-2031).
This report is Segmented by Product Type( Virtual Desktop Infrastructure, and More), Organization Size (Large Enterprises, and More), Deployment Mode (On-Premise, Cloud, Hybrid), End User Industry (IT and Telecom, Banking Financial Services and Insurance, and More), Delivery Model (Virtual Desktop Infrastructure, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global End User Computing Market Trends and Insights
Drive to Increase Employee Productivity via Digital Workspaces
Enterprises are reimagining productivity by combining virtual desktops, collaboration suites, and AI copilots inside a single digital workspace. Organizations that reach advanced workplace maturity levels report a 57.8% boost in positive employee experience metrics, thanks to quicker access to resources, app self-service, and uniform security controls. Microsoft's early field data shows AI copilots save roughly 10 hours per employee each month, translating into tangible capacity gains. The result is a measurable uplift in innovation, inclusion, and well-being, as seamless device hopping and automated workflows reduce friction and burnout.
Growing Adoption of Cloud-Based Desktop and Application Virtualization
Consumption-based desktop hosting is scaling fast because it eliminates capital expenditure and shortens deployment timelines from months to days. Azure Virtual Desktop production use already spans 26% of surveyed organizations, with 58% planning rollouts within the next two years, driven by policy-based scaling, pay-as-you-go pricing, and native Microsoft 365 integration. Healthcare providers illustrate the upside: browser-delivered desktops logged sub-minute sign-ins, freeing clinicians to spend more time with patients and less on IT wait states.
Complexity Integrating EUC with Legacy Applications and Infrastructure
Banks, hospitals, and government agencies still depend on thick-client applications tied to specific OS versions, hard-coded drive mappings, or serial-port peripherals. Virtual desktops must replicate these dependencies while guaranteeing millisecond response times in mission-critical workflows. Integration projects therefore add middleware, APIs, and parallel test environments, extending timelines and inflating costs. Change-management gaps further undermine ROI; 73% of employees who move to digital workspaces without structured training feel disengaged, risking project rollback. Firms mitigate the drag by phasing workloads, rewriting monoliths into modular services, and introducing user-experience analytics that flag adoption bottlenecks early.
Other drivers and restraints analyzed in the detailed report include:
- Rising BYOD Policies and Mobile Workforce Requiring Unified Endpoint Management
- Windows-10 End-of-Support Triggering Enterprise PC Refresh Cycles
- High Upfront Transformation Costs for VDI and DaaS Migrations
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Solutions retained 60.45% End User Computing market share in 2025, underpinned by mature VDI platforms, device-management suites, and software-asset tools that together generated roughly USD 8 billion in annual recurring revenue. Vendors use unified consoles to orchestrate endpoints, apps, and security, which simplifies compliance audits across thousands of assets. Growth now skews toward managed services, with a 10.05% CAGR, as enterprises prefer outcome-based contracts that offload patching, scaling, and experience monitoring to specialists.
Managed service providers embed AI-driven observability and self-healing capabilities, enabling customers to transition from firefighting tickets to proactive optimization. Healthcare customers, for instance, adopt Device-as-a-Service bundles that convert capex to predictable opex and deliver pre-configured clinical workstations on 36-month refresh cycles, reducing help-desk volumes by double-digit percentages.
Large enterprises controlled 45.85% of End User Computing market size in 2025 and rely on tailored integrations, zero-trust overlays, and global federated identity to secure tens of thousands of users. Concurrent licensing and in-house talent give them lower per-seat operating costs, yet hardware refresh mandates and AI upgrade cycles force continual reinvestment.
SMEs, conversely, expand at 10.25% CAGR because cloud-native desktops remove the need for data-center space or specialized staff. Browser-launched workspaces deploy in under 48 hours and include automatic scaling, backup, and compliance templates. For many SMEs the Windows 10 sunset is a trigger to jump straight to cloud desktops, avoiding hardware outlays and accessing Windows 11-ready environments instantly.
Complete Report Scope:
- By Product Type
- Solutions
- Virtual Desktop Infrastructure
- Device Management
- Unified Communication
- Software Asset Management
- Services
- Solutions
- By Organization Size
- Large Enterprises
- Small and Medium Enterprises
- By Deployment Mode
- On-Premise
- Cloud
- Hybrid
- By End User Industry
- IT and Telecom
- Banking, Financial Services and Insurance
- Healthcare
- Retail
- Government
- Education
- Transportation and Logistics
- By Delivery Model
- Virtual Desktop Infrastructure
- Desktop-as-a-Service
- Cloud Workspaces
- Enterprise Mobility Management
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- South Korea
- Southeast Asia
- Rest of Asia Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- North Africa
- Rest of Africa
- North America
Geography Analysis
The Asia Pacific controlled 62.40% of the End-User Computing market in 2025 and is projected to post a regional 10.72% CAGR from 2026 to 2031. A Zoho survey reveals that APAC organizations have achieved a 66.35% digital workplace maturity score, five points above the global average, with 76% reaching advanced levels. Penetration of AI-enabled tools (54%) and team chat (72%) epitomizes a mobile-first mentality, while steady 5G rollouts create fertile ground for edge-enhanced virtual desktops.
North America exhibits entrenched VDI estates across regulated sectors and leads the early adoption of AI copilots, which save roughly 10 hours per user per month. The Windows 10 cutoff brings an immediate refresh wave that favors modern endpoint management and DaaS. Europe mirrors the pattern but adds stringent GDPR mandates, steering multinationals toward hybrid deployments that balance local data residency with global cloud scale.
Emerging markets in the Middle East, Africa, and Latin America treat cloud desktops as a leapfrog opportunity to bypass legacy infrastructure. Consumption models align with budget constraints, while telco-edge collaborations promise sub-20-millisecond latency for immersive field maintenance or remote-assistance scenarios. Governments increasingly codify data-localization rules, encouraging regional cloud zones and sovereign VDI stacks that can interconnect with global platforms.
- Omnissa (VMware EUC)
- Citrix Systems Inc.
- Microsoft Corporation
- Amazon Web Services Inc.
- Dell Technologies Inc.
- Lenovo Group Ltd.
- HP Inc.
- Nutanix Inc.
- Fujitsu Ltd.
- Genpact Ltd.
- HCL Infosystems Ltd.
- Infosys Ltd.
- LTIMindtree Ltd.
- NetApp Inc.
- Tech Mahindra Ltd.
- Hitachi
- IGEL Technology GmbH
- Parallels International GmbH
- Nerdio Inc.
- ControlUp Inc.
- Cisco Systems Inc.
- Google LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDCSAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Drive to Increase Employee Productivity via Digital Workspaces
- 4.2.2 Growing Adoption of Cloud-Based Desktop and Application Virtualization
- 4.2.3 Rising BYOD Policies and Mobile Workforce Requiring Unified Endpoint Management
- 4.2.4 Windows-10 End-of-Support Triggering Enterprise PC Refresh Cycles
- 4.2.5 Emergence of AI-Capable Endpoints Enabling On-Device GenAI Workloads
- 4.2.6 Telco Edge-Cloud Partnerships Enabling Ultra-Low-Latency EUC for Field AR-VR
- 4.3 Market Restraints
- 4.3.1 Complexity Integrating EUC with Legacy Applications and Infrastructure
- 4.3.2 High Upfront Transformation Costs for VDI and DaaS Migrations
- 4.3.3 Vendor Consolidation-Driven License Uncertainty (e.g., VMware EUC Divestiture)
- 4.3.4 Data Sovereignty Concerns Hindering Full Cloud EUC Adoption
- 4.4 Impact of Macroeconomic Factors
- 4.5 Industry Value / Supply-Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Consumers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Solutions
- 5.1.1.1 Virtual Desktop Infrastructure
- 5.1.1.2 Device Management
- 5.1.1.3 Unified Communication
- 5.1.1.4 Software Asset Management
- 5.1.2 Services
- 5.1.1 Solutions
- 5.2 By Organization Size
- 5.2.1 Large Enterprises
- 5.2.2 Small and Medium Enterprises
- 5.3 By Deployment Mode
- 5.3.1 On-Premise
- 5.3.2 Cloud
- 5.3.3 Hybrid
- 5.4 By End User Industry
- 5.4.1 IT and Telecom
- 5.4.2 Banking, Financial Services and Insurance
- 5.4.3 Healthcare
- 5.4.4 Retail
- 5.4.5 Government
- 5.4.6 Education
- 5.4.7 Transportation and Logistics
- 5.5 By Delivery Model
- 5.5.1 Virtual Desktop Infrastructure
- 5.5.2 Desktop-as-a-Service
- 5.5.3 Cloud Workspaces
- 5.5.4 Enterprise Mobility Management
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 United Kingdom
- 5.6.3.2 Germany
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Russia
- 5.6.3.7 Rest of Europe
- 5.6.4 Asia Pacific
- 5.6.4.1 China
- 5.6.4.2 India
- 5.6.4.3 Japan
- 5.6.4.4 South Korea
- 5.6.4.5 Southeast Asia
- 5.6.4.6 Rest of Asia Pacific
- 5.6.5 Middle East
- 5.6.5.1 Saudi Arabia
- 5.6.5.2 United Arab Emirates
- 5.6.5.3 Turkey
- 5.6.5.4 Rest of Middle East
- 5.6.6 Africa
- 5.6.6.1 South Africa
- 5.6.6.2 North Africa
- 5.6.6.3 Rest of Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 Omnissa (VMware EUC)
- 6.4.2 Citrix Systems Inc.
- 6.4.3 Microsoft Corporation
- 6.4.4 Amazon Web Services Inc.
- 6.4.5 Dell Technologies Inc.
- 6.4.6 Lenovo Group Ltd.
- 6.4.7 HP Inc.
- 6.4.8 Nutanix Inc.
- 6.4.9 Fujitsu Ltd.
- 6.4.10 Genpact Ltd.
- 6.4.11 HCL Infosystems Ltd.
- 6.4.12 Infosys Ltd.
- 6.4.13 LTIMindtree Ltd.
- 6.4.14 NetApp Inc.
- 6.4.15 Tech Mahindra Ltd.
- 6.4.16 Hitachi
- 6.4.17 IGEL Technology GmbH
- 6.4.18 Parallels International GmbH
- 6.4.19 Nerdio Inc.
- 6.4.20 ControlUp Inc.
- 6.4.21 Cisco Systems Inc.
- 6.4.22 Google LLC
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


