


 |
市場調查報告書
商品編碼
2124182
飛行時間(TOF)感測器:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)Time-of-Flight (TOF) Sensor - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,2025 年全球飛行時間 (ToF) 感測器市場價值為 66.8 億美元,預計到 2031 年將從 2026 年的 80.6 億美元成長至 205.2 億美元,預測期(2026-2031 年)的複合成長率為 20.56%。
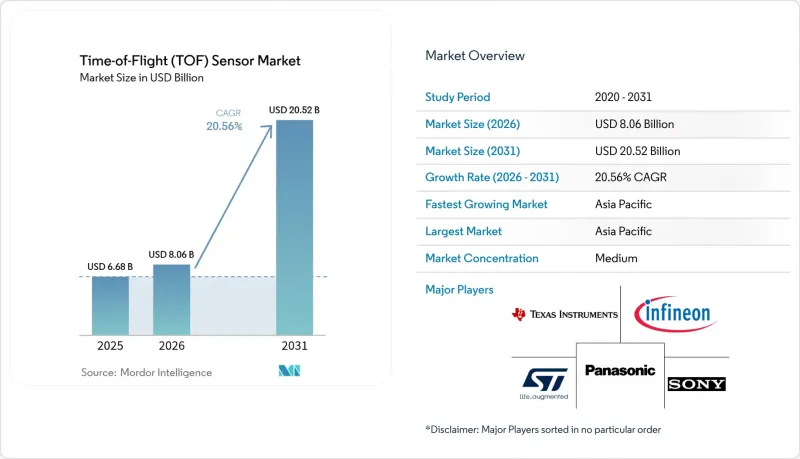
本報告按感測器類型(間接式、直接式、測距門控成像器)、解析度(QVGA 或更低、VGA、高清或更高)、測量距離(短、中、長)、應用(擴增實境(AR) 和虛擬實境 (VR)、雷射雷達、其他)、終端用戶產業(家用電子電器、汽車、其他)以及地區進行細分。市場預測以美元 (USD) 為單位。
全球飛行時間(TOF)感測器市場趨勢與洞察
歐洲和日本機器視覺系統部署的擴展
德國、義大利和日本的工業叢集正在為機器人配備飛行時間成像器,以提高揀選和隨機疊棧的效率。尼康的機器人視覺套件自2024年底開始出貨,能夠以250幀/秒的速度傳輸深度幀,從而縮短汽車沖壓生產線的循環時間。日本系統整合商目前正致力於將這些感測器與專用5G網路結合,以便在偵測到入侵時立即停止機器運作。東京貿易公司和NetOne Systems在2025年展示了這種方法。隨著勞動力短缺問題日益嚴重,以及歐盟工廠升級到工業4.0標準,預計飛行時間感測器市場將迎來中階iToF陣列的穩定訂單。
中國和韓國對dToF 3D智慧型手機相機的需求不斷成長
三星Galaxy S24 Ultra搭載了首款dToF模組,該模組具備更精準的背景虛化效果和AR錨定功能,加速了旗艦機型從結構化光學ToF向直接ToF技術的轉變。中國廠商紛紛效仿,以提升其成像能力。分析師預測,到2030年,智慧型手機3D相機的銷售額將達到440.1億美元。設備更新換代週期短意味著每次設計革新都將提升年度出貨量,進一步擴大行動裝置在飛行時間感測器市場的佔有率。
超過 30 公尺距離處的多路徑干擾和環境光雜訊
麻省理工學院的實驗表明,從多個表面反射的光子會扭曲原始相位數據,導致深度圖上物體位置的識別錯誤。微軟的SPUMIC演算法透過軟體補償了這個問題,但其高昂的運算成本使其不適用於預算受限的部署。感測器供應商正透過更大的像素和全局百葉窗陣列來解決這個問題,但在明亮的戶外條件下,性能仍然會下降,這限制了其在飛行時間(ToF)感測器市場中一些智慧城市和遠端工業應用中的使用。
細分市場分析
到2025年,間接式飛行時間(ToF)技術將佔據飛行時間感測器市場62.40%的佔有率。這反映了其在智慧型手機、網路攝影機和取放機器人等領域的成本優勢和技術成熟度。直接式ToF單元雖然價格較高,但由於其測距門控SPAD陣列即使在超過200公尺的距離上也能保證公分級的精度,因此正以22.6%的複合年成長率快速成長。隨著汽車製造商專注於以雷射雷達(LiDAR)為核心的ADAS系統,直接式ToF模組的市場規模預計將迅速擴大。一級供應商重視dToF提供的零延遲深度輸出,這確保了感測器融合過程中與雷達軌跡的冗餘性。間接式ToF晶片組不斷增加全域百葉窗、HDR和嵌入式DSP等新功能,逐漸成為AR智慧型手機和工廠協作機器人的標準配備。
先進的晶圓代工製程節點如今整合了片上直方圖處理功能,降低了對外部DRAM的需求,並將VR控制器的組件成本減半。如果智慧型手機OEM廠商能夠將單一iToF晶片同時用於前置人像攝影機和後置自動對焦輔助系統,飛行時間(ToF)感測器市場將從中受益。另一方面,在汽車LiDAR領域,由於需要將崩潰式二極體與邏輯電路進行電隔離,直接ToF成本預計在2031年之前仍將居高不下。兩種架構的共存既滿足了各自的性能需求,也穩定了飛行時間感測器市場的收入來源。
智慧型手機人像攝影和擴增實境(AR)地圖繪製將在2025年佔據48.10%的需求佔有率,鞏固3D成像作為最大收入來源的地位。隨著L3級高級駕駛輔助系統(ADAS)的部署,每輛車需要配備多個車頂雷射器,因此用於雷射雷達(LiDAR)的飛行時間(ToF)感測器市場正以23.1%的複合年成長率快速成長。 iToF相機正被用於電子組裝上的機器視覺改造,以即時檢測焊點錯位;深度陣列則被安裝在電物流中心的巡邏機器人上,用於動態避障。
機器人和無人機領域雖然目前規模較小,但卻是尚未開發的、具有巨大成長潛力的市場。在缺氧礦井中,dToF掃描儀用於繪製礦洞地圖;輕型ToF高度計則用於農業無人機,以保持與樹冠的距離。智慧電視、遊戲機和XR頭顯中的手勢姿態辨識正轉向多區域iToF,以避免RGB影像帶來的隱私問題。車載駕駛員監控將於2026年起在歐洲強制實施,這推動了超廣角近紅外線ToF光學技術的進步。該技術無需發出可見光即可追蹤駕駛員的視線和微睡眠行為,從而擴大了飛行時間(ToF)感測器市場中與安全相關的收入。
區域分析
亞太地區仍然是飛行時間(ToF)感測器市場的核心,供應和消費了全球一半以上的產量。廣東省的智慧型手機組裝中心每季消耗數百萬顆iToF晶片,而江蘇省的後端企業正在進行大規模的超構光學透鏡應用。日本晶圓廠正為高利潤的汽車合約精進SPAD晶圓,並利用國內的機器人生態系統試行新的製程節點。韓國的垂直整合型企業集團正在推動發送器和影像感測器的生產,既創造了國內需求,也帶來了出口收入,從而穩定了晶圓廠的產運轉率。隨著行動電話平均售價(ASP)的上漲以及該地區採用多光束雷射雷達的電動車(EV)的普及,亞太地區的ToF感測器市場規模也在不斷成長。
北美在技術規格方面處於主導地位。矽谷的雷射雷達新創公司正不斷突破探測範圍和視覺安全性的極限,而高密度機器人協作技術正在西雅圖周邊的電商倉庫中得到驗證。聯邦公路監管機構正在考慮進行免手持駕駛試點項目,間接推動了車載冗餘攝影機的普及,並擴大了該地區對飛行時間(ToF)感測器的需求。在加拿大的農業技術領域,基於無人機的近紅外線飛行時間高度計生物量估算技術正在進行試點,並顯示出在農村地區具有成長潛力。
在歐洲,監管壓力與工業自動化正在融合。歐盟《2026年通用安全條例》強制要求對駕駛員進行進階監控,並確保最低出貨量。德國一級供應商、義大利包裝線專家和北歐機器人製造商正在將iToF技術整合到品質關鍵型工作流程中。節能工廠維修的稅收優惠政策正在增加感測器更換週期所需的資金籌措。儘管經濟逆風導致家用電子電器需求放緩,但工業資本投資正在促進該地區飛行時間(ToF)感測器市場的穩定。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 宏觀經濟影響分析
- 市場促進因素
- 在歐洲和日本的主要製造地擴大機器視覺系統的應用。
- 中國和韓國對配備dToF 3D相機的智慧型手機的需求日益成長
- 將dToF雷射雷達整合到歐盟和美國的L3+ ADAS部署中
- 基於 SPAD 的 ToF 模組小型化使得相機島的尺寸小於 6 毫米。
- 倉庫自動化程度的不斷提高,推動了北美物流行業對 iToF 深度相機的需求。
- 基於歐盟GSR-2026標準的政府強制駕駛監控系統
- 市場限制因素
- 超過 30 公尺距離處的多路徑干擾和環境光雜訊
- 台灣與美國之間VCSEL供應集中度的波動
- 歐盟《一般資料保護規範》(GDPR) 對商店內人員計數攝影機有嚴格的規定
- 由於結構光深度解決方案的競爭,入門級智慧型手機的價格下降。
- 價值供應鏈分析
- 監管和技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 依感測器類型
- 間接型(iToF/RF調製型)
- 直接型(dToF)
- 測距門成像器
- 按組件
- 照明(VCSEL/LED)
- 感測器/接收器陣列
- 深度處理器
- 通過決議
- QVGA 或以下
- VGA
- 高清或更高
- 按範圍
- 短的
- 中等的
- 長的
- 透過使用
- 擴增實境(AR)和虛擬實境(VR)
- LiDAR
- 機器視覺
- 3D影像和掃描(包括智慧型手機相機)
- 機器人和無人機
- 手勢姿態辨識和生物識別
- 車載駕駛監控系統
- 安全監控
- 按最終用戶行業分類
- 家用電子產品
- 車
- 娛樂和遊戲
- 工業和製造業
- 醫療保健和醫學影像
- 物流和倉儲自動化
- 安全和智慧建築
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 韓國
- 印度
- 其他亞太國家
- 中東
- 以色列
- 沙烏地阿拉伯
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 其他非洲國家
- 大洋洲
- 澳洲
- 紐西蘭
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Sony Corporation(Sony Semiconductor Solutions)
- STMicroelectronics NV
- Infineon Technologies AG
- Texas Instruments Incorporated
- onsemi(ON Semiconductor Corp.)
- Panasonic Holdings Corp.
- Sharp Corp.
- Keyence Corp.
- Teledyne Technologies Inc.
- Omron Corp.
- ams-OSRAM AG
- Melexis NV
- PMD Technologies AG
- Analog Devices Inc.
- Cognex Corp.
- LMI Technologies Inc.
- Samsung Electronics Co. Ltd.
- LG Innotek Co. Ltd.
- Hamamatsu Photonics KK
- Renesas Electronics Corp.
- Himax Technologies Inc.
- Tower Semiconductor Ltd.
第7章 市場機會與未來展望
According to Mordor Intelligence, the global Time-of-Flight sensor market size was valued at USD 6.68 billion in 2025 and estimated to grow from USD 8.06 billion in 2026 to reach USD 20.52 billion by 2031, at a CAGR of 20.56% during the forecast period (2026-2031).
This report is Segmented by Sensor Type (Indirect, Direct, Range-Gated Imagers), Resolution (QVGA and Below, VGA, HD and Above), Range (Short, Medium, Long), Application (Augmented and Virtual Reality, Lidar, and More), End-User Vertical (Consumer Electronics, Automotive, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Time-of-Flight (TOF) Sensor Market Trends and Insights
Growing adoption of machine-vision systems in Europe and Japan
Industrial clusters in Germany, Italy, and Japan are equipping robots with Time-of-Flight imagers to improve bin-picking and random-order depalletizing. Nikon's robot-vision package, shipping since late 2024, streams 250 fps depth frames, cutting cycle time for automotive stamping lines. Japanese integrators now couple these sensors with private 5 G to stop machines instantly when intrusion is detected, an approach validated by Tokyo Boeki and Net One Systems in 2025. As labor shortages worsen and EU factories upgrade to Industry 4.0 standards, the Time-of-Flight sensor market expects steady purchase orders for mid-range iToF arrays.
Rising demand for dToF 3-D smartphone cameras in China and South Korea
Samsung's Galaxy S24 Ultra debuted a refined dToF module that improves bokeh accuracy and AR anchoring, reinforcing the shift from structured-light to direct ToF in flagships. Chinese OEMs mirror this move to differentiate imaging, and analysts see smartphone 3-D camera revenues climbing to USD 44.01 billion by 2030. Because handset refresh cycles are short, every design win lifts annual unit volumes, magnifying the contribution of mobile shipments to the Time-of-Flight sensor market.
Multipath Interference and Ambient-Light Noise at Greater than30 m Range
Laboratory trials at MIT show that photons bouncing off multiple surfaces distort raw phase data, misplacing objects in depth maps. Microsoft's SPUMIC algorithm corrects this in software, yet its compute footprint discourages budget deployments. Sensor vendors respond with larger pixels and global-shutter arrays, but performance still drops outdoors at noon, restraining some smart-city and long-haul industrial use cases inside the Time-of-Flight sensor market.
Other drivers and restraints analyzed in the detailed report include:
- dToF LiDAR integration for Level-3+ ADAS roll-outs in EU and US
- Miniaturization of SPAD-based modules enabling sub-6 mm camera islands
- Volatile VCSEL supply concentration in the Taiwan-US corridor
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Indirect ToF technology accounted for 62.40% of the Time-of-Flight sensor market in 2025, reflecting its cost advantage and maturity in smartphones, webcams, and pick-and-place robots. Direct ToF units, though pricier, are surging at a 22.6% CAGR because range-gated SPAD arrays guarantee centimeter-grade accuracy beyond 200 m. The Time-of-Flight sensor market size for direct ToF modules is projected to swell rapidly as automakers fixate on LiDAR-centric ADAS stacks. Tier-1 suppliers value the latency-free depth output that dToF delivers, enabling redundancy with radar tracks during sensor-fusion. Indirect ToF chipsets continue to gain new features-global-shutter, HDR, and embedded DSP-positioning them as the default for AR handsets and factory cobots.
Advanced foundry nodes now pack on-chip histogramming that reduces external DRAM needs, cutting bill-of-materials in half for VR controllers. The Time-of-Flight sensor market benefits when handset OEMs can reuse a single iToF die across front-facing portrait cameras and rear-facing autofocus assist. Automobile LiDAR, however, mandates avalanche diodes, galvanically isolated from logic, which keeps the direct ToF bill higher through 2031. Both architectures coexist, filling discrete performance slots and stabilizing revenue diversity within the Time-of-Flight sensor market.
Smartphone portraiture and AR mapping drove 48.10% of 2025 demand, cementing 3-D imaging as the largest revenue bucket. The Time-of-Flight sensor market size for LiDAR is climbing at a 23.1% CAGR because Level-3 ADAS roll-outs require multiple roof-line lasers per vehicle. Machine-vision retrofits in electronics assembly lines adopt iToF cameras to identify solder misalignment at real-time takt speed, and e-commerce distribution centers fit depth arrays on aisle-roaming robots for dynamic obstacle avoidance.
Robotics and drones, while smaller today, represent high-growth greenfields: oxygen-starved mines use dToF scanners to map voids, and crop-spraying UAVs leverage low-weight ToF altimeters to maintain canopy distance. Gesture-recognition in smart TVs, gaming consoles, and XR headsets shifts toward multizone iToF, avoiding the privacy pitfalls of RGB capture. In-cabin driver monitoring-mandated in Europe from 2026-advances ultrawide near-infrared ToF optics that track gaze and microsleep behavior without emitting visible light, broadening safety-related revenues for the Time-of-Flight sensor market.
Complete Report Scope:
- By Sensor Type
- Indirect (iToF / RF-Modulated)
- Direct (dToF)
- Range-Gated Imagers
- By Component
- Illumination (VCSEL/LED)
- Sensor/Receiver Array
- Depth Processor
- By Resolution
- QVGA and Below
- VGA
- HD and Above
- By Range
- Short
- Medium
- Long
- By Application
- Augmented and Virtual Reality
- LiDAR
- Machine Vision
- 3-D Imaging and Scanning (incl. Smartphone Cameras)
- Robotics and Drones
- Gesture Recognition and Biometrics
- In-Cabin Driver-Monitoring Systems
- Security and Surveillance
- By End-User Vertical
- Consumer Electronics
- Automotive
- Entertainment and Gaming
- Industrial and Manufacturing
- Healthcare and Medical Imaging
- Logistics and Warehouse Automation
- Security and Smart Buildings
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Rest of Asia-Pacific
- Middle East
- Israel
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Oceania
- Australia
- New Zealand
- North America
Geography Analysis
Asia-Pacific remains the epicenter of the Time-of-Flight sensor market, supplying and consuming over half of global output. China's smartphone assembly clusters in Guangdong absorb millions of iToF dies each quarter, while Jiangsu-based back-end houses attach meta-optics lenses at scale. Japanese fabs refine SPAD wafers for high-margin automotive contracts, leveraging domestic robotics ecosystems to pilot new process nodes. South Korea's vertically integrated conglomerates anchor both emitter and image-sensor production, providing internal demand and export revenue that stabilizes fab utilization. The Time-of-Flight sensor market size in this region grows in lockstep with handset ASP gains and regional EV roll-outs that specify multi-beam LiDAR.
North America drives technological specification. Silicon Valley lidar start-ups push range and eye-safety envelopes, and Seattle-area e-commerce warehouses prove out high-density robot-to-robot coordination. Federal highway regulators studying hands-free pilot deployments indirectly promote adoption of redundant cabin cameras, enlarging local demand for the Time-of-Flight sensor market. Canada's agritech scene pilots drone-based biomass estimation using NIR ToF altimeters, marking niche rural growth.
Europe blends regulatory pull and industrial automation. The EU General Safety Regulation 2026 mandates advanced driver-monitoring, guaranteeing baseline shipments. German Tier-1s, Italian packaging-line specialists, and Nordic robotics makers integrate iToF in quality-driven workflows. Tax incentives for energy-efficient factory retrofits help finance sensor refresh cycles. Although economic headwinds temper consumer electronics demand, industrial capital expenditure stabilizes the regional Time-of-Flight sensor market.
- Sony Corporation (Sony Semiconductor Solutions)
- STMicroelectronics N.V.
- Infineon Technologies AG
- Texas Instruments Incorporated
- onsemi (ON Semiconductor Corp.)
- Panasonic Holdings Corp.
- Sharp Corp.
- Keyence Corp.
- Teledyne Technologies Inc.
- Omron Corp.
- ams-OSRAM AG
- Melexis N.V.
- PMD Technologies AG
- Analog Devices Inc.
- Cognex Corp.
- LMI Technologies Inc.
- Samsung Electronics Co. Ltd.
- LG Innotek Co. Ltd.
- Hamamatsu Photonics K.K.
- Renesas Electronics Corp.
- Himax Technologies Inc.
- Tower Semiconductor Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Macroeconomic Impact Analysis
- 4.3 Market Drivers
- 4.3.1 Growing Adoption of Machine Vision Systems Across Manufacturing Hubs in Europe and Japan
- 4.3.2 Rising Demand for Smartphones Integrating dToF 3-D Cameras in China and South Korea
- 4.3.3 Integration of dToF LiDAR for Level-3+ ADAS Roll-outs in EU and U.S.
- 4.3.4 Miniaturization of SPAD-Based ToF Modules Enabling Sub-6 mm Camera Islands
- 4.3.5 Warehouse Automation Push Elevating iToF Depth Cameras in North-American Logistics
- 4.3.6 Government-Mandated Driver-Monitoring Systems under EU GSR-2026
- 4.4 Market Restraints
- 4.4.1 Multipath Interference and Ambient-Light Noise at >30 m Range
- 4.4.2 Volatile VCSEL Supply Concentration in Taiwan-U.S. Corridor
- 4.4.3 Strict EU GDPR Rules on In-Store People-Counting Cameras
- 4.4.4 Price Erosion from Competing Structured-Light Depth Solutions in Entry Smartphones
- 4.5 Value / Supply-Chain Analysis
- 4.6 Regulatory and Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitute Products
- 4.7.5 Degree of Competition
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Sensor Type
- 5.1.1 Indirect (iToF / RF-Modulated)
- 5.1.2 Direct (dToF)
- 5.1.3 Range-Gated Imagers
- 5.2 By Component
- 5.2.1 Illumination (VCSEL/LED)
- 5.2.2 Sensor/Receiver Array
- 5.2.3 Depth Processor
- 5.3 By Resolution
- 5.3.1 QVGA and Below
- 5.3.2 VGA
- 5.3.3 HD and Above
- 5.4 By Range
- 5.4.1 Short
- 5.4.2 Medium
- 5.4.3 Long
- 5.5 By Application
- 5.5.1 Augmented and Virtual Reality
- 5.5.2 LiDAR
- 5.5.3 Machine Vision
- 5.5.4 3-D Imaging and Scanning (incl. Smartphone Cameras)
- 5.5.5 Robotics and Drones
- 5.5.6 Gesture Recognition and Biometrics
- 5.5.7 In-Cabin Driver-Monitoring Systems
- 5.5.8 Security and Surveillance
- 5.6 By End-User Vertical
- 5.6.1 Consumer Electronics
- 5.6.2 Automotive
- 5.6.3 Entertainment and Gaming
- 5.6.4 Industrial and Manufacturing
- 5.6.5 Healthcare and Medical Imaging
- 5.6.6 Logistics and Warehouse Automation
- 5.6.7 Security and Smart Buildings
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 South America
- 5.7.2.1 Brazil
- 5.7.2.2 Argentina
- 5.7.2.3 Rest of South America
- 5.7.3 Europe
- 5.7.3.1 Germany
- 5.7.3.2 United Kingdom
- 5.7.3.3 France
- 5.7.3.4 Italy
- 5.7.3.5 Rest of Europe
- 5.7.4 Asia-Pacific
- 5.7.4.1 China
- 5.7.4.2 Japan
- 5.7.4.3 South Korea
- 5.7.4.4 India
- 5.7.4.5 Rest of Asia-Pacific
- 5.7.5 Middle East
- 5.7.5.1 Israel
- 5.7.5.2 Saudi Arabia
- 5.7.5.3 Turkey
- 5.7.5.4 Rest of Middle East
- 5.7.6 Africa
- 5.7.6.1 South Africa
- 5.7.6.2 Rest of Africa
- 5.7.7 Oceania
- 5.7.7.1 Australia
- 5.7.7.2 New Zealand
- 5.7.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global and Market Overview, Core Segments, Financials, Strategy, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Sony Corporation (Sony Semiconductor Solutions)
- 6.4.2 STMicroelectronics N.V.
- 6.4.3 Infineon Technologies AG
- 6.4.4 Texas Instruments Incorporated
- 6.4.5 onsemi (ON Semiconductor Corp.)
- 6.4.6 Panasonic Holdings Corp.
- 6.4.7 Sharp Corp.
- 6.4.8 Keyence Corp.
- 6.4.9 Teledyne Technologies Inc.
- 6.4.10 Omron Corp.
- 6.4.11 ams-OSRAM AG
- 6.4.12 Melexis N.V.
- 6.4.13 PMD Technologies AG
- 6.4.14 Analog Devices Inc.
- 6.4.15 Cognex Corp.
- 6.4.16 LMI Technologies Inc.
- 6.4.17 Samsung Electronics Co. Ltd.
- 6.4.18 LG Innotek Co. Ltd.
- 6.4.19 Hamamatsu Photonics K.K.
- 6.4.20 Renesas Electronics Corp.
- 6.4.21 Himax Technologies Inc.
- 6.4.22 Tower Semiconductor Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 飛行時間感測器市場預測至2034年—按感測器類型、組件、偵測範圍、解析度、應用、最終用戶和地區分類的全球分析
 飛行時間感測器市場:按類型、組件、技術、測量範圍、輸出類型、波長、應用和分銷管道分類-2026-2032年全球市場預測全球飛行時間(ToF)感測器市場預測至2034年:按技術、組件、檢測範圍、解析度、應用、最終用戶和地區分類
 全球飛行時間(ToF)感測器市場
 飛行時間 (ToF) 感測器市場分析及預測(至 2035 年):按類型、產品類型、應用、技術、組件、最終用戶、設備、功能、安裝類型和解決方案分類
 飛行時間(ToF)感測器市場規模、佔有率、趨勢及預測(按類型、應用、最終用戶和地區分類),2026-2034年
 飛行時間 (ToF) 感測器市場規模、佔有率、成長及全球產業分析:依類型、應用和地區劃分的洞察與預測 (2026–2034)
 2026年全球飛行時間(TOF)感測器市場報告
 2025-2029年全球飛行時間(TOF)感測器市場超音波飛行時間感測器市場:依技術、感測器類型、偵測範圍、通道配置、安裝類型、工作模式和應用分類-2026年至2032年全球預測