


 |
市場調查報告書
商品編碼
2124066
大理石:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Marble - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
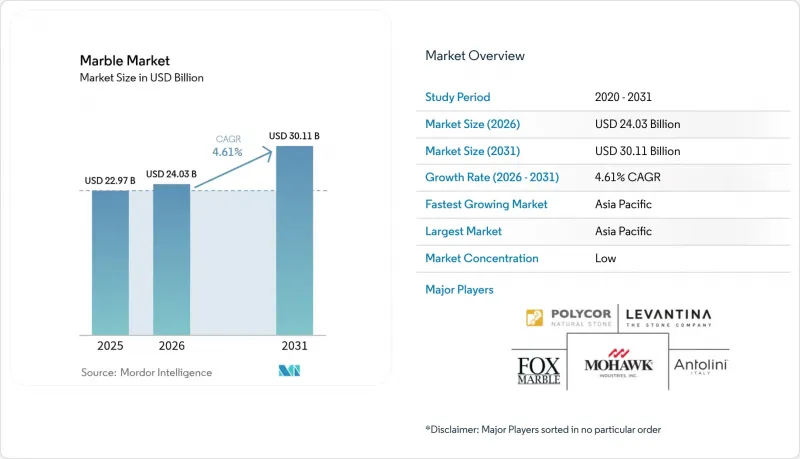
據 Mordor Intelligence 稱,2025 年大理石市場價值為 229.7 億美元,預計到 2031 年將達到 301.1 億美元,而 2026 年為 240.3 億美元,預測期(2026-2031 年)的複合年成長率為 4.61%。
本報告按產品類型(天然大理石和合成/人造大理石)、顏色(白色、黑色、黃色、紅色及其他顏色)、應用領域(建築和裝飾、雕塑和紀念碑等)、最終用戶行業(住宅等)以及地區(亞太地區、北美地區、歐洲地區等)對行業進行細分。市場預測以美元計價。
全球大理石市場趨勢及洞察
建設產業的快速成長
隨著建築投資的增加,越來越多的開發人員在豪華住宅和綜合用途大樓中指定使用高階石材作為地板、牆壁和檯面材料,從而帶動了對大理石的需求成長。亞太地區各國政府持續為交通樞紐和公共建築撥款,這些建築通常採用大尺寸石材覆層,進一步促進了大理石在結構和裝飾方面的應用。工廠預製的大理石板材經過高精度切割,可縮短施工時間,減少現場損壞,幫助承包商確保工程按時完工。厚度僅3-5毫米的薄型飾面可減輕高層建築外觀的荷載,而大理石-混凝土複合材料因其重量輕、碳含量低等優勢,在追求綠色建築認證的項目中得到越來越廣泛的應用,進一步推動了大理石市場的成長。
豪華房地產和基礎設施項目增加
豪華飯店集團和高階辦公大樓開發商正利用獨特的石材打造令人印象深刻的入口、康體中心和餐飲空間。杜拜、新加坡和紐約的五星級飯店設計師們指定使用紋理醒目、圖案引人注目的石板,因為天然石材的紋理變化能為賓客營造一種專屬感。精品酒店品牌也將類似的概念延伸至小規模的場所,這反映了大理石市場的成長以及人們對能夠區別於人造石材的稀有色調日益成長的需求。
與大理石粉塵相關的健康危害
切割和拋光過程中產生的可吸入結晶質二氧化矽,在加州報告了127例矽肺病病例和13例死亡後,正受到嚴格監管。截至2024年4月,加州已通報了此類病例。這促使當局製定了新的接觸限值,並強制要求使用濕式切割。儘管二氧化矽在天然大理石中的含量不到10%,但監管機構對所有石材加工企業都實施了類似的規定。遵守這些規定的成本,包括密封工作台、高吸塵器裝置和個人監測系統,給缺乏資金升級設備的小規模大理石加工商帶來了沉重的負擔。
細分市場分析
到2025年,人造大理石將佔據80.65%的市場佔有率,因為工業樹脂系統已經能夠完美複製卡拉拉和卡拉卡塔等高階大理石的外觀和觸感,同時兼具硬度和抗污性。在家庭裝修通路和加工流程加速發展的推動下,預計該細分市場將繼續以4.72%的複合年成長率擴大主導地位。天然大理石在一些項目中仍然扮演著至關重要的角色,因為其真實性和持久的質感比維護成本更為重要。旗艦酒店和客製化住宅的設計師仍然會指定使用大塊大理石用於接待台、樓梯、雕塑等。在巴西等國家,鋼絲鋸和無人機測繪技術正在提高採石場的獲利能力,而各種新型白色大理石也開始出現在世界各地的展示室中。
預計到2025年,白色石材的需求量將佔總需求量的36.02%,並將以5.60%的複合年成長率持續成長至2031年,顯著高於大理石整體市場的成長速度。設計師認為,白色石材的需求也不斷成長。
黑色大理石,例如尼祿馬奎納大理石,正逐漸成為旗艦零售店和頂層公寓廚房中引人注目的對比色點綴。黃色、紅色和綠色大理石迎合了中東和亞洲部分地區的美學偏好,通常與當地文化象徵意義緊密相連。多色大理石和布雷西亞大理石則吸引著追求醒目牆面效果的前衛建築師。如今,色彩選擇擴大借助數位孿生庫,在設計階段即可預覽整塊大理石板,從而減少不確定性和廢棄物。
區域分析
預計到2025年,亞太地區將佔全球大理石市場佔有率的33.62%,年複合成長率最高,達6.10%。印度智慧城市的建設和印尼新首都的開發,催生了對地板材料和外牆石材的新需求。越南和巴基斯坦的生產商正在擴大採石場產量,以滿足當地的規格要求。
歐洲市場以義大利和土耳其為中心。卡拉拉大理石以其標誌性的潔白而聞名,但廢棄物仍然是一個難題,高達70%的採石場石材最終被當作污泥丟棄。法規和社會壓力正在推動對「廢棄物變廢為寶」計畫的投資,例如水循環利用、乾式成型和以大理石為原料的3D列印耗材。德國和西班牙的加工商正在向尋求綠色認證的建築師銷售低排放認證石材。
在北美,高價位依然存在,特色品種的供應也較為緊張。需求主要集中在豪華住宅大樓、精品酒店和高階零售商店。
南美洲正在崛起為供應基地,巴西白石英岩和大理石被廣泛應用於美國和歐洲的計畫。在中東和非洲,沙烏地阿拉伯、阿拉伯聯合大公國和南非的大型企劃帶動了強勁的需求。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 建設產業的快速成長
- 豪華房地產和基礎設施項目增加
- 擴大大理石粉作為低碳混凝土輔助水泥基材料的應用。
- 人們對大理石作為天然永續材料的興趣日益濃厚。
- 採礦和加工技術的進步正在推動大理石產業的發展。
- 市場限制因素
- 與大理石粉塵相關的健康危害
- 合成替代品帶來的競爭
- 廢棄物產生和回收面臨的挑戰
- 價值鏈分析
- 波特五力模型
- 貿易分析
第5章 市場規模與成長預測
- 依產品類型
- 天然大理石
- 人造大理石
- 按顏色
- 白色的
- 黑色的
- 黃色的
- 紅色的
- 其他顏色
- 透過使用
- 建築/施工
- 雕像和紀念碑
- 家具
- 其他用途(裝飾基礎設施)
- 按最終用戶類別
- 住宅大樓
- 商業和酒店
- 工業和公共部門
- 按地區
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 其他亞太國家
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 土耳其
- 其他歐洲國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 南非
- 其他中東和非洲國家
- 亞太地區
第6章 競爭情勢
- 市場集中度
- 策略性舉措(併購、合作、採石場整合)
- 市佔率和排名分析
- 公司簡介
- Antolini Luigi & CSpa
- BC Marble Products Ltd
- Best Cheer Stone Group
- China Kingstone Mining Holdings Limited
- Dimpomar
- Eco Buildings Group Plc
- FHL
- Fox Marble
- HELLENIC GRANITE Co
- Hilltop Stones Pvt. Ltd.
- Kangli stone group
- Levantina y Asociados de Minerales, SA
- Mohawk Industries, Inc.
- Mumal Marbles Pvt. Ltd.
- NQ Acrylic and Stone
- Polycor Inc.
- Santucci Group Srl
- TEKMAR MERKEZ OFFICES
- Temmer Marble
- Topalidis SA
- UMGG
- XISHI GROUP LTD.
第7章 市場機會與未來展望
According to Mordor Intelligence, the marble market size was valued at USD 22.97 billion in 2025 and estimated to grow from USD 24.03 billion in 2026 to reach USD 30.11 billion by 2031, at a CAGR of 4.61% during the forecast period (2026-2031).
This report Segments the Industry by Product Type (Natural Marble and Synthetic/Artificial Marble), Color (White, Black, Yellow, Red, and Other Colors), Application (Building and Decoration, Statues and Monuments, and More), End-User Sector (Residential Buildings, and More), and Geography (Asia-Pacific, North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Marble Market Trends and Insights
Rapid Growth in the Construction Industry
Construction spending is cascading into higher marble demand as developers specify premium stone for floors, walls, and countertops in luxury homes and mixed-use towers. Governments across Asia-Pacific continue to funnel budget into transport hubs and civic buildings that feature large-format stone cladding, lifting structural as well as decorative usage. Prefabricated marble panels, factory-cut to tight tolerances, are saving installation time and reducing on-site breakage, helping contractors meet schedule guarantees. Thin 3-5 mm veneers are opening high-rise facades to lighter loads, and marble-concrete composites are appearing in projects seeking green-building certifications due to weight and embodied-carbon advantages, supporting the growth in the marble market.
Increase in Luxury Real Estate and Infrastructure Projects
Luxury hospitality groups and premium office developers are turning to distinctive stone to craft memorable entrances, wellness areas, and dining venues. Designers working on five-star hotels in Dubai, Singapore, and New York specify statement slabs with dramatic veining because natural variance signals exclusivity to guests. Boutique brands extend the same ethos to small properties, boosting demand for rare colors that differentiate from engineered look-alikes, reflecting growth in the marble market.
Health Hazard Related to Marble Dust
Respirable crystalline silica generated during cutting and polishing is under heightened scrutiny after California recorded 127 silicosis cases and 13 fatalities by April 2024, prompting new exposure limits and mandated wet-cutting protocols. Although natural marble contains less than 10% silica, regulators are applying similar controls across all stone operations. Compliance costs include enclosed workstations, high-vacuum extraction, and personal monitoring systems, pressuring small fabricators that lack the capital to upgrade in the marble market.
Other drivers and restraints analyzed in the detailed report include:
- Rising Adoption of Marble Powder as Supplementary Cementitious Material
- Technological Advancements in Extraction and Processing
- Competition from Synthetic Alternatives
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Synthetic grades dominated 80.65% of the marble market in 2025 as industrial resin systems reproduced the look of premium Carrara and Calacatta while providing hardness and stain resistance. The segment is projected to extend leadership at a 4.72% CAGR, supported by home-center channels and accelerated fabrication. Natural marble stays relevant in projects where authenticity and long-term patina outweigh maintenance concerns. Designers of flagship hotels and bespoke residences still specify large blocks for reception desks, staircases, and sculpture. Countries such as Brazil have improved quarry yield through wire saws and drone mapping, bringing new white marble varieties to global showrooms.
White stones captured 36.02% of demand in 2025 and are on track for a 5.60% CAGR through 2031, significantly above the marble market. Designers cite neutrality, light reflectance and association with classical architecture as key reasons for preference, particularly in wellness spas and minimalist corporate lobbies. The marble market size for white varieties is expanding in China and the Gulf, where bright interiors counter hot climates.
Black marbles, led by Nero Marquina, secure orders for contrast features in retail flagships and penthouse kitchens. Yellow, red, and green types cater to regional tastes in the Middle East and parts of Asia, often tied to local cultural symbolism. Multicolored and brecciated stones attract avant-garde architects seeking statement walls. Color choice is increasingly curated through digital twin libraries that allow clients to preview entire slabs at the design stage, reducing uncertainty and waste.
Complete Report Scope:
- By Product Type
- Natural Marble
- Synthetic/Artificial Marble
- By Color
- White
- Black
- Yellow
- Red
- Other Colors
- By Application
- Building and Construction
- Statues and Monuments
- Furniture
- Other Applications (Decorative Infrastructure)
- By End-user Sector
- Residential Buildings
- Commercial and Hospitality
- Industrial and Institutional
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Turkey
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 33.62% of the marble market in 2025 and is forecast to post the highest 6.10% CAGR. India's smart-city roll-out and Indonesia's new capital development add fresh demand for flooring and facade stone. Producers in Vietnam and Pakistan are expanding quarry output to meet regional specifications.
Europe is anchored by Italy and Turkey. Carrara delivers iconic whites, yet waste remains a pain point, with up to 70% of extracted mass discarded as sludge. Regulation and social pressure are catalyzing investment in water recycling, dry shaping, and waste-to-product initiatives such as marble-based 3D printing filament. German and Spanish processors market verified low-emission stone to architects pursuing green certifications.
North America maintains premium pricing and a tight supply of distinctive varieties. Demand centers on luxury residential towers, boutique hotels, and upmarket retail.
South America is emerging as a supply hub, with Brazil's white quartzites and marble winning specifications in US and European projects. The Middle East and Africa show robust demand linked to mega-projects in Saudi Arabia, the United Arab Emirates and South Africa.
- Antolini Luigi & C. S.p.a.
- BC Marble Products Ltd
- Best Cheer Stone Group
- China Kingstone Mining Holdings Limited
- Dimpomar
- Eco Buildings Group Plc
- F.H.L.
- Fox Marble
- HELLENIC GRANITE Co
- Hilltop Stones Pvt. Ltd.
- Kangli stone group
- Levantina y Asociados de Minerales, S.A.
- Mohawk Industries, Inc.
- Mumal Marbles Pvt. Ltd.
- NQ Acrylic and Stone
- Polycor Inc.
- Santucci Group Srl
- TEKMAR MERKEZ OFFICES
- Temmer Marble
- Topalidis S.A.
- UMGG
- XISHI GROUP LTD.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Growth in the Construction Industry
- 4.2.2 Increase in Luxury Real Estate and Infrastructure Projects
- 4.2.3 Rising Adoption of Marble powder as Supplementary Cementitious Material for Low-carbon Concrete
- 4.2.4 Growing Inclination on Marble as a Natural and Sustainable Material
- 4.2.5 Technological Advancements in Extraction and Processing Driving Growth in the Marble Industry
- 4.3 Market Restraints
- 4.3.1 Health Hazard Related to Marble Dust
- 4.3.2 Competition from Synthetic Alternatives
- 4.3.3 Waste Generation and Recycling Challenges
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
- 4.6 Trade Analysis
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Natural Marble
- 5.1.2 Synthetic/Artificial Marble
- 5.2 By Color
- 5.2.1 White
- 5.2.2 Black
- 5.2.3 Yellow
- 5.2.4 Red
- 5.2.5 Other Colors
- 5.3 By Application
- 5.3.1 Building and Construction
- 5.3.2 Statues and Monuments
- 5.3.3 Furniture
- 5.3.4 Other Applications (Decorative Infrastructure)
- 5.4 By End-user Sector
- 5.4.1 Residential Buildings
- 5.4.2 Commercial and Hospitality
- 5.4.3 Industrial and Institutional
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 India
- 5.5.1.3 Japan
- 5.5.1.4 South Korea
- 5.5.1.5 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Turkey
- 5.5.3.6 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle-East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle-East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (Mergers and Acquisitions, Partnerships, Quarry Integration)
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 Antolini Luigi & C. S.p.a.
- 6.4.2 BC Marble Products Ltd
- 6.4.3 Best Cheer Stone Group
- 6.4.4 China Kingstone Mining Holdings Limited
- 6.4.5 Dimpomar
- 6.4.6 Eco Buildings Group Plc
- 6.4.7 F.H.L.
- 6.4.8 Fox Marble
- 6.4.9 HELLENIC GRANITE Co
- 6.4.10 Hilltop Stones Pvt. Ltd.
- 6.4.11 Kangli stone group
- 6.4.12 Levantina y Asociados de Minerales, S.A.
- 6.4.13 Mohawk Industries, Inc.
- 6.4.14 Mumal Marbles Pvt. Ltd.
- 6.4.15 NQ Acrylic and Stone
- 6.4.16 Polycor Inc.
- 6.4.17 Santucci Group Srl
- 6.4.18 TEKMAR MERKEZ OFFICES
- 6.4.19 Temmer Marble
- 6.4.20 Topalidis S.A.
- 6.4.21 UMGG
- 6.4.22 XISHI GROUP LTD.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment
- 7.2 Growing Use of Marble Slabs and Powder

 大理石市場規模、佔有率和成長分析:按產品類型、應用、顏色、最終用途產業、形狀、分銷管道和地區分類-2026-2033年產業預測
 大理石市場:按類型、產品類型、厚度、應用、最終用戶和分銷管道分類-2026-2032年全球市場預測
 2026年全球人造大理石市場報告2026年全球花崗岩和大理石檯面市場報告
 大理石市場規模、佔有率、成長及全球產業分析:按類型、應用和地區的洞察,2026-2034年的預測
 天然石材和大理石市場分析及預測(至2035年):按類型、產品類型、應用、最終用戶、加工方法、技術、形狀、材質、安裝方法和服務分類全球大理石市場規模、佔有率、趨勢和成長分析報告(2026-2034年)2026年全球大理石市場報告
 建築用大理石市場-全球產業規模、佔有率、趨勢、機會、預測:按類型、應用、地區和競爭格局分類,2021-2031年白色天然大理石市場按產品類型、表面處理、應用、最終用途和分銷管道分類,全球預測(2026-2032年)