


 |
市場調查報告書
商品編碼
2123638
以模型為基礎的企業:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Model-based Enterprise - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
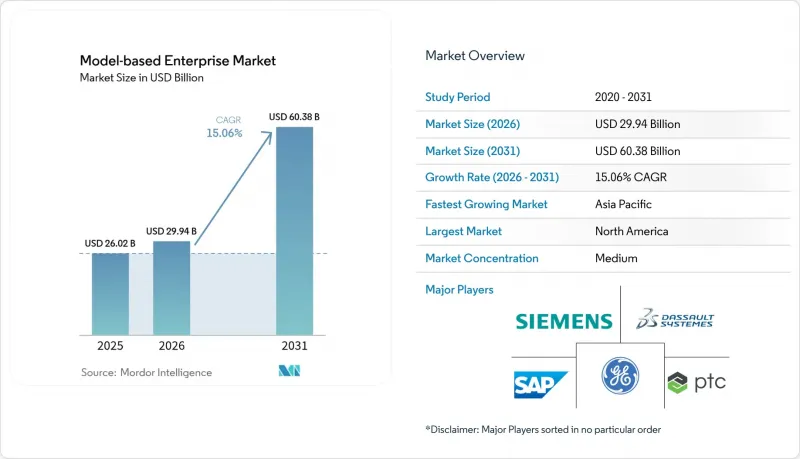
根據 Mordor Intelligence 預測,基於模型的企業市場規模將從 2025 年的 260.2 億美元成長到 2026 年的 299.4 億美元,然後在 2031 年達到 603.8 億美元,2026 年至 2031 年的複合年成長率為 15.06%。
本報告按產品/服務(解決方案和服務)、解決方案類型(PLM軟體、CAD/CAM/CAE及其他)、服務類型(整合和實施、諮詢和培訓及其他)、部署模式(本地部署和雲端部署)、最終用戶產業(航太與國防、建築與基礎設施及其他)以及地區進行細分。市場預測以美元計價。
全球基於模型的企業市場趨勢與洞察
美國國防部 (DoD) 的強制性數位工程計畫正在北美加速推廣。
國防承包商現在必須將3D模型作為其設計、分析、採購和維護決策的唯一資訊來源。近30萬家供應商正在著手更新流程、軟體堆疊和網路安全措施,以確保未來的合約資格。隨著通用分包商適應符合指令要求的工作流程,這一趨勢正蔓延至民用航太領域。工具供應商也積極回應,提供符合規範的打包範本和自動化的基於模型的定義(MBD)檢查器,以縮短文件編制時間並提高可追溯性。
汽車OEM廠商的電動車平台向全3D數位線程過渡
在電池式電動車(BEV)專案中,機械、電氣和熱力系統的並行設計至關重要。統一的3D數位線程的引入,使領先的汽車製造商能夠將平台開發週期從72個月縮短至36個月,同時提高可追溯性。數位孿生和基於模型的系統工程的整合,使團隊能夠在開發早期模擬能量流、碰撞行為和電池劣化,從而降低後期重新設計和保固風險。這些優勢促使該技術在歐洲、北美和中國廣泛應用。
資料互通性的挑戰阻礙了無縫整合。
大約 65% 的工程項目在將傳統 CAD 檔案轉換為功能豐富的 MBD 模型時仍然會遇到延誤。僅進行形態轉換是不夠的;團隊還必須保留數十年來建構的特徵、約束和連結圖紙。雖然專用轉換工具正在不斷改進,但企業級遷移仍然需要大量資源,並且存在資料遺失的風險,這可能會阻礙數位線程的建置。
細分市場分析
到2025年,「解決方案」板塊將佔總收入的70.35%,凸顯其在大多數部署中的核心作用。然而,隨著企業面臨大規模部署基於模型的實踐的複雜性,服務合約的複合年成長率(CAGR)高達17.46%。服務供應商正在採用人工智慧技術來實現資料遷移和檢驗的自動化,從而縮短價值實現時間並提高模型準確性。市場對專注於數位線程技能的培訓和認證計畫的需求日益成長,凸顯了人才持續短缺的問題。專業服務公司的湧現為尋求指導但又不想承擔聘請大規模諮詢團隊成本的中型製造商提供了更多選擇。
隨著訂閱模式的興起,收入來源正從永久授權軟體轉向與績效指標和結果導向合約掛鉤的持續服務關係。將預測分析應用於維護和支援契約,能夠在整合問題中斷生產之前將其檢測出來。這些能力增強了客戶對可信賴合作夥伴的依賴,並支持了服務業在基於模型的企業市場中不斷成長的佔有率。
儘管產品生命週期管理 (PLM) 平台仍然是大多數部署的基礎,但隨著企業對設計和營運之間封閉回路型回饋的需求日益成長,數位孿生和模擬領域正變得越來越重要。將即時感測器數據輸入高精度模型,可以產生自我更新的數位孿生,從而指南維護、最佳化性能並延長資產壽命。模擬和系統工程的融合透過早期檢驗需求來減少返工。這項優勢在航太和醫療設備等高度監管的領域尤為顯著。
視覺化和協作工具現已包含AR/VR疊加功能,可實現身臨其境型設計評審。工程師、供應商甚至現場技術人員可即時查看相同模型,進而縮短決策時間。 CAD/CAM/CAE套件現在可將產品製造資訊直接嵌入3D幾何模型中。這使得下游軟體(包括檢測規劃和現場測量平台)能夠使用單一資料集,從而減少轉換步驟並最大限度地減少因修改而導致的誤差。
區域分析
北美地區在國防費用、成熟的航太供應鏈以及汽車製造商加速推出電動車的推動下,預計到2025年將佔全球收入的37.62%。聯邦政府強制推行數位化模型作為官方技術標準的舉措,正促使即使是較保守的承包商也走向現代化。加拿大和墨西哥透過整合供應鏈參與其中,這些供應鏈要求獲得合規認證,加速了數位化模型在北美大陸的廣泛應用。
亞太地區是成長最快的地區,預計2026年至2031年複合年成長率將達到18.34%。基於雲端的PLM正在降低日本精密設備製造商、韓國電子巨頭和印度工程服務供應商的進入門檻。中國對數位化工廠的投資正在推動龐大生產網路中對可擴展數位線程解決方案的需求。地方政府正在推行智慧製造津貼,加速中小企業進入該領域。
在歐洲,數位孿生技術的應用正穩步推進,這主要得益於德國的「工業4.0」舉措和法國的先進航太計劃。英國位於貝爾法斯特的數位孿生中心體現了該國致力於在下一代飛機研發領域保持競爭力的決心。永續發展法規進一步推動了以模型為中心的設計,這種設計能夠追蹤碳足跡並最佳化資源利用。區域標準化機構正在合作制定互通性框架,從而促進跨境合作。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 美國國防部 (DoD) 的強制性數位工程計畫正在北美加速推廣。
- 汽車OEM廠商正在向電動車平台的全3D數位線程過渡。
- 雲端原生PLM套件的激增使得亞太地區的中小企業能夠採用這些套件。
- 縮短航太維修週轉時間帶來的投資報酬率
- 整合基於模型的定義和積層製造品質工作流程
- 市場限制因素
- 傳統CAD標準與下一代MBD標準之間的資料互通性差距
- 初期階段員工技能再培訓成本較高。
- 雲端採用中的智慧財產權網路安全問題
- 監理展望
- 技術展望
- 波特五力分析
- 宏觀經濟影響分析
第5章 市場規模與成長預測
- 透過提供
- 解決方案
- 服務
- 按解決方案類型
- PLM軟體
- CAD/CAM/CAE
- 數位孿生仿真
- 視覺化與協作
- 按服務類型
- 整合與實施
- 諮詢和培訓
- 支援與維護
- 按實現類型
- 現場
- 雲
- 公共雲端
- 私有雲端
- 混合雲端
- 按最終用戶行業分類
- 航太/國防
- 車
- 建築和基礎設施
- 電力和能源
- 零售與消費品(CPG)
- 電子與高科技
- 海洋/近海
- 其他行業
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 智利
- 秘魯
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 韓國
- 印度
- 澳洲
- 紐西蘭
- 其他亞太國家
- 中東
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 其他非洲地區
- 北美洲
第6章 競爭情勢
- 戰略部署
- 供應商定位分析
- 公司簡介
- Siemens AG
- Dassault Systemes SE
- PTC Inc.
- SAP SE
- Ansys, Inc.
- Autodesk Inc.
- IBM Corporation
- Oracle Corporation
- HCL Technologies Limited
- Aras Corporation
- Anark Corporation
- Hexagon AB
- Altair Engineering Inc.
- Ansys Inc.
- Rockwell Automation Inc.
- IFS AB
- Bentley Systems Inc.
- Capgemini SE
第7章 市場機會與未來展望
According to Mordor Intelligence, the model-based enterprise market size is expected to grow from USD 26.02 billion in 2025 to USD 29.94 billion in 2026 and is forecast to reach USD 60.38 billion by 2031 at 15.06% CAGR over 2026-2031.
This report is Segmented by Offering (Solutions, and Services), Solution Type (PLM Software, CAD/CAM/CAE, and More), Service Type (Integration and Implementation, Consulting and Training, and More), Deployment Mode (On-Premise, and Cloud), End User Industry (Aerospace and Defense, Construction and Infrastructure, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Model-based Enterprise Market Trends and Insights
DoD Digital Engineering Mandates Accelerating Adoption in North America
Defense contractors must now treat 3D models as the single source of truth for design, analysis, sourcing, and sustainment decisions. Close to 300,000 suppliers have started updating processes, software stacks, and cybersecurity safeguards to stay eligible for future contracts. Uptake is spilling over to commercial aerospace as shared subcontractors align with mandate-compliant workflows. Tool vendors are responding with packaged compliance templates and automated model-based definition (MBD) checkers that cut documentation time and enhance traceability.
Automotive OEM Shift to Full-3D Digital Thread for EV Platforms
Battery-electric programs rely on concurrent design of mechanical, electrical, and thermal systems. Deploying a unified 3D digital thread has allowed leading automakers to shrink platform cycles from 72 months to 36 months while improving traceability. The integration of digital twins with model-based systems engineering lets teams simulate energy flow, crash behavior, and battery degradation early, curbing late redesigns and warranty risk. These gains drive widespread rollouts across Europe, North America, and China.
Data-Interoperability Challenges Hinder Seamless Integration
Roughly 65% of engineering projects still encounter delays when transforming historical CAD files into feature-rich, MBD-ready models. Geometry translation alone is not enough; teams must also preserve features, constraints, and linked drawings built over decades. Specialized conversion tools are improving, yet enterprise-wide migrations remain resource intensive and carry risk of data loss that can stall digital-thread initiatives.
Other drivers and restraints analyzed in the detailed report include:
- Surge in Cloud-Native PLM Suites Enabling SMB Access in Asia-Pacific
- ROI From Aerospace MRO Turn-Around-Time Reduction
- Workforce Reskilling Creates Implementation Hurdle
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The Solutions segment generated 70.35% of 2025 revenue, underscoring its role as the backbone of most deployments. Service engagements, however, are registering a 17.46% CAGR as enterprises confront the complexity of rolling out model-based practices at scale. Service providers are embedding AI to automate data migration and validation, shortening time-to-value and boosting confidence in model accuracy. Training and certification packages focused on digital-thread skills are rising in demand, highlighting the persistent talent gap. The influx of specialized service firms is broadening options for mid-market manufacturers seeking guidance without the expense of large consulting teams.
Rising subscription models are shifting revenue from perpetual software toward continuous service relationships tied to performance metrics and outcome-based contracts. Predictive analytics applied within maintenance and support agreements can flag integration glitches before they disrupt production. These capabilities reinforce client reliance on trusted partners, sustaining the upward trajectory of the Services share within the model-based enterprise market.
Product-lifecycle-management platforms remain the foundation of most implementations, but the Digital-Twin & Simulation segment is gaining prominence as organizations seek closed-loop feedback between design and operation. Real-time sensor data feeding high-fidelity models creates self-updating digital twins that guide maintenance, optimize performance, and extend asset life. The convergence of simulation and systems engineering reduces rework by validating requirements early, a benefit that is especially acute in regulated domains such as aerospace and medical devices.
Visualization and collaboration tools are adding AR/VR overlays to facilitate immersive design reviews. Engineers, suppliers, and even field technicians can inspect the same model in real time, shrinking the decision window. CAD/CAM/CAE suites now embed product-manufacturing information directly in 3D geometry. This allows downstream software, including inspection planning and shop-floor metrology platforms, to consume a single data set, trimming translation steps and minimizing revision errors.
Complete Report Scope:
- By Offering
- Solutions
- Services
- By Solution Type
- PLM Software
- CAD/CAM/CAE
- Digital-Twin and Simulation
- Visualization and Collaboration
- By Service Type
- Integration and Implementation
- Consulting and Training
- Support and Maintenance
- By Deployment Mode
- On-premise
- Cloud
- Public Cloud
- Private Cloud
- Hybrid Cloud
- By End User Industry
- Aerospace and Defense
- Automotive
- Construction and Infrastructure
- Power and Energy
- Retail and CPG
- Electronics and Hi-Tech
- Marine and Offshore
- Other Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Peru
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Australia
- New Zealand
- Rest of Asia-Pacific
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- North America
Geography Analysis
North America contributed 37.62% of 2025 revenue, supported by defense spending, a mature aerospace supply chain, and automakers seeking to accelerate electric-vehicle launches. Federal policies that enforce digital models as the official technical baseline are nudging even conservative contractors to modernize. Canada and Mexico participate through integrated supply chains that must also prove compliance, driving widespread adoption across the continent.
Asia-Pacific is the fastest-growing region with an 18.34% CAGR over 2026-2031. Cloud-hosted PLM lowers entry barriers for Japan's precision manufacturers, South Korea's electronics champions, and India's engineering-services providers. China's investment in digital factories fuels demand for digital-thread solutions that can scale across vast production networks. Local governments promote smart-manufacturing grants, accelerating SMB participation.
Europe maintains robust adoption driven by Germany's Industrie 4.0 initiatives and France's advanced aerospace programs. A United Kingdom digital-twin center in Belfast demonstrates national commitment to remain competitive in next-generation aircraft development. Sustainability regulations further encourage model-centric design to track carbon footprints and optimize resource use. Regional standards bodies collaborate on interoperability frameworks, smoothing cross-border collaboration.
- Siemens AG
- Dassault Systemes SE
- PTC Inc.
- SAP SE
- Ansys, Inc.
- Autodesk Inc.
- IBM Corporation
- Oracle Corporation
- HCL Technologies Limited
- Aras Corporation
- Anark Corporation
- Hexagon AB
- Altair Engineering Inc.
- Ansys Inc.
- Rockwell Automation Inc.
- IFS AB
- Bentley Systems Inc.
- Capgemini SE
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 DoD Digital Engineering Mandates Accelerating Adoption in North America
- 4.2.2 Automotive OEM Shift to Full-3D Digital Thread for EV Platforms
- 4.2.3 Surge in Cloud-Native PLM Suites Enabling SMB Access in Asia-Pacific
- 4.2.4 ROI From Aerospace MRO Turn-Around Time Reduction
- 4.2.5 Integrating Model-Based Definition with Additive-Manufacturing Quality Workflows
- 4.3 Market Restraints
- 4.3.1 Data-Interoperability Gaps Between Legacy CAD and Next-Gen MBD Standards
- 4.3.2 High Up-Front Workforce Reskilling Costs
- 4.3.3 Cyber-security Concerns Over IP in Cloud Deployments
- 4.4 Regulatory Outlook
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers/Consumers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
- 4.7 Macroeconomic Impact Analysis
5 Market Size and Growth Forecasts (Value)
- 5.1 By Offering
- 5.1.1 Solutions
- 5.1.2 Services
- 5.2 By Solution Type
- 5.2.1 PLM Software
- 5.2.2 CAD/CAM/CAE
- 5.2.3 Digital-Twin and Simulation
- 5.2.4 Visualization and Collaboration
- 5.3 By Service Type
- 5.3.1 Integration and Implementation
- 5.3.2 Consulting and Training
- 5.3.3 Support and Maintenance
- 5.4 By Deployment Mode
- 5.4.1 On-premise
- 5.4.2 Cloud
- 5.4.2.1 Public Cloud
- 5.4.2.2 Private Cloud
- 5.4.2.3 Hybrid Cloud
- 5.5 By End User Industry
- 5.5.1 Aerospace and Defense
- 5.5.2 Automotive
- 5.5.3 Construction and Infrastructure
- 5.5.4 Power and Energy
- 5.5.5 Retail and CPG
- 5.5.6 Electronics and Hi-Tech
- 5.5.7 Marine and Offshore
- 5.5.8 Other Industries
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Chile
- 5.6.2.4 Peru
- 5.6.2.5 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 South Korea
- 5.6.4.4 India
- 5.6.4.5 Australia
- 5.6.4.6 New Zealand
- 5.6.4.7 Rest of Asia-Pacific
- 5.6.5 Middle East
- 5.6.5.1 United Arab Emirates
- 5.6.5.2 Saudi Arabia
- 5.6.5.3 Turkey
- 5.6.5.4 Rest of Middle East
- 5.6.6 Africa
- 5.6.6.1 South Africa
- 5.6.6.2 Rest of Africa
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Strategic Developments
- 6.2 Vendor Positioning Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.3.1 Siemens AG
- 6.3.2 Dassault Systemes SE
- 6.3.3 PTC Inc.
- 6.3.4 SAP SE
- 6.3.5 Ansys, Inc.
- 6.3.6 Autodesk Inc.
- 6.3.7 IBM Corporation
- 6.3.8 Oracle Corporation
- 6.3.9 HCL Technologies Limited
- 6.3.10 Aras Corporation
- 6.3.11 Anark Corporation
- 6.3.12 Hexagon AB
- 6.3.13 Altair Engineering Inc.
- 6.3.14 Ansys Inc.
- 6.3.15 Rockwell Automation Inc.
- 6.3.16 IFS AB
- 6.3.17 Bentley Systems Inc.
- 6.3.18 Capgemini SE
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment


