


 |
市場調查報告書
商品編碼
2123510
智慧插座:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Smart Plug - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
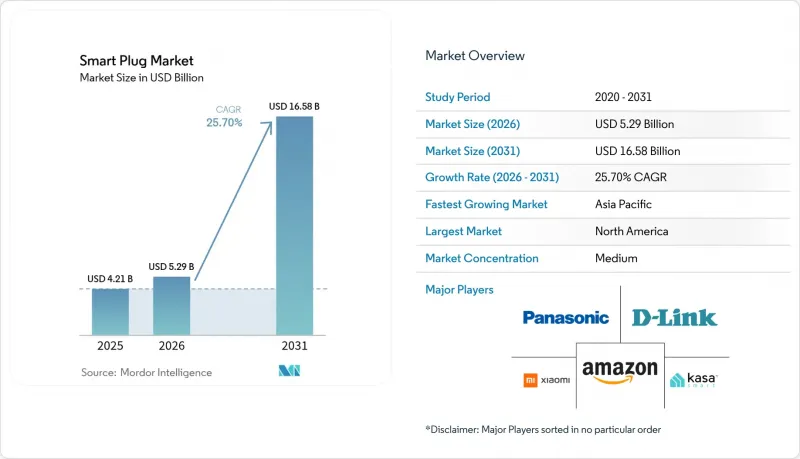
根據 Mordor Intelligence 估計,智慧插座市場在 2026 年的價值將達到 52.9 億美元,高於 2025 年的 42.1 億美元,預計到 2031 年將達到 165.8 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 25.70%。
本報告按技術(藍牙、Wi-Fi 等)、應用(住宅、商用等)、銷售管道(線上和線下)、插頭類型(牆壁插座適配器、牆壁插座等)和地區進行細分。市場預測以美元計價。
全球智慧插座市場趨勢及洞察
語音助理生態系統正在迅速擴展。
根據亞馬遜的報告,語音控制已從新奇事物轉變為必需品,印度連網智慧家居設備的數量在三年內激增了200%。每月收費19.99美元的生成式人工智慧服務Alexa+將於2025年與Prime會員捆綁銷售,它將重新定義智慧家庭的價值提案,從簡單的開關控制擴展到能夠協調多個設備的場景控制。訂閱經濟促進了用戶更深入的參與,並將智慧插座定位為基礎節點,從而將語音助理的功能擴展到傳統家用電器。 Alexa目錄中列出了超過14萬種相容設備,網路效應正在降低普及門檻,並提高各個收入階層的普及率。谷歌和蘋果的類似策略也強化了這樣一種認知:語音控制如今已成為所有新型插電設備的基本功能。
Wi-Fi晶片組的平均售價(ASP)正在下降。
Silicon Labs 的 SiWx917 MCU 將連接時的睡眠電流降低至 22 微安培,從而降低了組件成本,使其零售價低於 15 美元,且不影響能耗報告功能。 Synaptics 和中國新興企業AIC Micro 正在進軍價值 32 億美元的超低功耗物聯網 SoC 市場,加劇了價格競爭,並擴大了供應商選擇範圍。大規模生產使得 ODM 廠商能夠將 Wi-Fi/BLE 雙模組整合機殼,同時保持 Matter韌體的支援。新興市場受益最大,單價優勢使得中等收入家庭也能負擔得起,從而擴大了用戶群體,使其不再局限於早期用戶。
設備持續遭受網路安全漏洞攻擊
預計到2024年,針對智慧型裝置的網路攻擊將增加一倍以上,隨著各大品牌的高調漏洞曝光,消費者信心正在受到侵蝕。 TP-Link本地通訊漏洞的發現以及導致27億條物聯網記錄外洩的Mars Hydro事件,凸顯了系統性風險。由亞馬遜和谷歌支持的美國聯邦通訊委員會(FCC)推出的全新「網路信任標誌」(CyberTrust Mark)承諾提供更清晰的標籤,但最終規則尚未實施。例如,Emporia Energy因存在觸電風險而召回8萬個智慧插頭的案例,清楚地表明了安全措施不足造成的經濟損失。在認證強制執行之前,持續存在的擔憂可能會阻礙消費者的首次購買,尤其是在擁有嚴格IT政策的專業管理機構中。
細分市場分析
到2025年,藍牙仍將以31.12%的市場佔有率在智慧插座市場保持領先地位,而Zigbee/Thread協議則在Matter認證技術的推動下,以26.15%的複合年成長率快速成長。 Thread 1.4版本增強的認證資訊共用功能將支援企業級部署,預計將推動支援Thread技術的智慧插座市場快速擴張。塗鴉智慧的15天承包模組專案表明,標準化如何縮短產品上市時間並降低工程難度。 Wi-Fi因其成本優勢而被廣泛採用,並在高解析度能量測量等頻寬密集型應用情境中表現出色,而Z-Wave在美國的傳統安防系統中仍佔據穩固地位。隨著消費者對跨平台購買保障的需求日益成長,專有標準協定棧面臨被淘汰的風險。
Thread 的即時能源報告功能在公用事業需量反應方面具有顯著優勢。透過 Matter 1.3,智慧插座現在可以將即時能耗資料傳送到更廣泛的家庭能源管理儀表板。因此,支持 Thread 的硬體開始被納入公用事業公司的補貼計劃,獎勵安裝商放棄僅支援 Wi-Fi 的產品。供應商可以利用 Thread 的低延遲網狀網路提供能源分析功能,從而設定更高的平均售價 (ASP),緩解日益同質化的市場中利潤率下降的困境。
受語音助理套裝和便利的DIY安裝方式的推動,住宅市場預計到2025年仍將佔據智慧插座市場55.74%的佔有率。然而,隨著設施管理人員追求可量化的投資回報,工業和商業建築市場預計將以27.05%的複合年成長率成長。實地研究表明,應用基於物聯網的調度技術每年每個場所可減少36.8千瓦的插座負載。Honeywell面向企業建築管理系統的插座負載模組,標誌著能源監管合規正朝著數據驅動的方向發展。
在工廠和倉庫中,工業級智慧插座配備專用外殼,並具備住宅產品所不具備的過熱保護和過流分析功能。醫院和養老機構正在部署智慧插座,以監控醫療設備的運作並防止意外斷電,同時政府也為老齡化社會中的遠端監控提供補貼計畫。隨著商業性對受服務等級協定 (SLA) 保障的硬體需求不斷成長,價格更高的產品也越來越受歡迎,從而擴大了智慧插座面向專業 OEM 製造商的整體潛在市場規模。
區域分析
北美地區在2025年仍維持31.74%的市場佔有率,這主要得益於能源之星智慧家庭能源管理系統(SHEMS)法規和寬頻普及率的提升。該地區公用事業公司為購買經需量反應認證的插座提供補貼。此外,語音助理在該地區日益普及,有助於增強生態系統的穩定性,降低客戶流失率,並促進全住宅維修。加拿大修訂後的能源效率法規與美國標準接軌,為製造商提供了統一的北美認證藍圖。
亞太地區預計將以27.60%的複合年成長率成長,成為智慧插座市場成長最快的地區。在印度,自2022年以來,支援Alexa的裝置數量增加了兩倍,這主要得益於在地化的語音助理和具有競爭力的價格。中國本土晶片組生產穩定了物料清單(BOM)的波動,並促進了白牌產品的普及。在日本和韓國,政府資助的智慧城市試點計畫正在將插電式能源監測整合到區域碳排放儀錶板中,為機構對Thread網狀網路部署的需求奠定了基礎。
歐洲的情況錯綜複雜。 WEEE指令2024/884要求製造商承擔全部報廢成本,這給毛利率帶來了壓力。同時,英國2025年的智慧家電法規強制要求與電網相容,擴大了可受惠於Matter智慧插座維修的設備範圍。塗鴉智慧在倫敦舉辦的維修論壇強調了低成本插座在老舊住宅存量實現淨零排放目標方面所發揮的作用。
儘管南美洲、中東和非洲在部署數量上落後於其他地區,但5G的部署已顯著降低了延遲並擴大了覆蓋範圍,從而實現了兩位數的成長。高額進口關稅仍是一大障礙,促使當地企業利用區域自由貿易區進行組裝合資計畫。開發商已與海灣合作理事會(GCC)的連鎖飯店合作,並試行集中式能源控制面板,這表明智慧插座是通往更廣泛的物聯網基礎設施的門戶產品。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 語音助理生態系統正在迅速擴展。
- Wi-Fi晶片組的平均售價(ASP)正在下降。
- 政府關於插電負載控制的節能指令
- 第 1.3 項 促進互通性
- 老年人護理遠端監測津貼計劃
- 對耐候型戶外插頭的需求日益成長
- 市場限制因素
- 設備持續遭受網路安全漏洞攻擊
- 新興市場的射頻頻段細分
- 歐盟廢棄電子電氣設備回收成本給利潤率帶來了壓力。
- 召回原因是能量測量不準確。
- 供應鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 供應商的議價能力
- 買方的議價能力
- 新進入者的威脅
- 替代品的威脅
- 競爭公司之間的競爭
- 對與市場相關的宏觀經濟趨勢進行評估
第5章 市場規模與成長預測
- 透過技術
- Wi-Fi
- Bluetooth
- Zigbee/Thread
- Z-Wave
- 其他
- 透過使用
- 住宅
- 商業
- 產業
- 其他(旅館業、醫療保健業)
- 按銷售管道
- 線上
- 離線
- 插頭外形規格
- 牆插轉接器
- 牆壁安裝式電源插座
- 電源分接頭
- 其他
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 韓國
- 印度
- 其他亞太國家
- 中東和非洲
- GCC
- 土耳其
- 南非
- 其他中東和非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- TP-Link Technologies
- Belkin(WeMo)
- Xiaomi
- D-Link
- Panasonic
- Amazon(First-Party)
- Broadlink
- Ankuoo
- EDIMAX
- Vesync(Etekcity, Levoit, Cosori)
- Lenovo
- Leviton
- Wipro
- Sariana(Satechi)
- Sonoff(ITEAD)
- Shelly
- Gosund/Nooie
- Eve Systems
- Aeotec
- Sengled
- Wyze Labs
第7章 市場機會與未來展望
According to Mordor Intelligence, the smart plug market size in 2026 is estimated at USD 5.29 billion, growing from 2025 value of USD 4.21 billion with 2031 projections showing USD 16.58 billion, growing at 25.70% CAGR over 2026-2031.
This report is Segmented by Technology (Bluetooth, Wi-Fi, and More), Application (Residential, Commercial, and More), Sales Channel (Online and Offline), Plug Form Factor (Wall-Plug Adapter, In-Wall Outlet, and More), and by Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Smart Plug Market Trends and Insights
Soaring Adoption of Voice-Assistant Ecosystems
Voice control has shifted from novelty to necessity as Amazon reports a 200% jump in connected smart-home devices in India within three years. The 2025 debut of the USD 19.99-per-month Alexa+ generative-AI service, bundled into Prime, redefines the value proposition from simple on/off switching to multi-device scene orchestration. Subscription economics incentivize deeper engagement, positioning smart plugs as foundational nodes that extend voice-assistant reach to legacy appliances. With more than 140,000 compatible devices in the Alexa catalogue, network effects reduce adoption friction and lift attach rates across income bands. Comparable strategies from Google and Apple reinforce the perception that voice-ready control is now the baseline expectation for every new plug-in device.
Falling ASPs of Wi-Fi Chipsets
Silicon Labs' SiWx917 MCU trims connected-sleep current to 22 micro amp, slicing component costs and enabling sub-USD 15 retail pricing without sacrificing energy reporting features. Synaptics and Chinese newcomer AIC Micro have entered the USD 3.2 billion ultra-low-power IoT SoC arena, intensifying price competition and widening vendor choice. Mass-market volumes allow ODMs to package dual Wi-Fi/BLE modules inside compact casings while retaining Matter-ready firmware. Emerging economies benefit most, as unit economics now align with middle-income household budgets, expanding the install base beyond early adopters.
Persistent Device Cybersecurity Breaches
Smart-device cyberattacks more than doubled in 2024, eroding consumer trust as high-profile flaws surfaced in major brands. TP-Link's exposure of local-communication vulnerabilities and the Mars Hydro incident that leaked 2.7 billion IoT records underscore systemic risk. The U.S. FCC's upcoming Cyber Trust Mark, backed by Amazon and Google, promises clearer labeling but final rules are not yet in force. Product recalls such as Emporia Energy's withdrawal of 80,000 smart plugs due to shock hazards illustrate the financial toll of insufficient security controls. Until certification regimes become mandatory, lingering doubts may slow first-time purchases, especially in professionally managed facilities with stricter IT policies.
Other drivers and restraints analyzed in the detailed report include:
- Government Energy-Efficiency Mandates for Plug-Load Control
- Matter 1.3 Interoperability Push
- Fragmented RF Spectrum in Emerging Markets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Bluetooth retained the largest 31.12% slice of smart plug market share in 2025, but Zigbee/Thread protocols are accelerating at a 26.15% CAGR on the back of Matter certification momentum. The smart plug market size for Thread-enabled models is projected to swell sharply as enhanced credential-sharing in Thread 1.4 unlocks enterprise-grade deployments. Tuya's 15-day turnkey module program signals how standardization compresses time-to-market and lowers engineering hurdles. Wi-Fi enjoys cost-led ubiquity and excels in bandwidth-heavy use-cases such as high-resolution energy metering, while Z-Wave remains entrenched in legacy US security systems. Proprietary stacks risk obsolescence as consumers align around cross-platform purchase assurance.
Thread's real-time energy-reporting offers clear advantages in utility demand-response. Matter 1.3 now lets smart plugs feed instantaneous consumption data to broader home-energy-management dashboards. Consequently, utility rebates are beginning to single out Thread-capable hardware, incentivizing installers to pivot away from Wi-Fi-only SKUs. Vendors that overlay energy analytics atop Thread's low-latency mesh can charge premium ASPs, cushioning margin erosion in a commoditizing category.
Residential premises still represent 55.74% of the 2025 smart plug market size, buoyed by voice-assistant bundling and DIY convenience. Yet industrial and commercial buildings are set to expand at a 27.05% CAGR as facility managers chase quantified returns; field studies show 36.8 kW of annual plug-load savings per site when IoT scheduling is applied. Honeywell's plug-load module for enterprise building-management systems exemplifies the pivot to data-driven energy compliance.
In factories and warehouses, skinned industrial-grade smart plugs add thermal-overload protection and over-current analytics that residential units lack. Hospitals and elder-care facilities deploy smart plugs to verify medical-device uptime and prevent unplanned disconnection, aided by subsidy programs for remote monitoring in aging societies. The commercial appetite for SLA-backed hardware supports higher price points, widening the total addressable smart plug market for specialist OEMs.
Complete Report Scope:
- By Technology
- Wi-Fi
- Bluetooth
- Zigbee / Thread
- Z-Wave
- Others
- By Application
- Residential
- Commercial
- Industrial
- Others (Hospitality, Healthcare)
- By Sales Channel
- Online
- Offline
- By Plug Form Factor
- Wall-Plug Adapter
- In-Wall Outlet
- Power Strip
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- Turkey
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
North America retained 31.74% leadership in 2025 on the strength of Energy Star SHEMS rules and broadband ubiquity, with utilities offering rebates for demand-response-certified plugs. The region's mature voice-assistant penetration fosters ecosystem lock-in that reduces churn and encourages whole-home retrofits. Canada's updated Energy Efficiency Regulations mirror U.S. standards, giving manufacturers a unified North American certification roadmap.
Asia Pacific is projected to clock a 27.60% CAGR, making it the fastest-expanding territory of the smart plug market. Localized voice-assistant dialect support and competitive pricing have tripled the Alexa device count in India since 2022. China's domestic chipset output curbs BOM volatility and allows white-label brands to proliferate. Government-funded smart-city pilots in Japan and South Korea integrate plug-level energy monitoring into district-wide carbon dashboards, seeding institutional demand for Thread-mesh deployments.
Europe presents a mixed picture. WEEE Directive 2024/884 places full end-of-life costs on manufacturers, pressuring gross margins. Conversely, the UK's 2025 smart-appliance rules require grid-aware functionality, widening the pool of devices that can benefit from retrofitting with Matter-ready smart plugs. Tuya's London retrofit forum underscored the role that low-cost plugs play in hitting net-zero targets for aging housing stock.
South America and the Middle East-Africa trail in installed base but register double-digit growth as 5G rollouts improve latency and coverage. High import duties remain a hurdle, prompting local assembly joint ventures that leverage regional free-trade zones. Developers tapped into hotel chains in the Gulf Cooperation Council to trial centralized energy dashboards, illustrating how smart plugs serve as a gateway product for broader IoT infrastructure.
- TP-Link Technologies
- Belkin (WeMo)
- Xiaomi
- D-Link
- Panasonic
- Amazon (First-Party)
- Broadlink
- Ankuoo
- EDIMAX
- Vesync (Etekcity, Levoit, Cosori)
- Lenovo
- Leviton
- Wipro
- Sariana (Satechi)
- Sonoff (ITEAD)
- Shelly
- Gosund / Nooie
- Eve Systems
- Aeotec
- Sengled
- Wyze Labs
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Soaring adoption of voice-assistant ecosystems
- 4.2.2 Falling ASPs of Wi-Fi chipsets
- 4.2.3 Government energy-efficiency mandates for plug-load control
- 4.2.4 Matter 1.3 interoperability push
- 4.2.5 Subsidy programs for senior-care tele-monitoring
- 4.2.6 Rising demand for outdoor weather-proof plugs
- 4.3 Market Restraints
- 4.3.1 Persistent device cybersecurity breaches
- 4.3.2 Fragmented RF spectrum in emerging markets
- 4.3.3 EU WEEE recycling costs hitting margins
- 4.3.4 Inaccurate energy-metering claims triggering recalls
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Force Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Assesment of Macroeconomic Trends on Market
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Technology
- 5.1.1 Wi-Fi
- 5.1.2 Bluetooth
- 5.1.3 Zigbee / Thread
- 5.1.4 Z-Wave
- 5.1.5 Others
- 5.2 By Application
- 5.2.1 Residential
- 5.2.2 Commercial
- 5.2.3 Industrial
- 5.2.4 Others (Hospitality, Healthcare)
- 5.3 By Sales Channel
- 5.3.1 Online
- 5.3.2 Offline
- 5.4 By Plug Form Factor
- 5.4.1 Wall-Plug Adapter
- 5.4.2 In-Wall Outlet
- 5.4.3 Power Strip
- 5.4.4 Others
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 South Korea
- 5.5.4.4 India
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 GCC
- 5.5.5.2 Turkey
- 5.5.5.3 South Africa
- 5.5.5.4 Rest of Middle East and Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 TP-Link Technologies
- 6.4.2 Belkin (WeMo)
- 6.4.3 Xiaomi
- 6.4.4 D-Link
- 6.4.5 Panasonic
- 6.4.6 Amazon (First-Party)
- 6.4.7 Broadlink
- 6.4.8 Ankuoo
- 6.4.9 EDIMAX
- 6.4.10 Vesync (Etekcity, Levoit, Cosori)
- 6.4.11 Lenovo
- 6.4.12 Leviton
- 6.4.13 Wipro
- 6.4.14 Sariana (Satechi)
- 6.4.15 Sonoff (ITEAD)
- 6.4.16 Shelly
- 6.4.17 Gosund / Nooie
- 6.4.18 Eve Systems
- 6.4.19 Aeotec
- 6.4.20 Sengled
- 6.4.21 Wyze Labs
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment


