


 |
市場調查報告書
商品編碼
2123416
塑膠薄膜:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Plastic Film - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
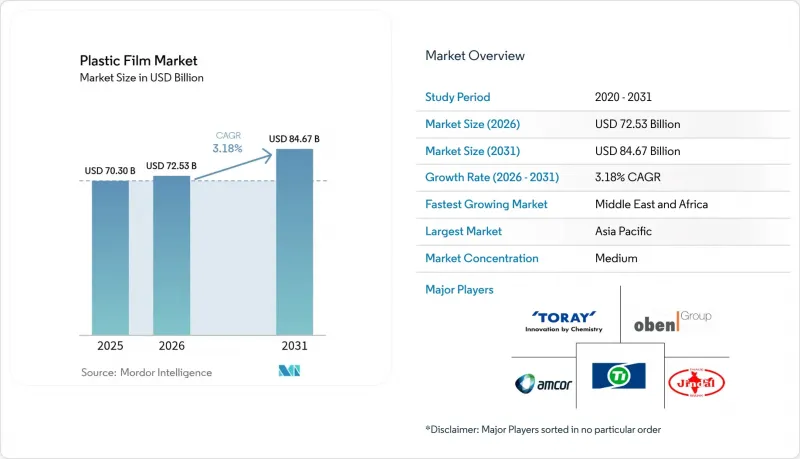
根據 Mordor Intelligence 預測,塑膠薄膜市場規模將從 2025 年的 703 億美元成長到 2026 年的 725.3 億美元,然後在 2031 年達到 846.7 億美元,2026 年至 2031 年的複合年成長率為 3.18%。
本報告按樹脂類型(聚丙烯、聚乙烯、雙向拉伸聚酯薄膜、聚苯乙烯、生質塑膠等)、應用(包裝和重疊、包裝袋和襯裡等)、薄膜功能(低阻隔單層材料、中阻隔金屬化薄膜等)、終端用戶行業(食品、飲料、醫療保健和製藥等)以及地區進行細分。市場預測以美元計價。
全球塑膠薄膜市場趨勢與洞察
消費者轉向單一材料、可回收的薄膜結構
在循環經濟政策的推動下,傳統的多層結構正迅速轉型為符合回收標準且性能不受影響的單層薄膜。歐洲法規要求在2030年實現完全可回收,這促使像Uzel Plastik這樣的加工商開發出無需粘合層黏合劑且保持氧氣阻隔性的聚乙烯寵物食品薄膜。品牌所有者正透過與永續發展指標掛鉤的多年供應合約來獎勵早期採用者,但對新型擠出和黏合系統的初始投資正在對短期利潤率造成壓力。製藥業也在加速這項轉型。 Klockner Pentaplast推出了單層吸塑包裝薄膜,簡化了下游回收流程,同時滿足嚴格的醫療合規要求。預計這一趨勢將使單層薄膜的市佔率從2024年的60%成長到2030年的三分之二。
由於相關法規,可生物分解和可堆肥薄膜的使用量增加。
在錯綜複雜的州和國家法規體系下,對經認證的可堆肥薄膜的需求正在成長,尤其是在餐飲服務和農產品包裝領域。華盛頓州的標籤和設施認證規則制定了全球供應商必須遵守的技術標準。明尼蘇達州強制要求遵守工業堆肥標準的法律也影響超級市場連鎖店的自有品牌規格。像DNP集團這樣擁有雄厚研發預算的供應商正在將多層可堆肥薄膜商業化,這種薄膜可在90天內分解,同時保持良好的氣體阻隔性能,從而保護零嘴零食。缺乏全球統一的標準仍然是一個障礙,迫使加工商在每個國家生產不同的SKU,導致合規成本增加。
聚烯和PET原料價格波動
PET和LDPE現貨價格每季波動15-20%,對加工商的價差帶來壓力,尤其是對非一體化企業而言。根據ChemOrbis的數據,預計2024年PET價格將在每噸1200美元至1450美元之間波動,這使得依賴現貨樹脂的供應商簽訂長期合約風險較高。亞洲BOPET市場的供應過剩已將售價推至歷史低點。 Firsta集團曾出現利潤率低於印度盧比/公斤的情況,迫使工廠暫時停產。運輸時間延長進一步加劇了庫存管理的複雜性,迫使小型加工商在價格下跌時承擔損失。
細分市場分析
聚乙烯採用茂金屬觸媒技術,可在不影響剛性和透明度的前提下,將薄膜厚度降低高達20%,預計2025年將佔銷售量的39.12%。這項優勢確保了即使在原油價格飆升的情況下,也能維持穩定的現金流。相較之下,生質塑膠雖然基準小規模,但隨著品牌商試用可堆肥包裝材料以達到其ESG目標,預計其複合年成長率將達到5.87%。包括甘蔗渣和藻類油在內的第二代原料供應量的增加,正在縮小生物塑膠與傳統樹脂之間的成本溢價。然而,由於水解穩定性方面的局限性,大多數生質塑膠仍然不適用於需要阻隔性的醫療和電子應用。
有意進軍生質塑膠領域的加工商正與樹脂新創公司洽談多年期外包協議,以避免價格波動風險。區域集群,尤其是歐盟和北美堆肥設施周邊的集群,也影響工廠的位置決策。聚丙烯憑藉其耐熱性和阻隔性,在殺菌袋應用領域持續擴大市場佔有率。同時,雙向拉伸聚酯薄膜(BOPET)生產商正尋求在美國等市場獲得反傾銷保護,以避免亞洲市場供應過剩。特種聚合物,例如環烯烴共聚物(COC),在醫療診斷領域扮演獨特的角色,凸顯了性能主導差異化在塑膠薄膜市場的重要性。
預計到2025年,袋裝包裝將佔總銷售額的47.95%,這主要得益於其便於分量控制和密封強度高,能夠減少食物廢棄物。袋裝包裝的形狀非常適合休閒食品和寵物食品工廠常見的自動化成型、灌裝和封口生產線,而數位印刷技術則可實現高度客製化的圖案,滿足短期宣傳活動的需求。同時,由於全通路食品銷售和食材自煮包服務對耐穿刺薄膜的需求不斷成長,預計保鮮膜和重疊膜的複合年成長率將達到4.56%,這些薄膜需與高速裝袋機器人相容。為了滿足冷鏈要求,市場對即使在零下溫度下也能保持延展性的防潮層的需求日益成長,而基於雙向拉伸聚丙烯(BOPP)的複合材料最近在該領域備受關注。
加工商正在將資料矩陣碼整合到二級包裝薄膜中,以追蹤最後一公里配送,從而在材料銷售之外,透過資料分析創造新的收入來源。無底紙標籤薄膜和多件裝收縮商品搭售仍然很重要,但由於碳酸飲料市場的成熟,其成長速度正在放緩。在所有應用領域,資源高效的薄膜形式,例如可調節透氣性的穿孔農業包裝薄膜,都符合零售商的永續性,因此即使價格較高,也能確保貨架空間。
區域分析
亞太地區憑藉著規模經濟和快速成長的國內消費,預計到2025年將佔據塑膠薄膜市場37.98%的佔有率。中國在雙向拉伸聚酯薄膜(BOPET)和雙向拉伸聚丙烯薄膜(BOPP)市場保持領先地位,但其新增產能每年超過國內需求約26萬噸,這給中型加工商的利潤率帶來壓力,並加速了中型加工商之間的併購活動。印度正利用茂金屬觸媒技術改進軟包裝袋的形狀,並快速部署新的BOPP生產線。日本成熟且技術高度發展的產業生態系統正在支持光學薄膜和電池隔膜的創新。
北美市場需求更為穩定,這得益於製造業回流趨勢以及推動電子商務使用可再生聚乙烯包裝的永續性法規。 Polyplex在阿拉巴馬州投資1億美元擴大PET薄膜生產線,體現了區域供應鏈在貿易政策確定性下的吸引力。加工商擴大位置靠近物流樞紐的地點,以縮短前置作業時間,這對於食材自煮包和藥品的運輸至關重要。
歐洲繼續發揮政策標竿的作用。生產者延伸責任制(EPR)對不可回收材料徵收費用,刺激了研發投入,以推動單一材料的研發。機械回收能力正在提升,創投基金也支持混合硬質和軟質材料的化學回收試點計畫。
在中東和非洲地區,預計到2031年,年複合成長率將達到7.86%,這主要得益於進口替代計畫和監管獎勵。在埃及,一項投資5,480萬美元建造再生聚酯纖維生產線的合資計畫表明,當地對循環解決方案的需求日益成長。波灣合作理事會(GCC)成員國正利用其碳氫化合物產業的整合優勢,以具競爭力的價格供應聚乙烯(PE),並創建下游薄膜產業叢集,力求滿足區域糧食安全計畫的需求。雖然撒哈拉以南非洲的需求成長主要受人口成長和日常消費品激增的推動,但廢棄物管理基礎設施的不平衡可能會阻礙高品質、永續薄膜的普及應用。
在南美洲,隨著專注於品牌食品和個人保健產品的跨國公司將零售業務拓展至農村地區,包裝需求增加,預計南美將實現中等個位數的成長。貨幣波動和南方共同市場成員國之間的監管差異使生產力計畫規劃變得複雜,但家庭收入的成長使基本消費保持穩定。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 消費者偏好轉向單一材料、可回收的薄膜結構。
- 由於相關法規,可生物分解和可堆肥薄膜的使用量增加。
- 醫療和電子包裝產業對高阻隔薄膜的需求不斷成長。
- 擴大農業薄膜在垂直農業和溫室自動化的應用。
- 利用先進的茂金屬催化劑實現薄膜減薄。
- 該地區電子商務冷鏈需求的激增,帶動了對特種薄膜需求的成長。
- 市場限制因素
- 聚烯和PET原料價格波動
- 新興國家嚴格禁止使用一次性塑膠製品
- 醫用級PVC樹脂供應緊張
- 同步雙軸延伸線的資本密集度
- 產業價值鏈分析
- 波特五力分析
- 宏觀經濟因素對市場的影響
第5章 市場規模與成長預測
- 依樹脂類型
- 聚丙烯(PP)
- 聚乙烯(PE)
- 聚對苯二甲酸乙二醇酯(BOPET)
- 聚苯乙烯(OPS)
- 生質塑膠
- 其他材料類型
- 透過使用
- 包裝和重疊
- 袋裝和襯裡
- 小袋
- 其他用途
- 薄膜的功能特性
- 低阻隔單材料薄膜
- 中等阻隔性金屬沉澱膜
- 高阻隔多層膜
- 特殊功能薄膜和抗菌薄膜
- 按最終用途行業分類
- 食物
- 糖果和糖果甜點
- 冷凍食品
- 生鮮食品
- 乳製品
- 肉類、雞肉、魚貝類
- 寵物食品
- 其他食物
- 飲料
- 醫療和藥品
- 個人護理和居家護理
- 工業包裝
- 其他終端用戶產業
- 食物
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 智利
- 其他南美國家
- 歐洲
- 英國
- 德國
- 法國
- 西班牙
- 義大利
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 越南
- 其他亞太國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 埃及
- 其他非洲國家
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Amcor plc
- Toray Industries, Inc.
- Oben Holding Group SA
- Taghleef Industries LLC
- Jindal Poly Films Limited
- Cosmo First Limited
- Uflex Limited
- DuPont Teijin Films Japan Ltd.
- Sealed Air Corporation
- Mondi plc
- Huhtamki Oyj
- Polifilm GmbH
- CCL Industries Inc.
- Klckner Pentaplast Group
- Innovia Films Ltd.
- Mitsui Chemicals Tohcello, Inc.
- Inteplast Group Corporation
- AR Metallizing NV
- Guangdong Decro Film New Materials Co., Ltd.
第7章 市場機會與未來展望
According to Mordor Intelligence, the plastic film market size is expected to grow from USD 70.30 billion in 2025 to USD 72.53 billion in 2026 and is forecast to reach USD 84.67 billion by 2031 at 3.18% CAGR over 2026-2031.
This report is Segmented by Resin Type (Polypropylene, Polyethylene, BOPET, Polystyrene, Bioplastics, and More), Application (Wraps and Overwraps, Bags and Linings, and More), Film Functionality (Low-Barrier Mono-Material, Medium-Barrier Metallised, and More), End-Use Industry (Food, Beverages, Healthcare and Pharmaceutical, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Plastic Film Market Trends and Insights
Consumer Shift Toward Mono-Material Recyclable Film Structures
Circular-economy policies are swiftly converting legacy multilayer formats into mono-material films that meet recyclability thresholds without sacrificing performance. European regulations mandating full recyclability by 2030 have already spurred converters such as Uzel Plastik to roll out polyethylene pet-food films that eliminate tie-layer adhesives while preserving oxygen barriers. Brand owners are rewarding early adopters with multi-year supply contracts linked to sustainability metrics, yet initial capital outlays for new extrusion and adhesive systems are trimming near-term margins. Pharmaceutical players are also transitioning; Klockner Pentaplast introduced a mono-material blister film that meets stringent medical compliance while simplifying downstream recycling. This momentum is expected to lift mono-material share from 60% in 2024 toward two-thirds of the plastic film market by 2030.
Growing Adoption of Biodegradable and Compostable Films Amid Regulations
A mosaic of state and national mandates is fueling demand for certified compostable films, particularly in food service and produce packaging. Washington State's labeling and facility-certification rules set a technical benchmark that global suppliers must now match. Minnesota's legislation requiring industrial-composting compatibility is influencing private-label specifications for supermarket chains. Suppliers with robust R&D budgets, such as DNP Group, are commercializing multilayer compostable structures capable of 90-day degradation while sustaining gas-barrier properties that protect snack foods. Lack of harmonized global standards remains a hurdle, forcing converters to produce country-specific SKUs and inflating compliance costs.
Volatility in Polyolefin and PET Feedstock Prices
Quarterly swings of 15-20% in PET and LDPE spot prices have compressed converter spreads, particularly among non-integrated players. ChemOrbis data show PET values oscillating between USD 1,200 and USD 1,450 per ton in 2024, making long-term contracts risky for suppliers dependent on spot resin. Overcapacity in Asia's BOPET segment has driven realizations to historical lows; Firsta Group recorded instances where margins dipped below INR 15/kg, triggering temporary plant shutdowns. Inventory management is further complicated by lengthy transit times, causing small converters to absorb losses during price retracements.
Other drivers and restraints analyzed in the detailed report include:
- Rising Demand for High-Barrier Films in Medical and Electronics Packaging
- Expansion of Agri-Film Usage in Vertical Farming and Greenhouse Automation
- Stringent Single-Use Plastic Bans in Emerging Economies
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Polyethylene retained 39.12% of 2025 volume, underpinned by metallocene catalyst technology that slashed film gauge by up to 20% without surrendering stiffness or clarity. This dominance supplied predictable cash flows even when oil-linked feedstock costs spiked. In contrast, bioplastics, though representing a modest baseline, are set to post a 5.87% CAGR as brand owners deploy compostable packaging pilots to meet ESG targets. Rising supply of second-generation feedstock, including sugarcane bagasse and algae oils, has clipped the cost premium to conventional resins. Still, high-barrier medical and electronics uses remain out of reach for most bioplastics due to hydrolytic-stability constraints.
Converters courting the bioplastic subsector are negotiating multi-year off-take pacts with resin start-ups to hedge price-volatility risk. Regional clustering around EU and North-American compost facilities also influences plant-location decisions. Polypropylene continues expanding within retort pouch applications, benefiting from heat-resistance and grease-barrier traits, while BOPET producers seek anti-dumping shelters in markets like the United States to escape Asian oversupply. Specialty polymers such as cyclic olefin copolymers fill niche roles in medical diagnostics, emphasizing the value of performance-led differentiation within the plastic film market.
The pouch format delivered 47.95% of 2025 sales thanks to portion-control convenience and seal-integrity that reduces food waste. Automated form-fill-seal lines, common in snack and pet-food factories, favor its geometry, while digital printing allows hyper-customized graphics for short campaigns. However, wraps and overwraps are forecast to grow at 4.56% CAGR as omnichannel grocery and meal-kit services demand puncture-resistant films compatible with high-speed bagging robots. Cold-chain compliance amplifies the need for moisture barriers that stay ductile at sub-zero temperatures, an area where BOPP-based laminates have recently gained traction.
Converters are integrating data-matrix codes into secondary wraps to track last-mile delivery conditions, creating analytics revenue streams beyond the material sale itself. Linerless label films and shrink-bundling for multipacks remain important, though growth is slower due to maturation in carbonated-drink markets. Across applications, film formats enabling resource efficiency such as perforated produce wraps that modulate respiration align with retailer sustainability pledges and thus secure shelf space despite premium pricing.
Complete Report Scope:
- By Resin Type
- Polypropylene (PP)
- Polyethylene (PE)
- Polyethylene-terephthalate (BOPET)
- Polystyrene (OPS)
- Bioplastics
- Other Material Types
- By Application
- Wraps and Overwraps
- Bags and Linings
- Pouches
- Other Applications
- By Film Functionality
- Low-Barrier Mono-material Films
- Medium-Barrier Metallised Films
- High-Barrier Multilayer Films
- Specialty Active and Antimicrobial Films
- By End-use Industry
- Food
- Candy and Confectionery
- Frozen Foods
- Fresh Produce
- Dairy Products
- Meat, Poultry and Seafood
- Pet Food
- Other Food Products
- Beverages
- Healthcare and Pharmaceutical
- Personal Care and Home Care
- Industrial Packaging
- Other End-use Industries
- Food
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Vietnam
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific secured a 37.98% share of the plastic film market in 2025 by pairing scale economies with burgeoning domestic consumption. China maintains dominance in BOPET and BOPP, though capacity additions have outstripped local demand by roughly 260,000 t a year, pressing margins and catalyzing M&A among mid-tier converters. India leverages metallocene-catalyst technology to serve upgraded pouch formats and is onboarding new BOPP lines at a brisk pace. Japan's mature yet highly technical ecosystem sustains innovation in optical and battery-separator films.
North America's demand is steadier, buoyed by on-shoring trends and sustainability mandates that push recyclable PE wraps for e-commerce. Polyplex's USD 100 million PET-film expansion in Alabama illustrates the pull of regional supply chains aligned with trade-policy certainty. Converters increasingly co-locate with logistics hubs to shrink lead times, a factor critical for meal-kit and pharmaceutical shipments.
Europe continues to act as a policy bellwether; extended-producer-responsibility (EPR) fees penalize non-recyclable formats, driving R&D dollars into mono-material upgrades. Mechanical-recycling capacity additions are ramping, and venture funds are backing chemical-recycling pilots aimed at rigid-flexible feedstock mixes.
The Middle East and Africa is poised for a 7.86% CAGR through 2031 on the back of import-substitution plans and regulatory incentives. Egypt's joint venture to build a recycled-polyester fiber line worth USD 54.8 million signals rising local appetite for circular solutions. Gulf Cooperation Council members leverage hydrocarbon integration to supply competitively priced PE, spawning downstream film clusters that aim to capture regional food-security programs. Sub-Saharan Africa's demand growth is driven by population expansion and fast-moving consumer-goods uptake, though infrastructure gaps in waste management may moderate adoption of premium sustainable films.
South America delivers mid-single-digit growth as branded food and personal-care multinationals widen rural retail penetration, creating incremental packaging needs. Currency volatility and regulatory divergence between Mercosur nations complicate capacity planning, yet rising household incomes sustain baseline consumption.
- Amcor plc
- Toray Industries, Inc.
- Oben Holding Group S.A.
- Taghleef Industries LLC
- Jindal Poly Films Limited
- Cosmo First Limited
- Uflex Limited
- DuPont Teijin Films Japan Ltd.
- Sealed Air Corporation
- Mondi plc
- Huhtamki Oyj
- Polifilm GmbH
- CCL Industries Inc.
- Klckner Pentaplast Group
- Innovia Films Ltd.
- Mitsui Chemicals Tohcello, Inc.
- Inteplast Group Corporation
- AR Metallizing N.V.
- Guangdong Decro Film New Materials Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Consumer shift toward mono-material recyclable film structures
- 4.2.2 Growing adoption of biodegradable and compostable films amid regulations
- 4.2.3 Rising demand for high-barrier films in medical and electronics packaging
- 4.2.4 Expansion of agri-film usage in vertical farming and greenhouse automation
- 4.2.5 Film downgauging enabled by advanced metallocene catalysts
- 4.2.6 Surge in regional e-commerce cold-chain requiring specialty films
- 4.3 Market Restraints
- 4.3.1 Volatility in polyolefin and PET feedstock prices
- 4.3.2 Stringent single-use plastic bans in emerging economies
- 4.3.3 Supply tightness of medical-grade PVC resin
- 4.3.4 Capital intensity of synchronous biax orientation lines
- 4.4 Industry Value Chain Analysis
- 4.5 Porters Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers/Consumers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitute Products
- 4.5.5 Intensity of Competitive Rivalry
- 4.6 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Resin Type
- 5.1.1 Polypropylene (PP)
- 5.1.2 Polyethylene (PE)
- 5.1.3 Polyethylene-terephthalate (BOPET)
- 5.1.4 Polystyrene (OPS)
- 5.1.5 Bioplastics
- 5.1.6 Other Material Types
- 5.2 By Application
- 5.2.1 Wraps and Overwraps
- 5.2.2 Bags and Linings
- 5.2.3 Pouches
- 5.2.4 Other Applications
- 5.3 By Film Functionality
- 5.3.1 Low-Barrier Mono-material Films
- 5.3.2 Medium-Barrier Metallised Films
- 5.3.3 High-Barrier Multilayer Films
- 5.3.4 Specialty Active and Antimicrobial Films
- 5.4 By End-use Industry
- 5.4.1 Food
- 5.4.1.1 Candy and Confectionery
- 5.4.1.2 Frozen Foods
- 5.4.1.3 Fresh Produce
- 5.4.1.4 Dairy Products
- 5.4.1.5 Meat, Poultry and Seafood
- 5.4.1.6 Pet Food
- 5.4.1.7 Other Food Products
- 5.4.2 Beverages
- 5.4.3 Healthcare and Pharmaceutical
- 5.4.4 Personal Care and Home Care
- 5.4.5 Industrial Packaging
- 5.4.6 Other End-use Industries
- 5.4.1 Food
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Chile
- 5.5.2.4 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Spain
- 5.5.3.5 Italy
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 Australia
- 5.5.4.5 South Korea
- 5.5.4.6 Vietnam
- 5.5.4.7 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Egypt
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Amcor plc
- 6.4.2 Toray Industries, Inc.
- 6.4.3 Oben Holding Group S.A.
- 6.4.4 Taghleef Industries LLC
- 6.4.5 Jindal Poly Films Limited
- 6.4.6 Cosmo First Limited
- 6.4.7 Uflex Limited
- 6.4.8 DuPont Teijin Films Japan Ltd.
- 6.4.9 Sealed Air Corporation
- 6.4.10 Mondi plc
- 6.4.11 Huhtamki Oyj
- 6.4.12 Polifilm GmbH
- 6.4.13 CCL Industries Inc.
- 6.4.14 Klckner Pentaplast Group
- 6.4.15 Innovia Films Ltd.
- 6.4.16 Mitsui Chemicals Tohcello, Inc.
- 6.4.17 Inteplast Group Corporation
- 6.4.18 AR Metallizing N.V.
- 6.4.19 Guangdong Decro Film New Materials Co., Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 TPE薄膜和片材市場規模、佔有率和成長分析:按材料、產品類型、應用、加工方法、最終用戶和地區分類-2026-2033年產業預測
 PET收縮膜市場-2026-2032年全球市場預測塑膠薄膜和片材市場-2026-2032年全球市場預測塑膠薄膜市場:2026-2032年全球市場預測(按材料、製造技術、產品形式、厚度、性能和最終用途產業分類)
 擠出板材市場規模、佔有率和成長分析:按材料、結構、製造流程、應用、原料、終端用戶產業和地區分類-2026-2033年產業預測
 塑膠薄膜市場:按材質、成分、分銷管道和地區分類
 塑膠薄膜和片材市場規模、佔有率和趨勢分析報告:按產品、應用、地區和細分市場預測(2026-2033 年)APET薄膜市場:2026年至2032年全球預測(依材料類型、厚度、製造流程、應用及終端用戶產業分類)非成型薄膜市場:依材料、產品、應用和厚度分類,全球預測(2026-2032)
 APET薄膜全球市場規模、佔有率、趨勢和成長分析報告(2026-2034年)