


 |
市場調查報告書
商品編碼
2123363
工業顯示器:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Industrial Display - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
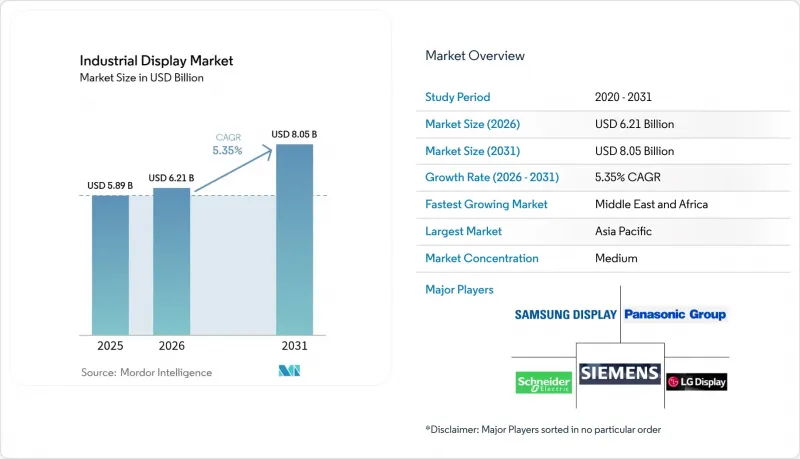
根據 Mordor Intelligence 預測,工業顯示器市場規模預計到 2026 年將達到 62.1 億美元,高於 2025 年的 58.9 億美元。
此外,預計到 2031 年市場規模將達到 80.5 億美元,並且預計從 2026 年到 2031 年將以 5.35% 的複合年成長率成長。
本報告按類型(耐環境顯示器、開放式顯示器等)、應用(人機介面、遠端資產和管道監控等)、技術(LCD、LED背光LCD等)、面板尺寸(14英寸以下、14英寸至21英寸等)、終端用戶行業(製造業、能源電力等)和地區進行細分。市場預測以美元計價。
全球工業顯示器市場趨勢與洞察
擴大工業IoT在離散製造和製程工廠的應用。
邊緣運算型人機介面 (HMI) 可實現基於以乙太網路為基礎的毫秒延遲資料處理,從而打造預測性維護儀表板,最大限度地減少意外停機時間。羅克韋爾自動化指出,控制器與視覺化終端之間更緊密的協作是邁向 2025 年的關鍵數位化路徑,並將工業物聯網 (IIoT) 架構定位為數位化的主要路線圖。 HMS Networks 也支援這一發展趨勢,指出工業乙太網將在 2024 年佔新節點安裝量的 71%,這將推動對支援 PROFINET、EtherNet/IP 和 EtherCAT 協定堆疊的顯示器的需求。
處理危險化學品的設施對多功能人機介面 (HMI) 的需求激增。
技術報告「ISA-TR101.02-2019」定義了可用性和效能基準,這些基準如今影響著所有採購要求。 VarTech Systems 等供應商提供符合 C1D1 和 C1D2 認證的面板,這些面板具有多點觸控、語音控制功能,亮度超過 1000 尼特,兼顧了安全性和功能性。這些規範有助於確保化學和製藥領域批次間的一致性,因為在這些領域,操作人員的反應速度需要達到微秒。
實施和維護高成本
防爆外殼、三防膠和專用安裝套件都會增加系統的初始投資成本。根據 Comark 公司估計,符合 IECEx 標準可能會使海上平台的設備預算翻倍,並將設計工期延長數季。
細分市場分析
到2025年,符合IP65-67標準的堅固機殼將佔據工業顯示器市場31.12%的佔有率。這反映了鑽井、採礦和軍事平台等嚴苛運作環境的需求。受石化聯合企業集中控制室投資的推動,電視牆預計將以5.66%的複合年成長率成長。高亮度開放式框架模組被整合到自助服務終端機殼中,而面板安裝單元仍然是機械級人機介面(HMI)的主流選擇。在工業顯示器市場,能夠兼顧抗衝擊性和模組化I/O的供應商備受青睞,這確保了快速更換和最大限度減少停機時間。符合MIL-STD-167抗振動標準和鹽霧試驗標準的船用級產品正在將工業顯示器市場的應用範圍擴展到海軍船艦和海上鑽井平台。條形和拉伸螢幕適用於發電廠的多參數儀表板,儘管銷量較低,但這一細分市場帶來了較高的平均售價(ASP)。
二級供應商正將堅固耐用性與窄邊框設計結合,打造出既適用於現場控制面板又適用於指揮中心的跨界產品。巴可公司與企業影院簽訂的4000塊雷射螢幕合約凸顯了其製造能力的擴充性,此後,其業務範圍已擴展至工業電視牆。混合型機殼現在整合了冗餘電源和邊緣閘道器,在滿足IEC 60079-2025安全要求的同時,也拓展了可維護工業顯示器的市場。
預計到2025年,人機介面(HMI)工作站將佔銷售額的46.05%,但隨著管道和井場遙測資料向集中管理的網路營運中心(NOC)轉移,遠端資產可視性預計將以6.12%的複合年成長率成長。隨著衛星和低功耗廣域網路(LPWAN)連接在沙漠和近海地區的普及,用於遠端監控的工業顯示器市場規模預計將穩步擴大。精益製造工廠中的安燈板和維護人員使用的互動式資訊亭增強了人性化的可視化工作流程,並縮短了故障修復週期。控制室中的電視牆定位高階,採用無邊框液晶顯示器和新興的微型LED陣列,營造出沉浸式的情境察覺環境。與人工智慧驅動的分析平台整合,使操作員能夠根據螢幕上直接顯示的指令採取行動,從而降低操作員的疲勞度和錯誤率。
OnePetro 經過現場測試的分散式太陽能顯示器即使在沒有電網覆蓋的地區也展現出實用性,從而擴大了工業顯示器市場在偏遠礦區的部署範圍。隨著網路安全日益重要,顯示器擴大整合硬體信任根模組,以保護螢幕上的資料流,這在跨境管道運作中尤其關鍵。
區域分析
預計到2025年,亞太地區將佔全球OLED銷售額的36.55%,主要得益於中國在工廠自動化方面的進步以及日本在精密零件領域的領先地位。三星顯示器和LG顯示在全球營運OLED製造工廠,鞏固了該地區在整體工業顯示器市場的供應優勢。各國政府正透過稅額扣抵支持資本投資,以加速面板工廠的擴張,從而確保即使在半導體短缺的情況下,面板供應也能保持穩定。
預計中東和非洲地區將迎來最高成長率,到2031年複合年成長率將達到6.05% 。沿岸地區高溫下也能保持高亮度的同步電視牆。
在北美,一股維修正在席捲擁有50年以上歷史的工廠,旨在提高能源效率並增強網路安全。隨著工廠採用數位性能板,工業顯示市場正在擴張,並率先用基於IP的玻璃表面取代了CRT和電阻式面板。在歐洲,透過推進工業4.0藍圖,提升操作人員的福祉,並專注於符合EN ISO 9241-210可用性指南的人體工學人機介面(HMI)佈局。在南美,採礦和水力發電產業正在進口專為高海拔和高濕度環境設計的高耐久性面板,進一步拓展了區域收入來源。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 擴大工業IoT在離散工廠和製程工廠的應用
- 處理危險化學品的設施對多功能人機介面 (HMI) 的需求激增。
- 在汽車生產線中引入精益生產數位電子看板(安燈)。
- 北美老舊廠掀起電氣化和自動化維修浪潮
- 用於油田作業的戶外微型OLED/微型LED面板,即使在陽光下也清晰可見。
- IECEx-2022:關於海上使用的本質安全型顯示硬體的規定。
- 市場限制因素
- 實施和維護成本高昂
- 由於 2023 年至 2024 年半導體短缺,LCD 控制器的前置作業時間延長了。
- 傳統PLC介面的碎片化限制了顯示器的互通性。
- 24/7 全天候控制室運作期間控制面板加速老化,導致總擁有成本上升。
- 產業生態系分析
- 監管和技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 按類型
- 耐環境影響的顯示器
- 開放式框架監視器
- 面板安裝顯示器
- 海洋和海軍展覽
- 工業電視牆
- 條形/拉伸式顯示器
- 透過使用
- 人機介面(HMI)
- 遠端資產和管道監控
- 互動式自助服務終端和操作員終端
- 工廠內的數位電子看板和安燈系統
- 控制室電視牆
- 透過技術
- LCD
- LED背光液晶顯示器
- OLED/AMOLED
- 電子紙和反射式顯示器
- Micro-LED
- 按面板尺寸
- 14吋或更小
- 14英寸至21英寸
- 21英寸至40英寸
- 40吋或更大
- 按最終用途行業分類
- 製造業
- 能源與電力
- 石油和天然氣
- 採礦和金屬
- 化學品和製藥
- 運輸/物流
- 其他(用水和污水、國防)
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 北歐的
- 其他歐洲國家
- 南美洲
- 巴西
- 其他南美國家
- 亞太地區
- 中國
- 日本
- 印度
- 東南亞
- 其他亞太國家
- 中東和非洲
- 中東
- 波灣合作理事會(GCC)成員國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 其他非洲國家
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略性舉措(併購、合資、合約)
- 市佔率分析
- 公司簡介
- Samsung Display Co., Ltd.
- LG Display Co., Ltd.
- Panasonic Holdings Corp.
- Sharp Corp.
- Emerson Electric Co.
- Schneider Electric SE
- Siemens AG
- Rockwell Automation Inc.
- NEC Display Solutions, Ltd.
- Advantech Co., Ltd.
- Barco NV
- WinMate Inc.
- Planar Systems, Inc.
- AU Optronics Corp.
- Bosch Rexroth AG
- Mitsubishi Electric Corp.
- Honeywell International Inc.
- Kontron AG
- iBASE Technology Inc.
- Beijer Electronics Group AB
- Delta Electronics, Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, industrial display market size in 2026 is estimated at USD 6.21 billion, growing from 2025 value of USD 5.89 billion with 2031 projections showing USD 8.05 billion, growing at 5.35% CAGR over 2026-2031.
This report is Segmented by Type (Rugged Displays, Open Frame Monitors, and More), Application (Human-Machine Interface, Remote Asset and Pipeline Monitoring, and More), Technology (LCD, LED Backlit LCD, and More), Panel Size (Up To 14 Inch, 14 Inch - 21 Inch, and More), End-Use Industry (Manufacturing, Energy and Power, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Industrial Display Market Trends and Insights
Increasing Adoption of Industrial IoT in Discrete and Process Plants
Edge-ready HMIs now process millisecond latency data from Ethernet-based networks, enabling predictive maintenance dashboards that minimize unplanned shutdowns. Rockwell Automation identifies IIoT architecture as the principal digitization pathway for 2025, citing tighter coupling between controllers and visualization endpoints. HMS Networks confirms momentum, noting that Industrial Ethernet supplied 71% of new node installations in 2024, catalyzing demand for displays that support PROFINET, EtherNet/IP and EtherCAT stacks.
Demand Surge for Multi-featured HMI in Hazardous Chemical Facilities
The ISA-TR101.02-2019 technical report codifies usability and performance benchmarks that now influence every procurement brief. Suppliers such as VarTech Systems deliver C1D1 and C1D2 certified panels offering multi-touch, voice control and >1,000 nit brightness, aligning safety with functionality. These specifications support batch-to-batch integrity in chemicals and pharmaceuticals where micro-seconds matter for operator intervention.
High Cost of Implementation and Maintenance
Explosion-proof enclosures, conformal coatings, and specialized mounting kits elevate upfront system outlays. Comark Corporation projects that IECEx compliance can double equipment budgets for offshore platforms while extending engineering schedules by several quarters.
Other drivers and restraints analyzed in the detailed report include:
- Lean-Manufacturing Digital Signage (Andon) Roll-outs Across Automotive Lines
- Retrofit Wave of Aging North-American Factories for Electrification and Automation
- Prolonged LCD Controller Lead-Times Amid Chip Shortage
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Rugged housings rated to IP65-67 secured a 31.12% slice of the industrial display market in 2025, reflecting critical-duty requirements in drilling, mining and military platforms. Video walls are projected to compound at 5.66% annually, fueled by centralized control-room investment across petrochemical complexes. High-brightness open-frame modules integrate into kiosk enclosures, while panel-mount units remain the workhorse for machine-level HMIs. The industrial display market repeatedly favors vendors that combine shock resistance with modular I/O, ensuring rapid swap-out and minimal downtime. Marine-grade variants meet MIL-STD-167 vibration thresholds and salt-spray protocols, extending the industrial display market footprint to naval vessels and offshore rigs. Bar-type and stretch screens address multi-parameter dashboards in power plants, a niche translating to higher ASPs despite lower volumes.
Second-tier suppliers are blending ruggedization with narrow-bezel architectures, creating cross-over products that serve both field panels and command centers. Barco's enterprise cinema contract for 4,000 laser screens underscores manufacturing scalability that later translates into industrial video walls. Hybrid enclosures now embed redundant power supplies and edge gateways, aligning with IEC 60079-2025 safety clauses while enlarging the serviceable industrial display market.
HMI stations delivered 46.05% of 2025 revenue, but remote asset visualization will outpace at a 6.12% CAGR as pipeline and well-pad telemetry shifts to centralized NOCs. The industrial display market size for remote monitoring is forecast to expand steadily as satellite and LPWAN connectivity proliferate in deserts and offshore locations. Andon boards in lean plants and interactive kiosks for maintenance crews reinforce human-centric visual workflows that shorten fault-to-fix cycles. Control-room video walls constitute the premium class where bezel-less LCD or emerging Micro-LED arrays craft immersive situational awareness environments. Integration with AI-driven analytics platforms means operators now act on prescriptive prompts rendered directly on the screen, reducing operator fatigue and error incidence.
Distributed solar-powered screens demonstrated by OnePetro field trials prove viability in regions lacking grid access, widening the install base of the industrial display market in remote extraction zones. As cybersecurity rises in priority, displays are increasingly paired with hardware-root-of-trust modules to secure on-screen data flows, a requirement accentuated in cross-border pipeline operations.
Complete Report Scope:
- By Type
- Rugged Displays
- Open Frame Monitors
- Panel-Mount Monitors
- Marine and Naval-Grade Displays
- Industrial Video Walls
- Bar-Type/Stretch Displays
- By Application
- Human-Machine Interface (HMI)
- Remote Asset and Pipeline Monitoring
- Interactive Kiosks and Operator Terminals
- In-plant Digital Signage and Andon Boards
- Control-Room Video Walls
- By Technology
- LCD
- LED Backlit LCD
- OLED/AMOLED
- E-Paper and Reflective Displays
- Micro-LED
- By Panel Size
- Up to 14 inch
- 14 inch - 21 inch
- 21 inch - 40 inch
- 40 inch and Above
- By End-Use Industry
- Manufacturing
- Energy and Power
- Oil and Gas
- Mining and Metals
- Chemical and Pharmaceutical
- Transportation and Logistics
- Others (Water and Wastewater, Defense)
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Nordics
- Rest of Europe
- South America
- Brazil
- Rest of South America
- Asia-Pacific
- China
- Japan
- India
- South-East Asia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Gulf Cooperation Council Countries
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific commanded 36.55% revenue in 2025, underpinned by China's factory automation drive and Japan's leadership in precision components. Samsung Display and LG Display operate global-scale OLED fabs, cementing the region's supply advantage across the industrial display market. Component governments back capex tax credits that accelerate panel plant expansions, ensuring steady panel availability even during semiconductor shortages.
The Middle East and Africa is poised for the fastest 6.05% CAGR to 2031. Multi-billion-dollar hydrocarbon projects across the Gulf rely on intrinsically safe screens certified under IEC 60079-2025, enlarging the industrial display market size for explosion-proof hardware. National oil companies pair centralized NOCs with regional micro-control rooms, demanding synchronized video walls that sustain high brightness amid desert temperatures.
North America witnesses a retrofit wave across mid-century factories seeking energy efficiencies and cybersecurity hardening. Proactive replacement of CRTs and resistive-touch panels with IP-based glass surfaces boosts the industrial display market as factories embrace digital performance boards. Europe advances Industry 4.0 blueprints with a focus on ergonomic HMI layouts compliant with EN ISO 9241-210 usability guidance, promoting operator well-being. South America's mining and hydroelectric sectors import hardy panels rated for high altitude and humidity, further diversifying geographic revenue.
- Samsung Display Co., Ltd.
- LG Display Co., Ltd.
- Panasonic Holdings Corp.
- Sharp Corp.
- Emerson Electric Co.
- Schneider Electric SE
- Siemens AG
- Rockwell Automation Inc.
- NEC Display Solutions, Ltd.
- Advantech Co., Ltd.
- Barco NV
- WinMate Inc.
- Planar Systems, Inc.
- AU Optronics Corp.
- Bosch Rexroth AG
- Mitsubishi Electric Corp.
- Honeywell International Inc.
- Kontron AG
- iBASE Technology Inc.
- Beijer Electronics Group AB
- Delta Electronics, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Adoption of Industrial IoT in Discrete and Process Plants
- 4.2.2 Demand Surge for Multi-featured HMI in Hazardous Chemical Facilities
- 4.2.3 Lean-Manufacturing Digital Signage (Andon) Roll-outs Across Automotive Lines
- 4.2.4 Retrofit Wave of Aging North-American Factories for Electrification and Automation
- 4.2.5 Outdoor-Grade Sunlight-Readable Micro-OLED/Micro-LED Panels for Oilfield Operations
- 4.2.6 IECEx-2022 Mandate for Intrinsically Safe Offshore Display Hardware
- 4.3 Market Restraints
- 4.3.1 High Cost of Implementation and Maintenance
- 4.3.2 Prolonged LCD Controller Lead-Times Amid 2023-24 Chip Shortage
- 4.3.3 Legacy PLC Interface Fragmentation Limiting Display Interoperability
- 4.3.4 Accelerated Panel Burn-in in 24/7 Control-Room Duty Raising TCO
- 4.4 Indusrty Ecosystem Analysis
- 4.5 Regulatory and Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Type
- 5.1.1 Rugged Displays
- 5.1.2 Open Frame Monitors
- 5.1.3 Panel-Mount Monitors
- 5.1.4 Marine and Naval-Grade Displays
- 5.1.5 Industrial Video Walls
- 5.1.6 Bar-Type/Stretch Displays
- 5.2 By Application
- 5.2.1 Human-Machine Interface (HMI)
- 5.2.2 Remote Asset and Pipeline Monitoring
- 5.2.3 Interactive Kiosks and Operator Terminals
- 5.2.4 In-plant Digital Signage and Andon Boards
- 5.2.5 Control-Room Video Walls
- 5.3 By Technology
- 5.3.1 LCD
- 5.3.2 LED Backlit LCD
- 5.3.3 OLED/AMOLED
- 5.3.4 E-Paper and Reflective Displays
- 5.3.5 Micro-LED
- 5.4 By Panel Size
- 5.4.1 Up to 14 inch
- 5.4.2 14 inch - 21 inch
- 5.4.3 21 inch - 40 inch
- 5.4.4 40 inch and Above
- 5.5 By End-Use Industry
- 5.5.1 Manufacturing
- 5.5.2 Energy and Power
- 5.5.3 Oil and Gas
- 5.5.4 Mining and Metals
- 5.5.5 Chemical and Pharmaceutical
- 5.5.6 Transportation and Logistics
- 5.5.7 Others (Water and Wastewater, Defense)
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Nordics
- 5.6.2.5 Rest of Europe
- 5.6.3 South America
- 5.6.3.1 Brazil
- 5.6.3.2 Rest of South America
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South-East Asia
- 5.6.4.5 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Gulf Cooperation Council Countries
- 5.6.5.1.2 Turkey
- 5.6.5.1.3 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, JV, Agreements)
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Samsung Display Co., Ltd.
- 6.4.2 LG Display Co., Ltd.
- 6.4.3 Panasonic Holdings Corp.
- 6.4.4 Sharp Corp.
- 6.4.5 Emerson Electric Co.
- 6.4.6 Schneider Electric SE
- 6.4.7 Siemens AG
- 6.4.8 Rockwell Automation Inc.
- 6.4.9 NEC Display Solutions, Ltd.
- 6.4.10 Advantech Co., Ltd.
- 6.4.11 Barco NV
- 6.4.12 WinMate Inc.
- 6.4.13 Planar Systems, Inc.
- 6.4.14 AU Optronics Corp.
- 6.4.15 Bosch Rexroth AG
- 6.4.16 Mitsubishi Electric Corp.
- 6.4.17 Honeywell International Inc.
- 6.4.18 Kontron AG
- 6.4.19 iBASE Technology Inc.
- 6.4.20 Beijer Electronics Group AB
- 6.4.21 Delta Electronics, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 橡膠邊框顯示器市場規模、佔有率和成長分析:按顯示器類型、螢幕尺寸、安裝方式、應用、最終用戶和地區分類 - 2026-2033 年行業預測
 工業顯示器市場-2026-2032年全球市場預測商用顯示器市場:2026-2032年全球市場預測(依顯示技術、面板尺寸、產品類型、解析度、安裝方式及最終用戶分類)
 工業顯示器市場:按技術、類型、面板尺寸、應用、產業和地區分類商用顯示器市場:按技術、組件、顯示器類型、顯示器尺寸、應用和地區分類商業顯示器市場:2026-2032年全球市場預測,依產品、技術、類型、顯示器尺寸、安裝方式、應用、最終用戶及通路分類
 工業IoT顯示器市場規模、佔有率和成長分析:按應用、連接方式、顯示器類型、面板尺寸和地區分類-2026-2033年產業預測
 工業IoT顯示器市場分析及預測(至2035年):依類型、產品類型、服務、技術、組件、應用、形狀、材質、設備及部署方式分類
 商業顯示器市場規模、佔有率、成長及全球產業分析:按類型、應用和地區分類-2026-2034 年洞察與預測
 2026年全球商用顯示器市場報告