


 |
市場調查報告書
商品編碼
2123293
互聯物流:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Connected Logistics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
2025年互聯物流市場價值為339.4億美元,預計到2031年將達到701.6億美元,而2026年為383.1億美元,預測期(2026-2031年)複合年成長率為12.86%。
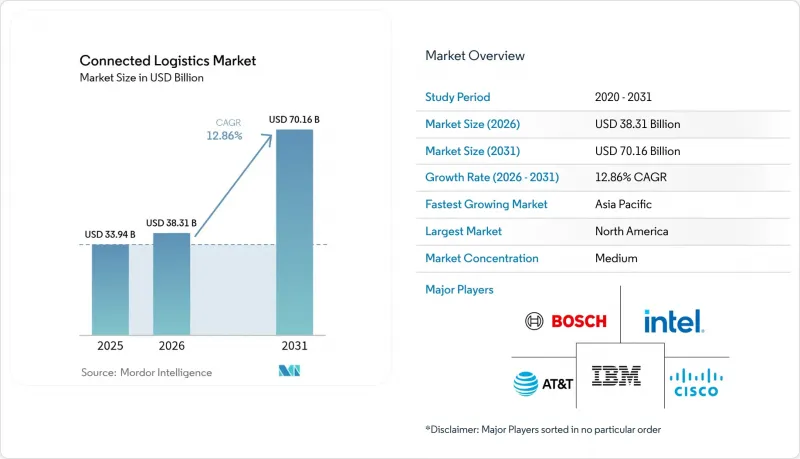
本報告按軟體解決方案(資產管理、安全等)、產品類型(設備管理、應用程式管理等)、運輸方式(公路、鐵路等)、最終用戶行業(汽車、製造業等)、服務類型(託管服務等)、部署模式(雲端、混合等)、組織規模(大型企業等)和地區進行分類。
全球互聯物流市場趨勢與洞察
物聯網在資產追蹤領域的應用激增
低功耗感測器和全球低功耗廣域網路 (LPWAN) 覆蓋範圍使企業能夠即時監控位置、溫度和影響,在某些 LoRaWAN 部署中,電池壽命可延長至 10 年。 BMW利用藍牙信標追蹤倉庫中的車輛,顯著縮短了搜尋時間。康德樂 (Cardinal Health) 的智慧感測器先導計畫正在改善醫院設備室的有效期管理。人工智慧分析的整合將歷史數據轉化為預測性維護警報,使車輛管理從被動響應轉變為主動預防。
托運人要求即時查看貨物資訊。
FourKites收購TrackX Yard Solutions後,整合了堆場管理資料和長途運輸視覺性,使托運人能夠每小時收到一次拖車位置更新。汽車精加工中心的RFID應用可將即時狀態傳送至OEM的ERP系統,滿足嚴格的準時制指標。生命科學領域的托運人正在部署多感測器標籤,以滿足良好分銷規範(GDP)中關於持續溫度記錄的要求。視覺化數據正用於一個由生成式人工智慧驅動的路線最佳化入口網站,預計到2028年,該網站將處理四分之一的物流KPI報告。
多租戶車隊的網路安全風險
2024年,交通運輸業的安全漏洞報告數量增加了181%,其中勒索軟體攻擊主要針對車輛遠端資訊處理系統和電子記錄設備。貨物竊盜損失高達4.55億美元,許多案件涉及詐騙,犯罪者冒充仲介,企圖轉移整車貨物。物流業的首席資訊安全安全長(CISO)預計安全支出將實現兩位數成長,這與馬士基預測的到2037年達到366億美元的支出目標相符。多租戶SaaS平台使租戶隔離變得更加複雜,增加了橫向機芯的風險。
細分市場分析
預計到2025年,資產管理將佔互聯物流市場規模的40.40%,因為企業可以透過減少閒置時間和提高貨櫃周轉率立即獲得投資回報。企業正在將RFID、GNSS和環境感測器整合到統一的儀錶板中,以即時檢測未充分利用的拖車和溫度偏差。隨著企業需要亞秒級的卡車預計到達時間波動和停留時間熱點信息,流式分析正以16.07%的複合年成長率快速發展,從而推動預測性路線重排引擎的運行。不斷發展的倉庫物聯網疊加技術正在擴展其應用場景,從引導揀貨員到最佳化環境控制和降低冷鏈SKU的劣化率。安全分析套件分析異常資料封包的流動,以偵測設備被入侵的早期徵兆。隨著微軟將其邊緣AI工具包擴展到物流閘道器,供應商正在將資產狀態和交通預測整合到單一的建議引擎中。
到2025年,設備管理將佔據43.30%的市場。這反映了韌體補丁的複雜性以及對成千上萬輛韌體、托盤和場地感測器進行身份驗證的困難。零接觸式入駐工具正在縮短卡車和碼頭的啟動時間,從而支援大規模更新周期。隨著專用5G和衛星鏈路的日益普及,連接管理正以15.25%的複合年成長率快速成長,導致需要逐個資產進行調整的合約類型不斷增加。應用程式管理平台在雲端區域和邊緣閘道器之間遷移工作負載,以滿足延遲容忍度和資料駐留要求。騰訊和三星的專利申請展示了新的流量優先演算法,該演算法可根據車速調整無線電參數。支援區塊鏈的設備現在整合了加密模組,提高了設備生命週期管理的標準。
到2025年,道路運輸將佔互聯物流市場佔有率的38.10%,這主要得益於高密度「最後一公里」網路和成熟的遠端資訊處理技術改造。強制性的基於攝影機的ADAS(高級駕駛輔助系統)和ELD(電子駕駛記錄器)正在加速資料流,有助於提高駕駛員安全性和合規性。海運預計將以14.72%的複合年成長率成長,這主要得益於智慧貨櫃遙測技術和自動化碼頭營運。鐵路行業正在透過引入軌道旁感測器陣列進行現代化改造,這些陣列可以預測車輪扁平缺陷,從而減少幹線中斷。在航空業,ULD追蹤器和人工智慧驅動的艙位管理工具正在貨運樞紐進行整合。 Eurotainer的槽式貨櫃遙測技術透過縮短加熱週期,將供應鏈成本降低了40%。 Aurora Innovation公司在達拉斯和休士頓之間建立的無人貨運走廊已在無人操作的情況下行駛了1200英里。
區域分析
北美地區預計到2025年將保持34.90%的市場佔有率,這得益於其強大的高速公路網路和用於輔助自動創業投資資金和公私合營試驗平台正在加速技術的應用。預計到2031年,亞太地區的複合年成長率將達到13.12%。日本國土交通省正在評估連接東京和大阪的500公里自動化貨運路線的可行性。澳洲在物流自動化領域的投資已超過40億美元,涵蓋倉庫機器人和堆場自動化。 GEODIS正在擴展從新加坡到中國的GPS可追蹤陸路運輸路線,著眼於預計將成長至4.5兆美元的區域物流產業。作為2025年國際貨運代理聯合會(FIATA)世界錦標賽的東道國,越南正致力於將自身打造成為東協的物流樞紐。在歐洲,嚴格的資料保護條例與鼓勵車輛電氣化和向永續航空燃料轉型的脫碳義務之間需要取得平衡。 CEVA新增了23輛電動卡車,使其低碳車隊規模超過1,100輛(cevalogistics.com)。 DHL與Neste合作,採用永續航空燃料(SAF)供應模式,以支持歐盟實現交通運輸部門淨零排放的目標。歐盟委員會估計,該地區的物流經濟規模達8,780億歐元,並正致力於協調相關法規,以減少跨境行政程序。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 物聯網在資產追蹤領域的應用激增
- 托運人必須提供即時貨物追蹤資訊。
- 透過併購實現平台整合
- 碼頭和港口的5G專用網路
- 利用數位孿生降低供應鏈風險
- 市場限制因素
- 多租戶機隊的網路安全責任
- 世界各地數據主權法律的差異
- 現有資產缺乏可互通的API
- 「免運費」電商模式對利潤率帶來壓力
- 價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 透過軟體解決方案
- 資產管理
- 倉庫物聯網
- 安全
- 資料管理
- 網管
- 流分析
- 依產品類型
- 設備管理
- 應用程式管理
- 連線管理
- 透過運輸方式
- 路
- 鐵路
- 航空
- 海上運輸
- 按最終用戶行業分類
- 車
- 製造業
- 石油和天然氣
- 資訊科技/通訊
- 衛生保健
- 零售與電子商務
- 食品/飲料
- 其他行業
- 按服務類型
- 諮詢與整合
- 託管服務
- 支援與維護
- 部署模式
- 雲
- 現場
- 混合
- 按組織規模
- 大公司
- 中小企業
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 智利
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 荷蘭
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- ASEAN
- 其他亞太國家
- 中東和非洲
- 中東
- 海灣合作理事會(沙烏地阿拉伯、阿拉伯聯合大公國、卡達等)
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 其他非洲國家
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Bosch Service Solutions GmbH
- Cisco Systems Inc.
- AT&T Inc.
- IBM Corporation
- Intel Corporation
- SAP SE
- Oracle Corporation
- Freightgate Inc.
- ORBCOMM Inc.
- HCL Technologies Ltd.
- Honeywell International Inc.
- Microsoft Corporation
- Siemens AG
- Zebra Technologies Corp.
- Trimble Inc.
- Descartes Systems Group
- Sensitech Inc.
- Project44 Inc.
- FourKites Inc.
- Huawei Technologies Co. Ltd.
- JD Logistics
- DHL Supply Chain
- FedEx Corp.
- UPS Inc.
According to Mordor Intelligence, the connected logistics market size was valued at USD 33.94 billion in 2025 and estimated to grow from USD 38.31 billion in 2026 to reach USD 70.16 billion by 2031, at a CAGR of 12.86% during the forecast period (2026-2031).
This report is Segmented by Software Solution (Asset Management, Security, and More), Product Type (Device Management, Application Management, and More), Transportation Mode (Roadways, Railways, and More), End-User Industry (Automotive, Manufacturing and More), Service Type (Managed Services and More), Deployment Mode (Cloud, Hybrid, and More), Organization Size (Large Enterprises and More), and Geography.
Global Connected Logistics Market Trends and Insights
Surge in IoT-enabled asset tracking
Low-power sensors and global LPWAN coverage let companies monitor location, temperature, and shock in real time, extending battery life to a decade in some LoRaWAN deployments. BMW's use of Bluetooth beacons to trace vehicles across warehouses cut search times dramatically. Cardinal Health's smart-sensor pilots improve expiry management in hospital supply rooms. Converging AI analytics transform historical data into predictive maintenance alerts, shifting fleets from reactive to proactive coordination.
Real-time freight visibility mandates from shippers
FourKites' purchase of TrackX Yard Solutions pairs yard-management data with over-the-road visibility, giving shippers sub-hourly updates on trailer locations. RFID deployments in automotive finishing centers stream live status to OEM ERP systems, satisfying strict just-in-time metrics. Life-science consignors deploy multi-sensor tags to meet continuous-temperature logging rules under Good Distribution Practice. Visibility feeds generative-AI route optimization portals expected to handle one-quarter of logistics KPI reporting by 2028.
Cyber-security liabilities across multi-tenant fleets
Reported breaches in transport rose 181% in 2024, with ransomware targeting fleet telematics and electronic logging devices. Cargo theft hit USD 455 million, often via broker impersonation that reroutes entire truckloads. Logistics CISOs now budget double-digit growth in security spend, mirroring Maersk's forecast of USD 36.6 billion by 2037. Multi-tenant SaaS platforms complicate isolation-of-tenants, elevating lateral-movement risks
Other drivers and restraints analyzed in the detailed report include:
- M&A-driven platform consolidation
- 5G private networks in yards and ports
- Fragmented global data-sovereignty laws
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Asset Management represented 40.40% of the connected logistics market size in 2025 thanks to the immediate ROI firms gain by trimming idle time and improving container turns. Enterprises mesh RFID, GNSS, and environmental sensors into unified dashboards that flag under-utilized trailers and temperature excursions in real time. Streaming Analytics is advancing at 16.07% CAGR as organizations demand sub-second insight into truck ETA variance and dwell-time hot spots, fueling predictive rerouting engines.Evolving warehouse IoT overlays expand use cases from picker guidance to climate optimization, cutting spoilage rates for cold-chain SKUs. Security analytics suites analyze atypical data-packet flows to detect early indicators of device compromise. As Microsoft extends edge AI toolkits into logistics gateways, providers stitch asset health and traffic forecasts into single recommendation engines.
Device Management captured 43.30% share in 2025, reflecting the complexity of patching firmware and certifying thousands of truck, pallet, and yard sensors. Zero-touch onboarding tools reduce truck-dock activation times, supporting large-scale refresh cycles. Connectivity Management is rising at a 15.25% CAGR as private 5G and satellite links multiply subscription profiles that must be orchestrated per asset.Application Management platforms move workloads between cloud regions and edge gateways to honor latency budgets and data-residency constraints. Patent filings by Tencent and Samsung illustrate new traffic-prioritization algorithms that adapt radio parameters by vehicle speed. Blockchain-enabled devices now embed cryptographic modules, raising the bar for device-lifecycle orchestration
Roadways held 38.10% of the connected logistics market share in 2025 due to dense last-mile networks and mature telematics retrofits. Camera-based ADAS and ELD mandates fuel data flows that improve driver safety and regulatory compliance. Seaways is expected to post a 14.72% CAGR, propelled by smart-container telemetry and automated terminal operations.Railways modernize with wayside-sensor arrays that predict wheel-flat defects, reducing line-haul interruptions. Airways integrate ULD trackers and AI-driven slot-management tools at cargo hubs. Eurotainer's tank-container telemetry cut supply-chain costs 40% by shrinking heating cycles. Aurora Innovation's driverless freight corridor between Dallas and Houston logged 1,200 miles without a human operator
Complete Report Scope:
- By Software Solution
- Asset Management
- Warehouse IoT
- Security
- Data Management
- Network Management
- Streaming Analytics
- By Product Type
- Device Management
- Application Management
- Connectivity Management
- By Transportation Mode
- Roadways
- Railways
- Airways
- Seaways
- By End-user Industry
- Automotive
- Manufacturing
- Oil and Gas
- IT and Telecom
- Healthcare
- Retail and E-commerce
- Food and Beverage
- Other Industries
- By Service Type
- Consulting and Integration
- Managed Services
- Support and Maintenance
- By Deployment Mode
- Cloud
- On-Premise
- Hybrid
- By Organisation Size
- Large Enterprises
- Small and Medium Enterprises (SMEs)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East and Africa
- Middle East
- GCC (Saudi Arabia, UAE, Qatar, etc.)
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America retained 34.90% share in 2025, buoyed by robust highway networks and supportive innovation sandboxes for autonomous vehicle pilots. Amazon is investing USD 4 billion to extend next-day coverage to 4,000 rural communities, underscoring the scale of infrastructure spend. UPS's purchase of Andlauer Healthcare Group deepens cold-chain specialization in the region. Cyber-risk remains acute, yet venture funding and public-private testbeds accelerate technology diffusion. Asia Pacific is projected to lead growth at a 13.12% CAGR through 2031. Japan's transport ministry is evaluating a 500-kilometer automated freight link between Tokyo and Osaka. Australia's logistics-automation outlays exceed USD 4 billion, spanning warehouse robotics and yard automation. GEODIS is extending GPS-tracked road corridors from Singapore to China in anticipation of a USD 4.5 trillion regional logistics sector. Vietnam positions itself as an ASEAN logistics pivot by hosting the 2025 FIATA World Congress. Europe balances stringent data-protection rules with decarbonization mandates that push fleets toward EVs and sustainable aviation fuels. CEVA added 23 electric trucks, raising its low-carbon fleet beyond 1,100 vehicles cevalogistics.com. DHL collaborates with Neste on SAF supply models, supporting the EU's net-zero transport goal. The European Commission estimates the regional logistics economy at EUR 878 billion and continues harmonizing rules to cut cross-border paperwork
- Bosch Service Solutions GmbH
- Cisco Systems Inc.
- AT&T Inc.
- IBM Corporation
- Intel Corporation
- SAP SE
- Oracle Corporation
- Freightgate Inc.
- ORBCOMM Inc.
- HCL Technologies Ltd.
- Honeywell International Inc.
- Microsoft Corporation
- Siemens AG
- Zebra Technologies Corp.
- Trimble Inc.
- Descartes Systems Group
- Sensitech Inc.
- Project44 Inc.
- FourKites Inc.
- Huawei Technologies Co. Ltd.
- JD Logistics
- DHL Supply Chain
- FedEx Corp.
- UPS Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in IoT-enabled asset tracking
- 4.2.2 Real-time freight visibility mandates from shippers
- 4.2.3 MandA-driven platform consolidation
- 4.2.4 5G private networks in yards and ports
- 4.2.5 De-risking supply chains via digital twins
- 4.3 Market Restraints
- 4.3.1 Cyber-security liabilities across multi-tenant fleets
- 4.3.2 Fragmented global data-sovereignty laws
- 4.3.3 Scarcity of interoperable APIs for brown-field assets
- 4.3.4 Margin pressure from "ship-for-free" e-commerce models
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Software Solution
- 5.1.1 Asset Management
- 5.1.2 Warehouse IoT
- 5.1.3 Security
- 5.1.4 Data Management
- 5.1.5 Network Management
- 5.1.6 Streaming Analytics
- 5.2 By Product Type
- 5.2.1 Device Management
- 5.2.2 Application Management
- 5.2.3 Connectivity Management
- 5.3 By Transportation Mode
- 5.3.1 Roadways
- 5.3.2 Railways
- 5.3.3 Airways
- 5.3.4 Seaways
- 5.4 By End-user Industry
- 5.4.1 Automotive
- 5.4.2 Manufacturing
- 5.4.3 Oil and Gas
- 5.4.4 IT and Telecom
- 5.4.5 Healthcare
- 5.4.6 Retail and E-commerce
- 5.4.7 Food and Beverage
- 5.4.8 Other Industries
- 5.5 By Service Type
- 5.5.1 Consulting and Integration
- 5.5.2 Managed Services
- 5.5.3 Support and Maintenance
- 5.6 By Deployment Mode
- 5.6.1 Cloud
- 5.6.2 On-Premise
- 5.6.3 Hybrid
- 5.7 By Organisation Size
- 5.7.1 Large Enterprises
- 5.7.2 Small and Medium Enterprises (SMEs)
- 5.8 By Geography
- 5.8.1 North America
- 5.8.1.1 United States
- 5.8.1.2 Canada
- 5.8.1.3 Mexico
- 5.8.2 South America
- 5.8.2.1 Brazil
- 5.8.2.2 Argentina
- 5.8.2.3 Chile
- 5.8.2.4 Rest of South America
- 5.8.3 Europe
- 5.8.3.1 Germany
- 5.8.3.2 United Kingdom
- 5.8.3.3 France
- 5.8.3.4 Italy
- 5.8.3.5 Spain
- 5.8.3.6 Netherlands
- 5.8.3.7 Russia
- 5.8.3.8 Rest of Europe
- 5.8.4 Asia Pacific
- 5.8.4.1 China
- 5.8.4.2 India
- 5.8.4.3 Japan
- 5.8.4.4 South Korea
- 5.8.4.5 ASEAN
- 5.8.4.6 Rest of Asia Pacific
- 5.8.5 Middle East and Africa
- 5.8.5.1 Middle East
- 5.8.5.1.1 GCC (Saudi Arabia, UAE, Qatar, etc.)
- 5.8.5.1.2 Turkey
- 5.8.5.1.3 Rest of Middle East
- 5.8.5.2 Africa
- 5.8.5.2.1 South Africa
- 5.8.5.2.2 Rest of Africa
- 5.8.5.1 Middle East
- 5.8.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 Bosch Service Solutions GmbH
- 6.4.2 Cisco Systems Inc.
- 6.4.3 AT&T Inc.
- 6.4.4 IBM Corporation
- 6.4.5 Intel Corporation
- 6.4.6 SAP SE
- 6.4.7 Oracle Corporation
- 6.4.8 Freightgate Inc.
- 6.4.9 ORBCOMM Inc.
- 6.4.10 HCL Technologies Ltd.
- 6.4.11 Honeywell International Inc.
- 6.4.12 Microsoft Corporation
- 6.4.13 Siemens AG
- 6.4.14 Zebra Technologies Corp.
- 6.4.15 Trimble Inc.
- 6.4.16 Descartes Systems Group
- 6.4.17 Sensitech Inc.
- 6.4.18 Project44 Inc.
- 6.4.19 FourKites Inc.
- 6.4.20 Huawei Technologies Co. Ltd.
- 6.4.21 JD Logistics
- 6.4.22 DHL Supply Chain
- 6.4.23 FedEx Corp.
- 6.4.24 UPS Inc.

 物流平台市場預測至2034年-按平台功能、資料整合、連接模式、營運模式、最終用戶和區域分類的全球分析城市物流自動化市場預測至2034年-按解決方案類型、技術、應用、最終用戶和地區分類的全球分析
 物聯網物流市場:按組件、組織規模、技術、部署模式和應用分類-2026-2032年全球市場預測非正規交通運輸數位化市場預測至2034年-按運輸方式、數位化解決方案、所有權/營運結構、最終用戶和區域分類的全球分析
 2026年全球互聯物流市場報告互聯物流市場:依物流類型、運輸方式、服務類型及最終用途分類-2026-2032年全球預測
 互聯物流市場分析及預測(至2035年):依類型、產品、服務、技術、組件、應用、設備、流程、部署類型及最終用戶分類
 全球互聯物流市場規模、佔有率、趨勢和成長分析報告(2026-2034)全球物聯網 (IoT) 市場規模、佔有率、趨勢和成長分析報告(2026-2034 年物流領域)
 互聯物流市場規模、佔有率、趨勢和預測(按組件、軟體、技術、設備、運輸方式、最終用戶行業和地區分類),2026-2034年