


 |
市場調查報告書
商品編碼
2123134
電氣和電子測試設備:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031)Electrical And Electronic Test Equipment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
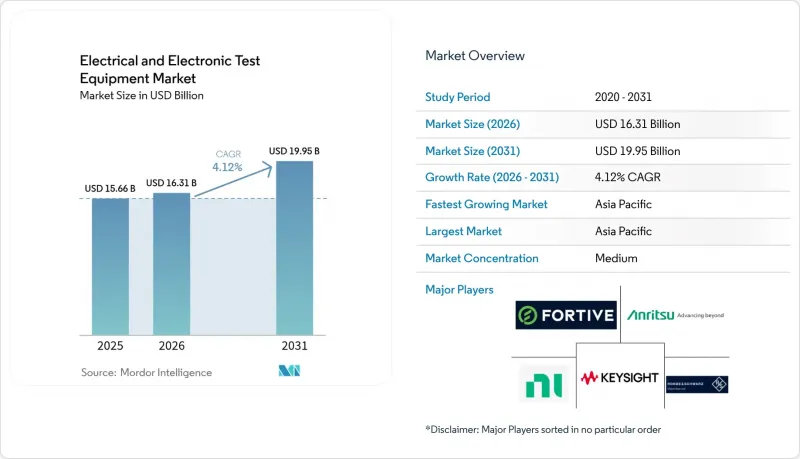
根據 Mordor Intelligence 預測,電氣和電子測試設備的市場規模預計將從 2025 年的 156.6 億美元成長到 2026 年的 163.1 億美元,然後從 2026 年到 2031 年以 4.12% 的複合年成長,到 2031 億美元達到 19.5 億美元。
本報告按產品類型(示波器、頻譜分析儀、訊號產生器等)、外形尺寸(桌上型、可攜式、模組化)、應用階段(研發、製造、安裝、合規性)、終端用戶產業(電信、半導體、汽車、航太、家用電子電器等)和地區進行細分。報告還提供市場預測(價值,美元)。
全球電氣和電子測試設備市場趨勢與洞察
5G和先進無線技術部署浪潮
全球5G基礎設施的擴張,對支援毫米波和6GHz以下頻段的分析儀、訊號產生器和無線傳輸測試實驗室的需求空前高漲。電信業者需要在日益擁擠的頻寬中檢驗波束成形、載波聚合和衛星回程傳輸的性能。如今,測量設備需要模擬多普勒效應、GNSS授時和非地面電波網路延遲,而傳統的地面電波射頻測量設備無法應對這些挑戰。供應商正在推出緊湊型CATR(載波干擾測試室)系列產品,這些產品在保持「靜默區」精度的同時,還能縮小所需面積,這對於消費性電子產品製造商而言至關重要。製造工廠和物流中心專用網路的部署也催生了新的需求。在這些環境中,頻譜共存和極高的可靠性至關重要,這給測試實驗室帶來了新的檢驗負擔。隨著無線標準演進至5G-Advanced和早期6G研究階段,這些因素共同推動了電氣和電子測試設備市場的發展動能。
先進節點半導體的日益複雜化
隨著晶片製造商在3奈米及更精細製程節點的製造過程中採用多晶片封裝和晶片組架構,測試向量的數量將大幅增加。產業協會SEMI預測,半導體測試設備銷售額將在2024年達到67億美元,預計在2025年成長30.3%,這主要得益於裝置複雜性的持續提高。泰瑞達及其合作夥伴目前能夠一次測試矽光電晶圓的正反兩面,從而顯著縮短共封裝光元件的測試週期。高頻寬記憶體堆疊、人工智慧加速器和封裝內收發器需要嚴格的熱控制和多Gigabit介面支持,這給傳統自動測試設備(ATE)帶來了挑戰。探針卡供應商FormFactor和Technoprobe已獲得Advantest的策略投資,以確保下一代接觸器的供應。資本投入的增加正在透過擴大目標工作負載來支持電氣和電子測試設備市場的長期成長。
高昂的資本投資成本和向租賃模式的轉變
核心5G和半導體ATE平台單價可能超過100萬美元,對資本支出預算造成巨大壓力。客戶擴大選擇租賃和訂閱模式。 Electro Rent公司擁有價值12億美元的庫存,以滿足這些需求。設備租賃與金融協會(ELFA)預測,到2024年,54%的設備購買將透過融資完成,並預測設備即服務(EaaS)到2030年將以50%的複合年成長率成長。雖然持續的收入對供應商而言是長期的利好,但短期硬體銷售已趨於平穩,減緩了電氣和電子測試設備市場的整體擴張。
細分市場分析
在電氣和電子測試設備市場中,示波器市場預計到2025年將達到46.1億美元,佔總營收的29.45%,佔據主導地位。示波器在研發、檢驗和故障排除方面仍然至關重要,但隨著設計頻率超過70 GHz,頻寬限制和協定解碼深度正成為區分不同產品的關鍵因素。受5G非地面電波網路、衛星物聯網和汽車雷達等應用需求的推動,射頻和微波儀器的複合年成長率(CAGR)為4.63%。具備即時觸發功能和支援2 GHz調頻寬的訊號產生器的頻譜分析儀正從實驗室走向現場應用。像支援40 GHz頻段的USB供電可攜式向量網路分析儀VNA400這樣的產品表明,小型化不再以犧牲性能為代價。
半導體ATE市場受晶圓廠擴張帶來的週期性需求驅動,但晶片組架構的出現也為其帶來了益處,該架構增加了引腳數量,並有助於多站點測試。環境壓力測試儀和電氣安全測試儀的需求因IEC和UL標準的日益嚴格而得到提升,尤其是在電池供電的消費性電子設備領域。光電技術的融合催生了混合測試儀的出現,這些測試儀能夠在單一工作流程中測量插入損耗、眼圖和射頻損傷,從而滿足資料中心對共封裝光學元件的需求。總體而言,儘管存在一些波動,但產品多元化支撐了電氣和電子測試設備市場的穩定收入。
桌上型平台憑藉其基準級的精確度、直覺的前面板和強大的輸入保護功能,預計將在2025年佔據47.12%的銷售額。這些平台在早期設計階段和大學實驗室中佔據主導地位,在這些應用中,柔軟性比機架密度更為重要。同時,模組化PXI系統正以5.02%的複合年成長率快速成長,因為使用者更傾向於使用同步的、軟體定義的通道進行平行測試。隨著工廠品質檢測站的數位化程度不斷提高,換線週期不斷縮短,預計到2031年,由PXI配置驅動的電氣和電子測試設備市場規模將超過51.8億美元。
NI 提供超過 600 種自有品牌的PXI 模組,其更廣泛的生態系統則提供超過 1500 種模組,為工程師提供豐富的選擇,如同樂高積木一般,涵蓋射頻、混合訊號和電源卡。 ADLINK 正在將其基於 PXI 的參數測試儀推廣至大規模生產線,其吞吐量可與專用機架系統媲美。手持式分析儀填補了現場服務、可再生能源發電電站和通訊塔審計等領域的空白,現在更配備了雲端儀表板,可實現即時報告。這種外形尺寸的融合,維持了電氣和電子測試設備市場的良性競爭。
區域分析
北美佔據了顯著的市場佔有率,這主要得益於國防研發、亞利桑那州半導體晶圓廠的擴張以及5G C頻段基礎設施的部署。聯邦政府的獎勵和經認證的校準實驗室維持著一個成熟的生態系統,該系統強調可追溯性和快速服務。加拿大電信營運商和電動車新創公司進一步推動了對合規服務的需求。
亞太地區年複合成長率達5.22%,預計到2031年將與北美地區並駕齊驅。中國大力發展國內半導體生產、台灣在先進製程節點上的領先地位以及韓國對記憶體領域的投資,都在推動銷售量成長。東南亞國家正扮演製造地的角色,為中階示波器和PXI機架創造了新的市場機會。印度電信業者採用開放式無線存取網(Open RAN)以及日本汽車製造商推進固態電池檢驗,都為電氣和電子測試設備市場帶來了多元化的收入來源。
在歐洲,受汽車電氣化、可再生能源目標以及數位化主權努力的推動,資本投資持續穩定成長,儘管成長緩慢。德國和法國的大規模校準和租賃業務正在蓬勃發展,而北歐國家則在5G先進現場測試方面處於領先地位。東歐的電子製造服務(EMS)供應商正在獲得近岸外包契約,從而提振了對具備網路連接功能的入門級儀器的需求。南美、中東和非洲仍在發展中,但潛力巨大,採礦自動化、大規模太陽能發電和機場維修項目正在推動模組化測試台的初步部署。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 5G及下一代無線技術部署浪潮
- 先進節點半導體的複雜性
- 電動車和電力電子設備的測試需求
- 利用人工智慧/機器學習的自動化測試
- 超寬頻隙裝置的特性分析
- 物聯網網路安全合規性要求
- 市場限制因素
- 高昂的資本成本和向租賃模式的過渡
- 來自亞洲低成本供應商的價格壓力
- 供不應求
- 「修復權」限制了專有協定的使用。
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 主要宏觀經濟趨勢評估
第5章 市場規模與成長預測
- 依產品類型
- 示波器
- 頻譜分析儀和網路分析儀
- 訊號產生器
- 半導體自動測試設備(ATE)
- 射頻和微波測試設備
- 數據採集(DAQ)系統
- 電氣和環境安全測試
- 按外形規格
- 工作檯面
- 可攜式/手持式
- 基於模組化/PXI/PC
- 按應用階段
- 設計、研究和開發;
- 製造和生產
- 安裝和維護
- 認證與合規
- 按最終用戶行業分類
- 通訊與網路
- 半導體和計算
- 汽車/電動車
- 航太/國防
- 家用電子電器和家用電器
- 工業和能源
- 醫療保健和生命科學
- 其他終端用戶產業
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 智利
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 荷蘭
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 其他亞太國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 其他非洲國家
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Keysight Technologies Inc.
- Rohde and Schwarz GmbH and Co. KG
- Fortive Corporation(Fluke, Tektronix)
- National Instruments Corporation(NI)
- Anritsu Corporation
- Teledyne LeCroy Inc.
- Yokogawa Test and Measurement Corporation
- Teradyne Inc.
- Advantest Corporation
- Chauvin Arnoux Group
- VIAVI Solutions Inc.
- EXFO Inc.
- BandK Precision Corporation
- Rigol Technologies Co., Ltd.
- GW Instek(Good Will Instrument Co., Ltd.)
- Hioki EE Corporation
- Chroma ATE Inc.
- Cobham Advanced Electronic Solutions
- Spectrum Instrumentation GmbH
- Signal Hound Inc.
- Pico Technology Ltd.
- Microchip Technology Inc.(Microsemi Timing Systems)
第7章 市場機會與未來展望
According to Mordor Intelligence, the electrical and electronic test equipment market size is expected to grow from USD 15.66 billion in 2025 to USD 16.31 billion in 2026 and is forecast to reach USD 19.95 billion by 2031 at 4.12% CAGR over 2026-2031.
This report is Segmented by Product Type (Oscilloscopes, Spectrum Analyzers, Signal Generators, and More), Form Factor (Benchtop, Portable, and Modular), Application Stage (R&D, Manufacturing, Installation, and Compliance), End-User Industry (Communications, Semiconductors, Automotive, Aerospace, Consumer Electronics, and More), and Geography. Market Forecasts in Value (USD).
Global Electrical And Electronic Test Equipment Market Trends and Insights
5G and Advanced Wireless Deployment Wave
Global 5G infrastructure expansion is driving unprecedented demand for millimeter-wave and sub-6 GHz analyzers, generators and over-the-air chambers. Operators need to validate beamforming, carrier aggregation and satellite backhaul performance across increasingly crowded spectrum allocations. Equipment must now simulate Doppler effects, GNSS timing and non-terrestrial network latency, tasks that conventional terrestrial RF sets cannot handle. Vendors are launching compact CATR ranges that shrink required floor space while retaining quiet-zone fidelity, a key need for consumer-device makers. Demand also flows from private-network deployments in manufacturing plants and logistics hubs, where spectral coexistence and ultra-reliability place fresh verification burdens on test labs. These factors collectively sustain momentum for the electrical and electronic test equipment market as wireless standards evolve toward 5G-Advanced and early 6G research.
Advanced-Node Semiconductor Complexity
Fabricating 3 nm and finer nodes multiplies test vectors as chipmakers adopt multi-die packaging and chiplet architectures. Industry association SEMI forecasts USD 6.7 billion in semiconductor test-equipment sales for 2024, with a 30.3% lift expected in 2025 as device complexity rises. Teradyne and partners now probe both sides of silicon-photonics wafers in one pass, slashing cycle times for co-packaged optics. High-bandwidth memory stacks, AI accelerators and on-package transceivers require tight thermal control and multi-gigabit interface coverage, pushing legacy ATE beyond its limits. Probe-card vendors FormFactor and Technoprobe have gained strategic investment from Advantest to secure next-gen contactor supply. The rising capital spend underpins long-term growth for the electrical and electronic test equipment market by widening addressable workloads.
High Capital Cost and Shift to Rentals
Flagship 5G or semiconductor ATE platforms can exceed USD 1 million apiece, straining capex budgets. Customers increasingly choose rental or subscription models; Electro Rent maintains USD 1.2 billion of inventory to meet these needs. The U.S. Equipment Leasing and Finance Association projects that 54% of equipment acquisitions will be financed in 2024 and expects Equipment-as-a-Service to grow 50% CAGR through 2030. While recurring revenue benefits vendors long term, near-term hardware sales flatten, tempering overall expansion of the electrical and electronic test equipment market.
Other drivers and restraints analyzed in the detailed report include:
- EV and Power-Electronics Test Needs
- AI/ML-Assisted Automated Testing
- Low-Cost Asian Vendor Price Pressure
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The electrical and electronic test equipment market size for oscilloscopes stood at USD 4.61 billion in 2025, translating to a dominant 29.45% slice of total revenue. Oscilloscopes remain indispensable across R&D, validation, and troubleshooting, yet bandwidth ceilings and protocol-decode depth are now differentiators as designs push beyond 70 GHz. RF and microwave instruments are expanding at a 4.63% CAGR thanks to 5G non-terrestrial networks, satellite IoT, and automotive radar. Spectrum analyzers with real-time triggers and signal generators capable of 2 GHz modulation bandwidth are moving from lab to field use. Portable vector-network analyzers such as the 40 GHz USB-powered VNA400 are proof that miniaturization no longer compromises performance.
Semiconductor ATE faces cyclical buying tied to fab expansions but benefits from chiplet architectures that raise pin counts and drive multisite test. Environmental-stress chambers and electrical-safety testers are getting a lift from stricter IEC and UL updates, especially in battery-powered consumer devices. Optical-electrical convergence is spawning hybrid testers that measure insertion loss, eye diagrams, and RF impairments in a single workflow, meeting data-center demand for co-packaged optics. Overall, product diversification underpins revenue stability for the electrical and electronic test equipment market despite pockets of volatility.
Benchtop platforms deliver benchmark accuracy, intuitive front panels and robust input protection, securing 47.12% of 2025 revenue. They dominate early-stage design and university labs, where flexibility outranks rack density. Modular PXI systems, however, are climbing fastest with a 5.02% CAGR as users favor synchronized, software-defined channels for parallel test. The electrical and electronic test equipment market size attributed to PXI setups is forecast to exceed USD 5.18 billion by 2031 as factories digitize quality stations and shorten changeover cycles.
NI counts more than 600 PXI modules under its brand and 1,500 across the broader ecosystem, giving engineers a Lego-like palette of RF, mixed-signal, and power cards. ADLINK extends reach into mass-production lines with PXI-based parametric testers that rival proprietary rack systems on throughput. Handheld analyzers fill gap-filling tasks in field service, renewable-energy farms, and telecom tower audits, now featuring cloud dashboards for instant report generation. This convergence of form factors sustains healthy competition inside the electrical and electronic test equipment market.
Complete Report Scope:
- By Product Type
- Oscilloscopes
- Spectrum and Network Analyzers
- Signal Generators
- Semiconductor Automatic Test Equipment (ATE)
- RF and Microwave Test Equipment
- Data Acquisition (DAQ) Systems
- Electrical and Environmental Safety Test
- By Form Factor
- Benchtop
- Portable / Hand-held
- Modular / PXI / PC-based
- By Application Stage
- Design and R&D
- Manufacturing and Production
- Installation and Maintenance
- Certification and Compliance
- By End-user Industry
- Communications and Networking
- Semiconductors and Computing
- Automotive and Electric Vehicles
- Aerospace and Defense
- Consumer Electronics and Appliances
- Industrial and Energy
- Healthcare and Life Sciences
- Other End-user Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Netherlands
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America generated significant share on the back of defense R&D, fab expansions in Arizona and 5G C-band build-outs. Federal incentives and accredited calibration labs sustain a mature ecosystem that values traceability and rapid service. Canadian telecom carriers and electric-vehicle startups add incremental demand for compliance services.
Asia-Pacific is on track for a 5.22% CAGR and will likely approach parity with North America by 2031. China's push for indigenous semiconductors, Taiwan's leadership in advanced nodes and South Korean investments in memory assist volume growth. Southeast Asian nations provide a manufacturing off-load valve, creating greenfield opportunities for mid-range oscilloscopes and PXI racks. Indian telcos embracing Open RAN and Japanese automakers validating solid-state batteries add diverse revenue streams to the electrical and electronic test equipment market.
Europe shows moderate but stable growth as automotive electrification, renewable-energy targets, and digital-sovereignty initiatives keep capex flowing. Germany and France host significant calibration and rental operations, while Nordic nations pioneer 5G advanced field trials. Eastern European EMS providers attract near-shoring contracts, bolstering demand for entry-level but network-connected instruments. South America and the Middle East and Africa remain nascent yet promising, with mining automation, utility-scale solar, and airport upgrades enabling first-time installations of modular test benches.
- Keysight Technologies Inc.
- Rohde and Schwarz GmbH and Co. KG
- Fortive Corporation (Fluke, Tektronix)
- National Instruments Corporation (NI)
- Anritsu Corporation
- Teledyne LeCroy Inc.
- Yokogawa Test and Measurement Corporation
- Teradyne Inc.
- Advantest Corporation
- Chauvin Arnoux Group
- VIAVI Solutions Inc.
- EXFO Inc.
- BandK Precision Corporation
- Rigol Technologies Co., Ltd.
- GW Instek (Good Will Instrument Co., Ltd.)
- Hioki E.E. Corporation
- Chroma ATE Inc.
- Cobham Advanced Electronic Solutions
- Spectrum Instrumentation GmbH
- Signal Hound Inc.
- Pico Technology Ltd.
- Microchip Technology Inc. (Microsemi Timing Systems)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 5G and Advanced Wireless Deployment Wave
- 4.2.2 Advanced-Node Semiconductor Complexity
- 4.2.3 EV and Power-Electronics Test Needs
- 4.2.4 AI/ML-Assisted Automated Testing
- 4.2.5 Ultra-Wide-Bandgap Device Characterization
- 4.2.6 IoT Cyber-Security Compliance Mandates
- 4.3 Market Restraints
- 4.3.1 High Capital Cost and Shift to Rentals
- 4.3.2 Low-Cost Asian Vendor Price Pressure
- 4.3.3 Precision-Component Supply Shortages
- 4.3.4 Right-to-Repair Curtailing Proprietary Protocols
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Degree of Competition
- 4.8 Assessment of Key Macroeconomic Trends
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Oscilloscopes
- 5.1.2 Spectrum and Network Analyzers
- 5.1.3 Signal Generators
- 5.1.4 Semiconductor Automatic Test Equipment (ATE)
- 5.1.5 RF and Microwave Test Equipment
- 5.1.6 Data Acquisition (DAQ) Systems
- 5.1.7 Electrical and Environmental Safety Test
- 5.2 By Form Factor
- 5.2.1 Benchtop
- 5.2.2 Portable / Hand-held
- 5.2.3 Modular / PXI / PC-based
- 5.3 By Application Stage
- 5.3.1 Design and R&D
- 5.3.2 Manufacturing and Production
- 5.3.3 Installation and Maintenance
- 5.3.4 Certification and Compliance
- 5.4 By End-user Industry
- 5.4.1 Communications and Networking
- 5.4.2 Semiconductors and Computing
- 5.4.3 Automotive and Electric Vehicles
- 5.4.4 Aerospace and Defense
- 5.4.5 Consumer Electronics and Appliances
- 5.4.6 Industrial and Energy
- 5.4.7 Healthcare and Life Sciences
- 5.4.8 Other End-user Industries
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Chile
- 5.5.2.4 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Netherlands
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Keysight Technologies Inc.
- 6.4.2 Rohde and Schwarz GmbH and Co. KG
- 6.4.3 Fortive Corporation (Fluke, Tektronix)
- 6.4.4 National Instruments Corporation (NI)
- 6.4.5 Anritsu Corporation
- 6.4.6 Teledyne LeCroy Inc.
- 6.4.7 Yokogawa Test and Measurement Corporation
- 6.4.8 Teradyne Inc.
- 6.4.9 Advantest Corporation
- 6.4.10 Chauvin Arnoux Group
- 6.4.11 VIAVI Solutions Inc.
- 6.4.12 EXFO Inc.
- 6.4.13 BandK Precision Corporation
- 6.4.14 Rigol Technologies Co., Ltd.
- 6.4.15 GW Instek (Good Will Instrument Co., Ltd.)
- 6.4.16 Hioki E.E. Corporation
- 6.4.17 Chroma ATE Inc.
- 6.4.18 Cobham Advanced Electronic Solutions
- 6.4.19 Spectrum Instrumentation GmbH
- 6.4.20 Signal Hound Inc.
- 6.4.21 Pico Technology Ltd.
- 6.4.22 Microchip Technology Inc. (Microsemi Timing Systems)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 電氣測試設備:市場佔有率分析、產業趨勢及統計、成長預測(2026-2031)
 電磁閥電壓測試儀市場規模、佔有率和成長分析:按產品類型、電壓範圍、應用、工業設備測試、最終用戶和地區分類-2026-2033年產業預測
 全球電力測試系統市場:2026-2036 年電氣和電子測試設備市場:按組件、產品類型、外形規格、應用、最終用戶、國家和地區分類——行業分析、市場規模、市場佔有率和預測(2026-2033 年)
 全球電壓檢測器市場規模、佔有率、趨勢和成長分析報告(2026-2034)
 2026年全球帶電電壓檢測器市場報告
 動態電壓恢復裝置市場:按類型、組件、容量、最終用途和銷售管道分類-2026-2032年全球市場預測2026年全球電壓感測系統市場報告2026年全球電氣測試設備市場報告
 電壓測試器市場 - 全球產業規模、佔有率、趨勢、機會、預測:按產品類型、操作方式、頻率、應用、地區和競爭格局分類,2021-2031年