


 |
市場調查報告書
商品編碼
2123133
智慧城市平台:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Smart City Platform - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
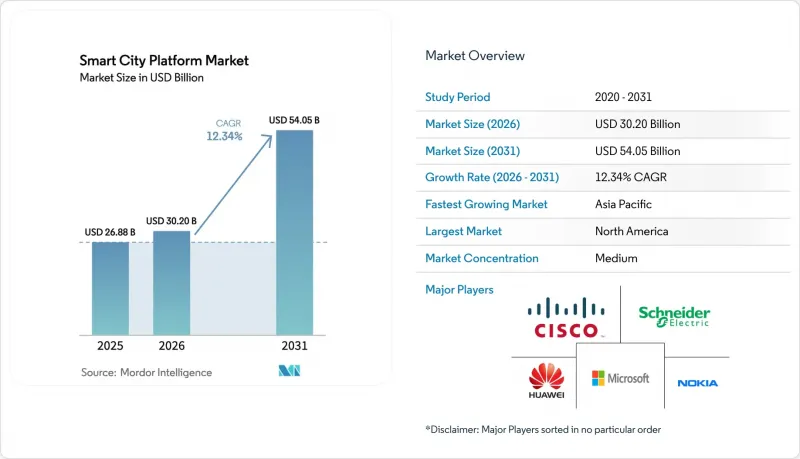
根據 Mordor Intelligence 預測,智慧城市平台市場規模預計將在 2026 年達到 302 億美元,並在 2031 年擴大到 540.5 億美元,在整個預測期內保持 12.34% 的高複合年成長率。
本報告按平台類型(連接管理、整合等)、應用領域(智慧運輸/交通、智慧安防/公共安全等)、部署方式(本地部署、雲端部署等)、最終用戶(政府/地方當局、公用事業/能源公司、醫療保健提供者等)和地區進行細分。市場預測以美元計價。
全球智慧城市平台市場趨勢及洞察
城市基礎設施中物聯網設備的激增
隨著公用事業、環保機構和公共工程部門不斷擴大連網設備的部署,預計到2025年,全球市政物聯網終端數量將達到12億,比2024年增加41%。設備密度差異仍然很大,一線城市平均每人擁有18台設備,而二線城市僅為6台,這要求供應商既要支援高容量、低延遲的工作負載,又要支援受電池容量限制的網路。邊緣推理如今已成為一項設計要求。例如,英特爾的OpenVINO工具包在47個部署案例中將影片分析延遲降低了62%,為額外的感測器部署騰出了頻寬。雖然這種分散式模式降低了回程傳輸成本,但在光纖基礎設施不發達的市場,每GB的成本仍超過0.08美元。因此,供應商的策略著重於資料管道的自動擴展和即插即用的設備接入,以滿足兩極化的需求。
擴大政府智慧城市資金支持計劃
預計到2025年,公共投資將達到384億美元,比上年成長29%,這將成為智慧城市平台市場的關鍵驅動力。 《基礎設施投資與就業法案》撥款12億美元用於數位基礎建設,而歐盟的「數位歐洲計畫」承諾到2027年投入18億歐元(約20億美元)。中國、印度和韓國正在投資二線城市,以縮小都市區差距,並經常強制要求符合NGSI-LD標準,該標準有利於提供開放API的供應商。津貼正在加速相關技術的普及,但同時,也加強了對網路安全狀況和資料管治的審查,促使城市從一開始就將互通性和零信任條款納入其提案文件中。
對資料隱私和網路安全的擔憂
預計2025年,針對地方政府的勒索軟體攻擊將增加34%,平均恢復成本將達420萬美元。歐洲網路與資訊安全指令2(NGSI-LD)現已強制要求在資料外洩發生後24小時內披露信息,違規者將被處以最高可達年收入2%的罰款。監管的收緊將使合規成本增加18%,從而對供應商的盈利造成壓力。 IEEE研究人員表示,強制地方政府對資料進行匿名化處理可能會使人工智慧的準確率降低高達19%。零信任架構可以降低風險,但需要網路分段和持續身份驗證,這通常會使實施延遲長達九個月。這些政策阻力對於醫療和公共安全影像等對隱私敏感的應用尤其嚴重,公眾的反對可能會導致計畫核准停滯不前。
細分市場分析
預計2026年至2031年間,安全管理平台將以13.02%的複合年成長率成長,反映出地方政府迫切需要遏制日益增加的網路安全事件。與該領域的快速成長形成鮮明對比的是,連接管理(2025年市場佔有率最高,達28.73%)由於價格壓力,其收入成長放緩。整合平台(2025年市佔率22%)受惠於城市轉型為微服務架構的趨勢,微服務架構能夠將傳統SCADA系統與現代分析功能整合。設備管理產品(市佔率約18%)正受惠於邊緣AI節點(需要持續韌體更新)的成長。數據管理層完善了市場結構,透過利用NGSI-LD上下文模型確保城市內部不同系統間的語義可攜性,從而鞏固了其在智慧城市平台市場中的地位。
競爭日趨激烈。思科斥資280億美元收購Splunk,標誌著網路可觀測性和安全分析在整合技術堆疊中的整合。成熟的開放原始碼解決方案,例如FIWARE,在基於NGSI-LD的採購中備受青睞,目前歐洲已有89個市政當局採用此採購模式。供應商正在將零信任模組(包括Palo Alto Networks的Prisma SASE功能)整合到23個城市的部署中,以縮小物聯網的攻擊面。招標書措辭也反映了這一轉變,預計2025年將有68%的競標要求包含威脅回應能力。隨著城市要求供應商承擔網路風險,來自託管偵測與回應(MDR)的持續業務收益正成為智慧城市平台產業未來的收入來源。
預計到2031年,智慧醫療的複合年成長率將達到13.55%,超過所有其他應用情境。遠端醫療、救護車路線最佳化和空氣品質相關的醫療服務將成為後疫情時代市政衛生策略的基石。到2025年,智慧基礎設施將佔智慧城市平台市場佔有率的31.84%,這反映了迄今為止的進展,最初的LED維修正在維修為配備人體感應器和自然光感測器的系統。在聯網汽車試點計畫的推動下,移動出行和交通運輸應用約佔24%的市場佔有率。公共安全分析約佔19%。公用事業和能源管理佔16%,主要得益於先進的測量系統,其餘部分則由市民服務入口網站和日益普及的多語言聊天機器人構成。
醫療保健領域的綜效清晰地展現了跨產業價值。例如,首爾的「U-Healthcare」舉措將穿戴式裝置與空氣品質數據結合,向氣喘患者發送即時警報。此外,新加坡的物聯網健身站預計2025年將使園區利用率提高22%。像昕諾飛這樣的照明供應商正在將聲波感測器整合到照明設備中,用於異常檢測,一項試點研究表明,這使警方響應時間縮短了18%。雖然在IEC 62386照明介面中添加網路安全措施會使每台照明設備的成本增加8至12美元,但它們降低了在城市部署的風險,並進一步支持了這樣一種觀點:在智慧城市平台市場中,對韌性的投資如今已被視為一種間接成本。
區域分析
2025年,北美地區的銷售額佔全球的38.74%,這主要得益於聯邦和州政府的津貼項目以及不斷成長的公用事業現代化市場。 Azure數位孿生技術已在芝加哥的2,400棟建築中部署,是該地區注重節能應用案例的典型例證,預計每年可節省1,400萬美元。然而,美國仍缺乏全國性的智慧城市指南,供應商不得不逐州應對相關法規。加拿大7500萬加元(5500萬美元)的智慧城市挑戰基金表明,小規模的經濟體可以透過競爭性津貼來加速專案進展。墨西哥85億墨西哥比索(5億披索)的旅遊計畫凸顯了拉丁美洲日益成長的關注度,但由於2025年遭受網路攻擊後預算重新分配,該計畫的實施進度有所放緩。
亞太地區是成長最快的區域,預計年複合成長率將達到13.78%。這主要得益於數位化浪潮席捲二線城市,而這股浪潮的推動力來自中國1,200億元人民幣(約168億美元)的「新基建計畫」和印度4,800億盧比(約58億美元)的「智慧城市二期計畫」。華為和阿里雲等國內領導廠商正利用數據在地化政策擴大市場佔有率,而日本1,200億日圓(約8.2億美元)的數位孿生計畫在成熟經濟體中也展現出新的發展動能。韓國2.1兆韓元(約16億美元)的基金正將韓國打造成為自動駕駛平台的試驗場。澳洲的開放資料交換平台雖然預算看似小規模,但卻顯著提升了開發者的參與度,並深化了生態系統。
歐洲的發展趨勢以互通性為核心。歐盟一項指令要求在2026年前採用NGSI-LD標準,這迫使供應商在公開其專有方案和失去進入全球最大智慧城市平台市場之一的資格之間做出選擇。光是2025年,英國、德國、法國、義大利和西班牙的國家項目預算總額就將超過19億美元。德國耗資5億歐元(約5.65億美元)的連網聯網汽車改造計畫展示了交通應用將如何與更廣泛的城市平台整合。南歐正在重點撥款以彌合數位鴻溝,義大利4.1億歐元(約4.64億美元)的韌性預算就是一個例證。西班牙的「Red.es」以巴塞隆納的「Sentilo」架構為藍本,投資2.9億歐元(約3.28億美元)來支援市政物聯網框架。
儘管南美洲、中東和非洲仍處於實施初期,但一些突破性計畫正在湧現。巴西已撥款18億雷亞爾(約3.6億美元)用於改善主要城市的交通狀況,但由於與聯邦政府的談判,資金撥付有所延遲。沙烏地阿拉伯耗資5000億美元的「NEOM」計畫將西門子的「MindSphere」系統整合到待開發區基礎設施中。南非已從非洲開發銀行獲得4.8億蘭特(約2,600萬美元)貸款,用於建造智慧水務平台,該平台將減少18%的無收益水。在奈及利亞,一項耗資150億奈拉(約1,000萬美元)的試點計畫正在拉各斯和阿布加進行,旨在測試交通管理和廢棄物收集平台。儘管光纖骨幹網路的缺乏和電力供應的不穩定仍然限制著快速擴張,但混合融資和模組化應用正在為智慧城市平台市場的未來成長奠定基礎。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 市場分析與定義的前提條件
- 分析範圍
第2章 分析方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 城市基礎設施中物聯網設備的激增
- 擴大政府智慧城市資金支持計劃
- 利用人工智慧和雲端技術實現即時分析
- 5G和LPWAN連線的快速普及
- 互通性(NGSI-LD、OASC MIMs)
- 地方政府數據市場貨幣化
- 市場限制因素
- 資料隱私和網路安全問題
- 大量初始資本投資
- 舊有系統中的供應商鎖定問題
- 城市層級資料管治人員短缺
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 宏觀經濟因素影響評估
第5章:預測市場規模與成長率
- 依平台類型
- 連結管理平台
- 整合平台
- 設備管理平台
- 資料管理平台
- 安全管理平台
- 透過使用
- 智慧運輸/交通
- 智慧安防與公共安全
- 智慧公用設施(能源/水)
- 智慧管治與公民服務
- 智慧基礎設施(建築物/路燈)
- 智慧醫療
- 透過部署方法
- 現場
- 雲
- 混合
- 最終用戶
- 政府/地方政府
- 公用事業和能源公司
- 運輸/物流運營商
- 醫療保健提供者
- 其他商業企業
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 英國
- 德國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 澳洲和紐西蘭
- 其他亞太國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 其他非洲國家
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Siemens Aktiengesellschaft
- Schneider Electric SE
- Microsoft Corporation
- Hitachi, Ltd.
- Huawei Technologies Co., Ltd.
- Cisco Systems, Inc.
- General Electric Company
- International Business Machines Corporation
- Alibaba Group Holding Limited
- Amazon Web Services, Inc.
- Oracle Corporation
- SAP SE
- Telefonaktiebolaget LM Ericsson
- Fujitsu Limited
- NEC Corporation
- Itron, Inc.
- Atos SE
- Nokia Corporation
- Quantela, Inc.
- Intel Corporation
- PTC Inc.
- Bosch.IO GmbH
第7章 市場機會與未來展望
According to Mordor Intelligence, the smart city platform market size reached USD 30.20 billion in 2026 and is projected to climb to USD 54.05 billion by 2031, delivering a compelling 12.34% CAGR across the forecast horizon.
This report is Segmented by Platform Type (Connectivity Management, Integration, and More), Application (Smart Mobility/Transportation, Smart Security and Public Safety, and More), Deployment Model (On-Premise, Cloud, and More), End-User (Government and Municipalities, Utilities and Energy Providers, Healthcare Providers, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Smart City Platform Market Trends and Insights
IoT-Device Proliferation Across Urban Infrastructure
Global municipal IoT endpoints reached 1.2 billion in 2025, a 41% increase from 2024, as utilities, environmental agencies, and public works departments scaled up connected devices. Density remains uneven, with tier-one cities averaging 18 devices per capita, while tier-two municipalities average six, obliging platform vendors to support both high-volume, low-latency workloads and battery-constrained networks. Edge inference is now a design prerequisite, for instance, Intel's OpenVINO toolkit trimmed video-analytics latency by 62% in 47 deployments, freeing bandwidth budgets for additional sensors. This distributed pattern reduces backhaul costs, which still exceed USD 0.08 per gigabyte in fiber-poor markets. Vendor strategies, therefore, emphasize auto-scaling data pipelines and plug-and-play device onboarding to address the bifurcated demand profile.
Expanding Government Smart-City Funding Programs
Public investment increased 29% year-over-year to USD 38.4 billion in 2025, creating a vital flywheel for the smart city platform market. The Infrastructure Investment and Jobs Act allocated USD 1.2 billion for U.S. digital infrastructure, while the European Union's Digital Europe Programme committed EUR 1.8 billion (USD 2.0 billion) through 2027. China, India, and South Korea are channeling funds toward tier-two cities to bridge urban-rural gaps, often stipulating NGSI-LD compliance that benefits vendors with open APIs. Grants speed adoption but simultaneously heighten scrutiny of cybersecurity posture and data governance, prompting cities to incorporate interoperability and zero-trust provisions into RFPs from the outset.
Data-Privacy and Cyber-Security Concerns
Municipal ransomware incidents rose 34% in 2025, pushing average remediation costs to USD 4.2 million. Europe's Network and Information Security Directive 2 now requires 24-hour breach disclosure and penalties of up to 2% of annual revenue for non-compliance. Stricter rules strain vendor economics by increasing compliance overhead by 18% and compel cities to anonymize data, a step that can erode AI accuracy by as much as 19%, according to IEEE researchers. Zero-trust architectures mitigate exposure but necessitate network segmentation and continuous authentication, often delaying deployments by nine months. The policy headwind is particularly acute in privacy-sensitive applications such as healthcare and public-safety video, where citizen opposition can stall project approvals.
Other drivers and restraints analyzed in the detailed report include:
- AI and Cloud-Enabled Real-Time Analytics Adoption
- Rapid Roll-Out of 5G and LPWAN Connectivity
- High Up-Front Capital Expenditure
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Security management platforms are on track for a 13.02% CAGR from 2026 to 2031, reflecting municipal urgency to contain escalating cyber incidents. The segment's surge contrasts with connectivity management's 28.73% market-leading share in 2025, where revenue growth is moderating under pricing pressure. Integration platforms, which hold a 22% share in 2025, benefit from cities migrating to microservices that enable them to integrate legacy SCADA systems with contemporary analytics. Device-management products, at roughly 18% share, ride the wave of edge-AI node growth that requires continuous firmware updates. Data-management layers round out the landscape by leveraging NGSI-LD context models to ensure semantic portability across city silos, cementing their role in the smart city platform market.
Competition is intensifying. Cisco's USD 28 billion acquisition of Splunk illustrated how network observability is converging with security analytics in an integrated stack. NGSI-LD-driven procurement favors open-source solutions with a pedigree, such as FIWARE, which is now active in 89 European municipalities. Vendors embed zero-trust modules, including Palo Alto Networks' Prisma SASE features, in 23 city deployments to limit IoT attack surfaces. RFP language mirrors the shift as 68% of 2025 tenders mandate built-in threat response integration. As cities ask suppliers to assume cyber-risk, recurring service revenue from managed detection and response is emerging as a future profit pool within the smart city platform industry.
Smart healthcare is projected to register a 13.55% CAGR to 2031, outpacing every other use case as telemedicine, ambulance routing, and air-quality-linked care become staples of post-pandemic municipal health strategies. Smart infrastructure retained 31.84% of the smart city platform market share in 2025, reflecting the legacy outcome of early LED retrofits that have now been retrofitted with occupancy and daylight sensors. Mobility and transportation applications held roughly 24% share, aided by connected-vehicle pilots, while public-safety analytics contributed about 19%. Utilities and energy management captured 16%, mainly from advanced metering, and citizen-service portals comprise the remainder, with multilingual chatbots gaining traction.
Healthcare synergies illustrate cross-domain value, such as Seoul's U-Healthcare initiative, which combines wearable and air-quality datasets to alert asthma patients in real-time. Singapore's IoT fitness stations raised park usage 22% in 2025. Lighting vendors, such as Signify, embed acoustic sensors in luminaires for anomaly detection, resulting in an 18% reduction in police response times in pilot studies. Cybersecurity controls added to IEC 62386 lighting interfaces increase fixture costs by USD 8-12 per unit, but de-risk citywide rollouts, further proving that resilience premiums are now accepted as an overhead in the smart city platform market.
Complete Report Scope:
- By Platform Type
- Connectivity Management Platform
- Integration Platform
- Device Management Platform
- Data Management Platform
- Security Management Platform
- By Application
- Smart Mobility / Transportation
- Smart Security and Public Safety
- Smart Utilities (Energy / Water)
- Smart Governance and Citizen Services
- Smart Infrastructure (Buildings / Street Lighting)
- Smart Healthcare
- By Deployment Model
- On-Premise
- Cloud
- Hybrid
- By End-User
- Government and Municipalities
- Utilities and Energy Providers
- Transportation and Logistics Operators
- Healthcare Providers
- Other Commercial Enterprises
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia and New Zealand
- Rest of Asia Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America accounted for 38.74% of the revenue in 2025, driven by federal and provincial grant programs and a growing utility modernization market. Chicago's Azure Digital Twins rollout across 2,400 buildings exemplifies the region's tilt toward energy-efficiency use cases, with projected annual savings of USD 14 million. Yet procurement fragmentation persists because the United States lacks a national smart-city mandate, forcing vendors to navigate disparate state rules. Canada's CAD 75 million (USD 55 million) Smart Cities Challenge funds illustrate how smaller economies catalyze projects through competitive grants. Mexico's MXN 8.5 billion (USD 500 million) mobility effort demonstrates rising Latin American interest, although budget reallocations after a 2025 cyber breach slowed implementation.
Asia-Pacific is the fastest-growing region, forecast at a 13.78% CAGR as China's CNY 120 billion (USD 16.8 billion) New Infrastructure Initiative and India's INR 48,000 crore (USD 5.8 billion) Smart Cities Mission phase two pull tier-two cities into the digital fold. Domestic champions such as Huawei and Alibaba Cloud leverage data-localization policies to capture share, while Japan's JPY 120 billion (USD 820 million) digital-twin program signals renewed momentum in mature economies. South Korea's KRW 2.1 trillion (USD 1.6 billion) fund positions the nation as a testing ground for autonomous mobility platforms. Australia's open-data exchanges appear small in budget terms but generate outsized developer engagement that broadens ecosystem depth.
Europe's trajectory pivots on interoperability mandates. The EU directive to adopt NGSI-LD by 2026 forces vendors to open proprietary schemas or forfeit access to one of the world's largest smart city platform markets. National programs in the United Kingdom, Germany, France, Italy, and Spain collectively exceed USD 1.9 billion for 2025 alone. Germany's EUR 500 million (USD 565 million) connected-vehicle retrofit illustrates how transport applications integrate with broader city platforms. Southern Europe receives targeted allocations to narrow digital divides, evidenced by Italy's EUR 410 million (USD 464 million) resiliency budget. Spain's Red.es backs municipal IoT frameworks with EUR 290 million (USD 328 million), employing Barcelona's Sentilo architecture as a blueprint.
South America, the Middle East, and Africa remain in early adoption mode yet supply landmark projects. Brazil earmarked BRL 1.8 billion (USD 360 million) for mobility upgrades in major cities, although federal negotiations have delayed disbursement. Saudi Arabia's USD 500 billion NEOM integrates Siemens MindSphere for greenfield infrastructure. South Africa secured African Development Bank financing for a ZAR 480 million (USD 26 million) smart-water platform that slashes non-revenue water by 18%. Nigeria's NGN 15 billion (USD 10 million) pilot in Lagos and Abuja test-beds traffic management and waste-collection platforms. Limited fiber backbones and power instability still curtail rapid expansion, yet blended finance and modular deployments create footholds for future scaling of the smart city platform market.
- Siemens Aktiengesellschaft
- Schneider Electric SE
- Microsoft Corporation
- Hitachi, Ltd.
- Huawei Technologies Co., Ltd.
- Cisco Systems, Inc.
- General Electric Company
- International Business Machines Corporation
- Alibaba Group Holding Limited
- Amazon Web Services, Inc.
- Oracle Corporation
- SAP SE
- Telefonaktiebolaget LM Ericsson
- Fujitsu Limited
- NEC Corporation
- Itron, Inc.
- Atos SE
- Nokia Corporation
- Quantela, Inc.
- Intel Corporation
- PTC Inc.
- Bosch.IO GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 IoT-Device Proliferation Across Urban Infrastructure
- 4.2.2 Expanding Government Smart-City Funding Programs
- 4.2.3 AI- and Cloud-Enabled Real-Time Analytics Adoption
- 4.2.4 Rapid Roll-Out of 5G and LPWAN Connectivity
- 4.2.5 Interoperability Mandates (NGSI-LD, OASC MIMs)
- 4.2.6 Monetisation of Municipal Data Marketplaces
- 4.3 Market Restraints
- 4.3.1 Data-Privacy and Cyber-security Concerns
- 4.3.2 High Up-Front Capital Expenditure
- 4.3.3 Legacy-System Vendor Lock-In
- 4.3.4 Shortage of City-Level Data-Governance Talent
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Assessment of Impact of Macroeconomic Factors
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Platform Type
- 5.1.1 Connectivity Management Platform
- 5.1.2 Integration Platform
- 5.1.3 Device Management Platform
- 5.1.4 Data Management Platform
- 5.1.5 Security Management Platform
- 5.2 By Application
- 5.2.1 Smart Mobility / Transportation
- 5.2.2 Smart Security and Public Safety
- 5.2.3 Smart Utilities (Energy / Water)
- 5.2.4 Smart Governance and Citizen Services
- 5.2.5 Smart Infrastructure (Buildings / Street Lighting)
- 5.2.6 Smart Healthcare
- 5.3 By Deployment Model
- 5.3.1 On-Premise
- 5.3.2 Cloud
- 5.3.3 Hybrid
- 5.4 By End-User
- 5.4.1 Government and Municipalities
- 5.4.2 Utilities and Energy Providers
- 5.4.3 Transportation and Logistics Operators
- 5.4.4 Healthcare Providers
- 5.4.5 Other Commercial Enterprises
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia and New Zealand
- 5.5.4.6 Rest of Asia Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Siemens Aktiengesellschaft
- 6.4.2 Schneider Electric SE
- 6.4.3 Microsoft Corporation
- 6.4.4 Hitachi, Ltd.
- 6.4.5 Huawei Technologies Co., Ltd.
- 6.4.6 Cisco Systems, Inc.
- 6.4.7 General Electric Company
- 6.4.8 International Business Machines Corporation
- 6.4.9 Alibaba Group Holding Limited
- 6.4.10 Amazon Web Services, Inc.
- 6.4.11 Oracle Corporation
- 6.4.12 SAP SE
- 6.4.13 Telefonaktiebolaget LM Ericsson
- 6.4.14 Fujitsu Limited
- 6.4.15 NEC Corporation
- 6.4.16 Itron, Inc.
- 6.4.17 Atos SE
- 6.4.18 Nokia Corporation
- 6.4.19 Quantela, Inc.
- 6.4.20 Intel Corporation
- 6.4.21 PTC Inc.
- 6.4.22 Bosch.IO GmbH
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

 城市交通數據平台市場預測至2034年—按平台類型、部署模式、應用、最終用戶和區域分類的全球分析
 2026-2030年全球智慧城市平台市場智慧城市平台市場預測至2034年-按解決方案類型、技術層、部署模式、應用、最終用戶和區域分類的全球分析
 智慧城市平台市場-2026-2032年全球市場預測智慧連結編配市場預測至2034年-按組件、部署模式、指導類型、應用、最終用戶和地區分類的全球分析
 智慧城市平台市場規模、佔有率和趨勢分析報告:按服務類型、技術、部署模式、應用、地區和細分市場預測(2026-2033 年)人工智慧智慧城市平台市場預測至2034年:按組件、技術、應用、部署模式、最終用戶和區域分類的全球分析
 智慧城市平台市場報告:按平台類型、部署模式、應用程式和地區分類(2026-2034 年)
 2026年全球智慧城市平台市場報告
 智慧城市平台市場分析及預測(至2035年):按類型、產品類型、服務、技術、組件、應用、部署類型、最終用戶、解決方案和功能分類