


 |
市場調查報告書
商品編碼
2123073
虛擬私人網路:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)Virtual Private Network - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,虛擬私人網路 (VPN) 市場規模將從 2025 年的 612.6 億美元成長到 2026 年的 704.6 億美元,然後在 2031 年達到 1420.6 億美元,2026 年至 2031 年的複合年成長率為 15.05%。
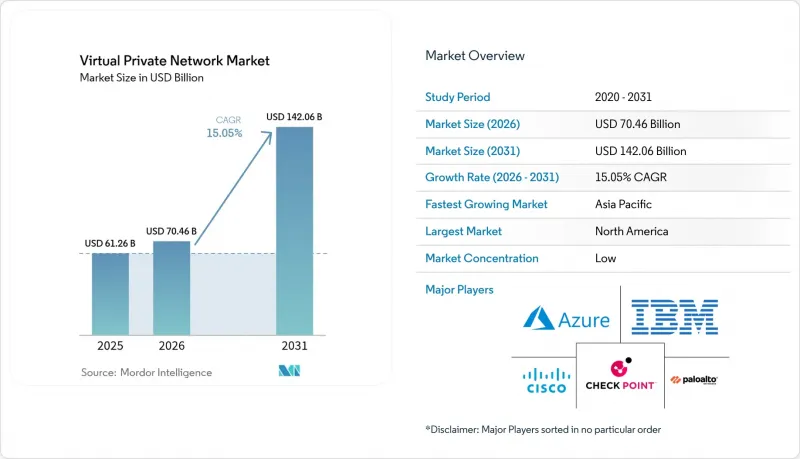
本報告按元件(硬體、軟體、服務)、類型(託管/管理型、IPsec VPN、MPLS VPN 等)、部署模式(雲端、本地部署)、最終用戶產業(銀行、金融服務和保險、醫療保健/生命科學、IT/電信等)和地區進行細分。市場預測以美元計價。
全球虛擬私人網路 (VPN) 市場趨勢與洞察
混合辦公模式越來越依賴安全的遠端存取。
隨著工作方式的改變,VPN 連線已成為企業營運的必要組成部分。紐約市教育局已將超過 100 萬用戶和 200 多萬台設備遷移到零信任框架,並報告攻擊減少了 15%,攔截的威脅增加了 40%。企業正擴大採用雲端原生 SASE 平台,將流量直接路由到應用程式,從而消除了傳統集中器帶來的延遲和修補程式維護負擔。
物聯網設備激增,需要加密連接
工業網路現在需要精細化的、基於身分的存取控制。思科的安全設備存取 (SEA) 解決方案可對操作技術(OT) 資源提供精細的零信任控制,從而取代遠端 VPN 隧道。在廣東大學,中國移動的 5G VPN 將下行速度提升了十倍,並支援 2 萬個同時上線用戶。
VPN/SASE 管理人員短缺導致整體擁有成本上升。
對熟練工程師的需求超過了供應,迫使企業轉向託管服務。服務供應商表示,由於人事費用目前佔總營運支出的近30%,客戶正被能夠減少人工維護工作的整合式SASE解決方案所吸引。
細分市場分析
到 2025 年,硬體設備將佔虛擬私人網路 (VPN) 市場的 42.80%,為許多大規模遠端存取部署提供支援。該細分市場的強勁成長得益於業界較長的更新周期,以及對本地部署合規性的嚴格要求。同時,軟體市場正以 15.72% 的複合年成長率 (CAGR) 成長,這主要得益於容器化閘道器和虛擬防火牆的普及,它們可以在幾分鐘內部署到超大規模雲端平台。半導體供應鏈的緊張狀況推動了雲端託管鏡像(例如 AWS 和 Azure 上的 pfSense Plus)的普及,加速了概念驗證(PoC) 專案的推進。隨著向 SASE 模式的轉變,業務收益(涵蓋託管營運和部署專案)也在不斷成長,如今已成為基於組件支出的第三大支柱。企業正在將用於提升本地性能的硬體與用於擴展覆蓋範圍的軟體閘道器相結合,這表明兩者正在走向共存而非相互替代。
隨著企業將維護負擔轉移給專業服務商,到2025年,託管式服務將佔據虛擬私人網路 (VPN) 市場的24.45%。這些服務將持續更新、威脅情報來源和全天候監控整合到可預測的訂閱模式中。同時,MPLS VPN 也呈現復甦跡象,隨著企業對混合雲端和關鍵任務協作的確定性延遲需求增加,其複合年成長率 (CAGR) 達到16.52%。雲端 VPN 和更廣泛的 SASE 套件正在將 IPsec、SD-WAN 和防火牆即服務 (FWaaS) 整合到統一的編配中,從而消除策略停滯。 IPsec VPN 對於遵循既定協定認證的國防和政府機構仍然至關重要,而新興的 WireGuard 解決方案則強調精簡的程式碼庫和接近線速的吞吐量。
區域分析
北美地區預計在2025年仍將是最大的區域市場,佔虛擬私人網路(VPN)市場收入的26.85%。早期零信任部署試點和嚴格的資料外洩揭露法規正在推動市場支出持續成長。聯邦和州政府專案正在加速從IPsec集中器到以身分為中心的SASE節點的升級,而超大規模資料中心業者則透過部署高密度存取點(PoP)來降低分散式使用者的延遲。
亞太地區正經歷最快成長,複合年成長率達15.96%。大規模數位化專案以及網路保險參保率的不斷提高,正迫使企業保障雲端工作負載和行動工作人員的安全。中國某大學的試點計畫表明,在5G獨立組網(SA)網路上,加密連線的效能比行動VPN提升了十倍。印度金融監管機構目前強制要求外包處理中心使用加密連接,將進一步加速加密技術的普及。
在歐洲,一般資料保護規則(GDPR) 的實施正穩步推進。企業優先選擇資料中心位於歐洲地區的供應商,以確保自身資料主權,許多企業也將預防資料外泄功能整合到其 VPN 中,作為合規措施。德國和法國的政府計畫已明確表示,支持後量子密碼技術是新遠端存取採購的必要條件。
同時,在中東和非洲,星鏈的部署已將寬頻網路擴展到農村地區,VPN服務正被用於保護新興電子商務和電子政府的流量安全。在拉丁美洲,巴西的銀行和墨西哥的零售商正在採用託管VPN來彌補當地勞動力短缺的問題,其使用範圍正在擴大。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 混合辦公模式下對安全遠端存取的依賴性日益增強
- 需要加密連線的物聯網設備數量激增
- 勒索軟體攻擊成本的不斷攀升正在推動對零信任網路的投資。
- 雲端原生應用程式的日益普及推動了對雲端 VPN 和 SASE(安全帳戶系統)的需求。
- 隱私法規(GDPR、CPRA、LGPD)的出現正在推動企業採用 VPN。
- 新興地區衛星寬頻的普及為VPN開闢了新的客戶群。
- 市場限制因素
- VPN/SASE 管理方面熟練人員的短缺正在推高總體擁有成本。
- 與 SDP 和 ZTNA 方案相比,性能/延遲有所下降。
- 監管機構正在加強對消費者 VPN 日誌記錄做法的審查。
- 超過 400 個零售 VPN 品牌之間的價格競爭給利潤率帶來了壓力。
- 供應鏈分析
- 監理情勢
- 技術趨勢(WireGuard、後量子密碼學和SASE的融合)
- 波特五力模型
- 市場宏觀經濟因素的評估
第5章 市場規模與成長預測
- 按組件
- 硬體
- 軟體
- 服務
- 按類型
- 託管/管理
- IPsec VPN
- MPLS VPN
- 雲端 VPN/SASE
- 其他
- 部署模式
- 雲
- 現場
- 按最終用戶行業分類
- BFSI
- 醫療保健和生命科學
- 資訊科技/通訊
- 政府/公共部門
- 製造業和工業
- 零售與電子商務
- 教育
- 其他
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 荷蘭
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 澳洲和紐西蘭
- 其他亞太國家
- 中東和非洲
- 中東
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 其他非洲國家
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Cisco Systems Inc.
- Microsoft Corp.(Azure)
- Palo Alto Networks Inc.
- Check Point Software Technologies Ltd.
- IBM Corp.
- Nord Security(NordVPN)
- Kape Technologies PLC(ExpressVPN, CyberGhost)
- Avast sro(AVG Secure)
- Fortinet Inc.
- Juniper Networks Inc.
- OpenVPN Inc.
- Citrix Systems Inc.
- Array Networks Inc.
- NetMotion Software Inc.(Absolute Secure Access)
- Golden Frog GmbH(VyprVPN)
- Cloudflare Inc.(Cloudflare One/WARP)
- Google LLC(Google VPN)
- McAfee LLC
- Sophos Ltd.
- F5 Inc.(BIG-IP APM)
- Zscaler Inc.(Zscaler Private Access)
- Barracuda Networks Inc.
- Perimeter 81 Ltd.
- Tailscale Inc.
- WireGuard Development Team
第7章 市場機會與未來展望
According to Mordor Intelligence, the virtual private network market size is expected to grow from USD 61.26 billion in 2025 to USD 70.46 billion in 2026 and is forecast to reach USD 142.06 billion by 2031 at 15.05% CAGR over 2026-2031.
This report is Segmented by Component (Hardware, Software, Services), Type (Hosted/Managed, Ipsec VPN, MPLS VPN and More), Deployment Mode (Cloud, On-Premise), End-User Industry (BFSI, Healthcare and Life Sciences, IT and Telecom and More), and by Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Virtual Private Network Market Trends and Insights
Rising Hybrid-Workforce Dependence on Secure Remote Access
Shifts in work patterns have elevated VPN connectivity to business-critical status. The New York City Department of Education migrated more than 1 million users and 2 million devices to a zero-trust framework and reported a 15% reduction in attacks alongside a 40% increase in blocked threats. Enterprises increasingly adopt cloud-native SASE platforms that route traffic directly to applications, eliminating the latency and patching burdens found in traditional concentrators.
Proliferation of IoT Devices Requiring Encrypted Connectivity
Industrial networks now demand granular, identity-based access. Cisco's Secure Equipment Access replaces broad VPN tunnels with fine-grained, zero-trust controls for operational technology resources. At Guangdong University, China Mobile's 5G VPN delivered ten-fold downlink speed versus legacy solutions while supporting 20,000 concurrent users.
Talent Shortage in VPN/SASE Administration Inflating Total Cost of Ownership
Demand for skilled engineers exceeds supply, pushing organizations toward managed services. Providers report staffing outlays approaching 30% of total operating expense, steering customers to integrated SASE offerings that reduce manual upkeep.
Other drivers and restraints analyzed in the detailed report include:
- Escalating Ransomware Losses Driving Zero-Trust Network Spending
- Cloud-Native Application Adoption Boosting Demand for Cloud VPN and SASE
- Performance and Latency Penalties Versus SDP and ZTNA Alternatives
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hardware appliances accounted for 42.80% of the virtual private network market in 2025, underpinning many large-scale remote access roll-outs. Segment resilience is tied to long refresh cycles in sectors with on-premises compliance mandates. Yet software is growing at a 15.72% CAGR, fueled by containerized gateways and virtual firewalls that deploy in minutes on hyperscale clouds. Supply-chain tightness around semiconductors catalyzed adoption of cloud-hosted images such as pfSense Plus on AWS and Azure, accelerating proofs of concept. Services revenue, spanning managed operations and implementation projects, scales in tandem with SASE transitions and currently forms the third pillar of component spend. Organizations continue to blend hardware for on-site performance with software gateways to extend reach, signalling coexistence rather than replacement.
Hosted and managed offerings secured 24.45% of virtual private network market share in 2025 as enterprises shifted maintenance burdens to specialists. These services integrate continuous updates, threat intelligence feeds, and 24X7 monitoring within predictable subscription models. Meanwhile, MPLS VPN shows a renaissance, pacing at 16.52% CAGR as firms require deterministic latency for hybrid cloud and mission-critical collaboration. Cloud VPN and broader SASE suites converge IPsec, SD-WAN, and firewall-as-a-service under unified orchestration, trimming policy sprawl. IPsec VPN remains essential for defense and government entities adhering to established protocol accreditation, while emerging WireGuard solutions emphasize streamlined code bases and near-line-rate throughput.
Complete Report Scope:
- By Component
- Hardware
- Software
- Services
- By Type
- Hosted / Managed
- IPsec VPN
- MPLS VPN
- Cloud VPN / SASE
- Others
- By Deployment Mode
- Cloud
- On-premise
- By End-User Industry
- BFSI
- Healthcare and Life Sciences
- IT and Telecom
- Government and Public Sector
- Manufacturing and Industrial
- Retail and E-Commerce
- Education
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Netherlands
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America remained the largest regional contributor with 26.85% of virtual private network market revenue in 2025. Spending momentum is sustained by early zero-trust pilots and stringent breach disclosure regulations. Federal and state programs accelerate upgrades from IPsec concentrators to identity-centric SASE nodes, while hyperscalers' dense PoP distribution keeps latency low for dispersed users.
Asia-Pacific delivers the fastest expansion at 15.96% CAGR. Massive digitization programs, combined with rising cyber insurance uptake, push enterprises to secure cloud workloads and mobile workforces. Trials in Chinese universities demonstrate ten-fold performance gains for mobile VPN on 5G stand-alone networks. India's financial regulators now require encrypted connectivity for outsourced processing centers, further catalyzing adoption.
Europe maintains steady progress under General Data Protection Regulation enforcement. Enterprises prefer providers with in-region data centers to ensure sovereignty, and many layer VPN with data-loss prevention for compliance. Government projects in Germany and France specify post-quantum readiness in new remote access procurement.
Meanwhile, Middle East and Africa benefit from Starlink roll-outs that extend broadband to rural districts; VPN services ride on top to protect emerging e-commerce and e-government traffic. Latin America gains traction as Brazilian banks and Mexican retailers embrace managed VPN to bypass local talent shortages.
- Cisco Systems Inc.
- Microsoft Corp. (Azure)
- Palo Alto Networks Inc.
- Check Point Software Technologies Ltd.
- IBM Corp.
- Nord Security (NordVPN)
- Kape Technologies PLC (ExpressVPN, CyberGhost)
- Avast s.r.o. (AVG Secure)
- Fortinet Inc.
- Juniper Networks Inc.
- OpenVPN Inc.
- Citrix Systems Inc.
- Array Networks Inc.
- NetMotion Software Inc. (Absolute Secure Access)
- Golden Frog GmbH (VyprVPN)
- Cloudflare Inc. (Cloudflare One / WARP)
- Google LLC (Google VPN)
- McAfee LLC
- Sophos Ltd.
- F5 Inc. (BIG-IP APM)
- Zscaler Inc. (Zscaler Private Access)
- Barracuda Networks Inc.
- Perimeter 81 Ltd.
- Tailscale Inc.
- WireGuard Development Team
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising hybrid-workforce dependence on secure remote access
- 4.2.2 Proliferation of IoT devices requiring encrypted connectivity
- 4.2.3 Escalating ransomware losses driving zero-trust network spending
- 4.2.4 Cloud-native application adoption boosting demand for Cloud VPN and SASE
- 4.2.5 Emergence of privacy regulations (GDPR, CPRA, LGPD) spurring corporate VPN roll-outs
- 4.2.6 Satellite broadband expansion in emerging regions unlocking new VPN user bases
- 4.3 Market Restraints
- 4.3.1 Talent shortage in VPN/SASE administration inflating total cost of ownership
- 4.3.2 Performance/latency penalties versus SDP and ZTNA alternatives
- 4.3.3 Heightened regulatory scrutiny on consumer VPN logging practices
- 4.3.4 Commodity pricing wars among 400+ retail VPN brands squeezing margins
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook (WireGuard, Post-Quantum, SASE Convergence)
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Assesment of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Hardware
- 5.1.2 Software
- 5.1.3 Services
- 5.2 By Type
- 5.2.1 Hosted / Managed
- 5.2.2 IPsec VPN
- 5.2.3 MPLS VPN
- 5.2.4 Cloud VPN / SASE
- 5.2.5 Others
- 5.3 By Deployment Mode
- 5.3.1 Cloud
- 5.3.2 On-premise
- 5.4 By End-User Industry
- 5.4.1 BFSI
- 5.4.2 Healthcare and Life Sciences
- 5.4.3 IT and Telecom
- 5.4.4 Government and Public Sector
- 5.4.5 Manufacturing and Industrial
- 5.4.6 Retail and E-Commerce
- 5.4.7 Education
- 5.4.8 Others
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Netherlands
- 5.5.3.5 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia and New Zealand
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 United Arab Emirates
- 5.5.5.1.2 Saudi Arabia
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials, Strategic Info, Market Share, Products and Services, Recent Developments)
- 6.4.1 Cisco Systems Inc.
- 6.4.2 Microsoft Corp. (Azure)
- 6.4.3 Palo Alto Networks Inc.
- 6.4.4 Check Point Software Technologies Ltd.
- 6.4.5 IBM Corp.
- 6.4.6 Nord Security (NordVPN)
- 6.4.7 Kape Technologies PLC (ExpressVPN, CyberGhost)
- 6.4.8 Avast s.r.o. (AVG Secure)
- 6.4.9 Fortinet Inc.
- 6.4.10 Juniper Networks Inc.
- 6.4.11 OpenVPN Inc.
- 6.4.12 Citrix Systems Inc.
- 6.4.13 Array Networks Inc.
- 6.4.14 NetMotion Software Inc. (Absolute Secure Access)
- 6.4.15 Golden Frog GmbH (VyprVPN)
- 6.4.16 Cloudflare Inc. (Cloudflare One / WARP)
- 6.4.17 Google LLC (Google VPN)
- 6.4.18 McAfee LLC
- 6.4.19 Sophos Ltd.
- 6.4.20 F5 Inc. (BIG-IP APM)
- 6.4.21 Zscaler Inc. (Zscaler Private Access)
- 6.4.22 Barracuda Networks Inc.
- 6.4.23 Perimeter 81 Ltd.
- 6.4.24 Tailscale Inc.
- 6.4.25 WireGuard Development Team
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 虛擬私人網路 (VPN) 市場:按元件、類型、接取技術、平台、驗證方法、最終用戶產業、組織規模、定價模式和部署模式分類——2026-2032 年全球市場預測
 2026年全球網際網路協定(IP)多重協定標籤交換(MPLS)市場報告
 Frost Radar™:北美專用網路接入,2026 年2026年全球多重協定標籤交換(MPLS)虛擬私人網路(VPN)市場報告2026年全球專用網路市場報告
 站點到站點 VPN 市場規模、佔有率和成長分析:按組件、部署類型、連接方式、組織規模、最終用戶和地區分類—2026-2033 年行業預測2026年全球多重協定標籤交換(MPLS)、網際網路協定(IP)和虛擬私人網路(VPN)服務市場報告2026年全球多重協定標籤交換(MPLS)、網際網路通訊協定(IP)和虛擬私人網路(VPN)服務市場報告2026年全球專用網路存取市場報告2026年全球站點到站點虛擬私人網路(VPN)市場報告