


 |
市場調查報告書
商品編碼
2122981
自動化液體處理系統:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)Automated Liquid Handlers - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
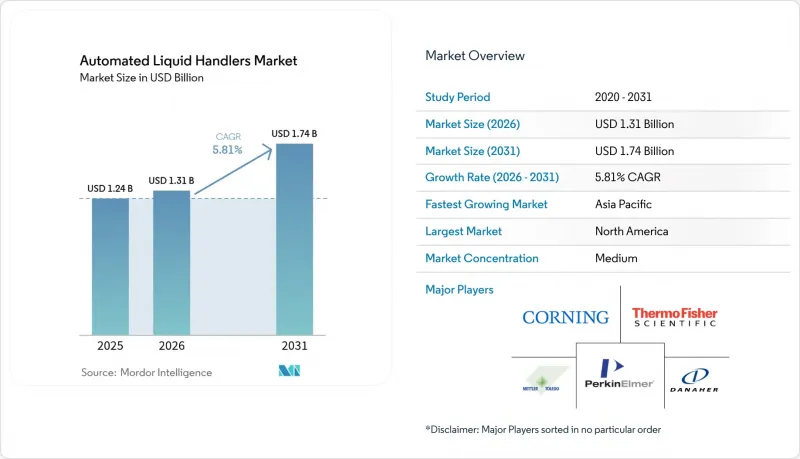
根據 Mordor Intelligence 預測,自動化液體處理設備的市場規模預計將從 2025 年的 12.4 億美元成長到 2026 年的 13.1 億美元,然後在 2031 年達到 17.4 億美元,2026 年至 2031 年的複合年成長率為 5.81%。
本報告按產品類型(例如,機器人液體處理工作站)、處理能力(低、中、高)、平台配置(獨立式桌上型系統、整合式模組化平台)、應用(例如,藥物發現、基因組學)、最終用戶(例如,合約研究組織 (CRO) 和合約生產組織 (CMO))以及地區進行細分。市場預測以價值(美元)表示。
全球自動化液體處理設備市場趨勢及洞察
與人工智慧驅動的藥物發現平台整合,可以加快從發現先導化合物到獲得先導化合物的進程。
自動化工作站與機器學習演算法協同工作,如今無需人工干預即可執行迭代的「設計、運行、分析」循環。配備<sup>19</sup>F NMR感測器的機器人可以並行評估21種反應,使藥物研發團隊能夠將先導化合物的發現週期縮短75%。Astra Zeneca和威爾康奈爾大學的案例研究表明,這些封閉回路型系統提高了協同化合物預測的準確性,同時收集詳細的檢測元資料,用於深度學習模型。節省的時間和豐富的數據直接轉化為更快的專利申請速度和更高的臨床成功率,這正是自動化液體處理市場如何與製藥業的數位轉型保持同步的原因。
大規模基因組篩檢(北美)對處理容量要求不斷提高
疫情期間,美國的參考實驗室擴大了規模,目前每天處理數千個臨床基因組樣本。像 Biomek Echo One 這樣的機器人移液解決方案已將樣本製備時間從兩小時縮短至十分鐘。每個樣本的定序成本可降至 100 美元以下,為檢查室帶來顯著的經濟效益,而這只有在工作流程完全自動化的情況下才能實現。隨著保險公司擴大次世代定序的承保範圍,高通量系統正成為標準配置,進一步鞏固了北美在自動化液體處理市場的主導地位。
新興市場靈活辦公空間的初始資本投入較高
進口關稅和多層流通結構導致標價上漲高達116%,在非洲部分地區,原價35萬美元的系統售價超過75萬美元。津貼很少涵蓋培訓或維護,迫使實驗室簽訂昂貴的服務合約。因此,技術差距正在擴大,新興市場面臨被全球基因組聯盟排除在外的風險,並減緩了這些地區自動化液體處理市場的成長。
細分市場分析
在自動化液體處理市場中,機器人工作站佔據最大的市場佔有率,預計2025年仍將維持45.72%的市場佔有率。這是因為實驗室仍然優先考慮機械精度,以實現高度可重複的移液操作。同時,軟體和服務領域預計將以7.59%的複合年成長率成長,因為用於設定執行計劃和預測吸頭使用情況的人工智慧模組能夠即時降低成本。機器人部署數量的不斷增加確保了對耗材的持續需求,其中註入潤滑劑的吸頭可以減少黏稠樣本中的殘留。
產品配置正轉向平台授權模式,以支援工作流程庫和雲端分析功能。供應商現在將基於訂閱的儀表板捆綁銷售,這些儀表板可以監控運作並檢測異常情況,從而進一步提升軟體收入。這種轉變正在改變競爭格局,促進生態系統夥伴關係,並使程式碼庫成為自動化流體處理設備市場的核心差異化因素。
到2025年,每次運行處理100至1000個樣本的中等通量系統將佔自動化液體處理系統市場規模的53.12%。這些系統符合臨床檢查室和中型生物技術公司典型的批量處理量,在速度和價格之間取得了良好的平衡。而每次運行處理超過1000個樣本的高通量系統將以6.21%的複合年成長率實現最高成長,這主要得益於藥物研發領域每天超過10萬次檢測的大規模篩檢宣傳活動。
隨著每日處理的培養皿數量超過 5000 片,單位經濟效益顯著提升,促使合約研究組織 (CRO) 在處理能力出現瓶頸之前升級設備。這一趨勢支撐了配備多臂配置和擴展吸頭架的機器人平台的溢價。此外,預測性維護方面的服務機會也不斷擴大,從而提高了自動化液體處理市場的收入穩定性。
區域分析
北美擁有完善的分子診斷基礎設施和集中的製藥產業叢集,預計2025年將佔據自動化液體處理設備市場38.10%的佔有率。總部位於美國的賽默飛世爾科技公司已投資20億美元用於本土生產,以確保更短的供應鏈和合規支援。加拿大在基因組學研究領域實力雄厚,墨西哥正在農業基因組學領域引入自動化技術。該地區正受益於創業投資對人工智慧實驗室技術新創企業的資助,但機器人程式設計人才的短缺仍然限制著企業的規模化發展。
亞太地區是成長最快的地區,預計到2031年將以6.82%的複合年成長率成長,這主要得益於中國1兆元人民幣的機器人技術舉措和韓國1.28億美元的智慧機器人計畫。日本正利用其數十年的自動化傳統,而澳洲則利用聯邦津貼建造符合GMP標準的生物程序設施。本地化服務中心正在減少停機時間,並克服對進口技術人員的傳統依賴。政府有利於國內供應商的採購政策正在加速部署規模的擴大,以鞏固亞太地區作為自動化液體處理市場主要收入成長來源的地位。
歐洲憑藉德國、英國和法國強大的製藥產品線,在自動化液體處理市場中保持著強勁的地位。歐盟內部的監管協調促進了跨境技術轉讓,而永續性法規則優先採用經檢驗二氧化碳排放量的機器人。南歐的實驗室正透過將自動化技術應用於食品和環境檢測,拓展目標市場。與設備供應商合作的學徒計畫正在彌補技能缺口,確保設備穩定運轉率並降低服務成本。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 北美地區大規模基因組篩檢對處理能力的需求日益成長
- 採用緊湊型檢測方法以降低試劑成本
- 透過與人工智慧驅動的藥物發現平台合作,從先導化合物到先導化合物的開發時間正在縮短。
- 個人化醫療的擴展正在推動高精度液體處理技術的發展(在歐洲和美國)。
- 後新冠疫情時代永久性分子診斷能力(全球參考實驗室)
- 政府對自動化生物製程的資助(亞太地區)
- 市場限制因素
- 新興市場彈性辦公工作站的初始資本投資成本較高
- 機器人系統編程和維護方面的技能差距
- 高黏度液體交叉污染風險範例
- 大型製藥企業研究實驗室整合傳統LIMS系統面臨的挑戰
- 產業生態系分析
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 依產品類型
- 機器人液體處理工作站
- 移液系統
- 試劑分配器
- 耗材(吸頭、微孔板、試劑)
- 軟體服務
- 按處理能力
- 低通量(每次運行少於100個樣本)
- 中等通量(每次運行 100-1000 個樣本)
- 高通量(每次運行 1000 個樣本或更多)
- 透過平台配置
- 獨立式桌上型系統
- 整合模組化平台
- 透過使用
- 藥物發現及先導化合物最佳化
- 基因組學和蛋白質組學
- 臨床診斷
- 細胞生物學和幹細胞研究
- 合成生物學和生物製程開發
- 其他用途
- 最終用戶
- 製藥和生物技術公司
- 合約研究組織 (CRO) 和合約行銷組織 (CMO)
- 學術研究機構
- 臨床和診斷實驗室
- 法醫科學與環境檢測實驗室
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 韓國
- 印度
- 東南亞
- 其他亞太國家
- 南美洲
- 巴西
- 其他南美國家
- 中東和非洲
- 中東
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 其他中東國家
- 非洲
- 南非
- 其他非洲國家
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Thermo Fisher Scientific Inc.
- Danaher Corp.(Beckman Coulter Life Sciences)
- Tecan Group Ltd.
- Hamilton Company
- PerkinElmer Inc.(Revvity)
- Agilent Technologies Inc.
- Mettler-Toledo International Inc.
- Becton, Dickinson and Company
- Eppendorf AG
- Formulatrix Inc.
- Aurora Biomed Inc.
- Sartorius AG(Biohit)
- Synchron Lab Automation
- Hudson Robotics Inc.
- Analytik Jena AG(Endress+Hauser)
- Opentrons Labworks Inc.
- Biosero Inc.(BICO Group)
- Gilson Inc.
- Lab Services BV
- Andrew Alliance SA(Waters)
- Integra Biosciences AG
- Corning Incorporated
- SPT Labtech Ltd.
- Festo AG and Co. KG
- Starlab International GmbH
第7章 市場機會與未來展望
According to Mordor Intelligence, the automated liquid handlers market size is expected to grow from USD 1.24 billion in 2025 to USD 1.31 billion in 2026 and is forecast to reach USD 1.74 billion by 2031 at 5.81% CAGR over 2026-2031.
This report is Segmented by Product Type (Robotic Liquid-Handling Workstations, and More), Throughput Capability (Low, Medium, and High), Platform Configuration (Stand-Alone Benchtop Systems, and Integrated Modular Platforms), Application (Drug Discovery, Genomics, and More), End User (CROs and CMOs, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Automated Liquid Handlers Market Trends and Insights
Integration with AI-Driven Drug-Discovery Platforms Accelerating Hit-to-Lead Timelines
Automated workstations that pair with machine-learning algorithms now run iterative design-execute-analyse loops without human intervention. Robots equipped with 19F NMR sensors can evaluate 21 reactions in parallel, enabling discovery teams to compress hit-to-lead cycles by 75%. Case studies at AstraZeneca and Weill Cornell show these closed-loop systems improving predictive accuracy for synergistic compounds while capturing granular assay metadata that feeds deep-learning models. The time savings and data richness directly translate into earlier patent filings and a better probability of clinical success, keeping the automated liquid handlers market firmly aligned with pharmaceutical digitalization.
Growing Throughput Requirements in High-Volume Genomic Screening (North America)
US reference labs that scaled up during the pandemic now process thousands of clinical genomes daily. Robotic pipetting solutions like the Biomek Echo One trim sample-prep from two hours to 10 minutes. The underlying economics reward laboratories able to push the cost per sequence below USD 100, which is only feasible when workflows are fully automated. As insurers broaden reimbursement for next-generation sequencing, high-capacity systems become default purchases, reinforcing North American leadership in the automated liquid handlers market.
High Initial CapEx for Flexible Deck Workstations in Emerging Markets
Import duties and multi-layer distribution inflate list prices by up to 116%, pushing a USD 350,000 system above USD 750,000 in parts of Africa. Grants rarely cover training or maintenance, leaving labs with unaffordable service contracts. The result is a widening capability gap that risks excluding emerging markets from global genomics consortia, dampening the automated liquid handlers market in these regions.
Other drivers and restraints analyzed in the detailed report include:
- Adoption of Miniaturized Assay Formats Reducing Reagent Costs
- Expansion of Personalized Medicine Driving High-Accuracy Liquid Handling
- Skill Gap in Programming and Maintenance of Robotic Systems
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Robotic workstations represent the largest slice of the automated liquid handlers market, holding 45.72% market share in 2025, because laboratories still prioritize mechanical precision for repeatable pipetting. Software and services, however, are forecast to grow at 7.59% CAGR as AI modules that schedule runs and predict tip usage deliver immediate cost savings. A growing installed base of robots ensures a recurring stream of consumables, and lubricant-infused tips reduce carry-over in viscous samples.
The product mix is shifting toward platform licences that unlock workflow libraries and cloud analytics. Vendors now bundle subscription dashboards that monitor uptime and flag anomalies, which further elevate software revenue. This pivot transforms competitive dynamics, encouraging ecosystem partnerships and making code libraries a core differentiator in the automated liquid handlers market.
Medium-throughput systems processing 100-1,000 samples per run accounted for 53.12% of the automated liquid handlers market size in 2025. They match typical batch volumes at clinical labs and mid-sized biotechs, offering balanced speed and price. High-throughput units that exceed 1,000 samples log the fastest 6.21% CAGR, thanks to large screening campaigns in drug discovery that surpass 100,000 assays a day.
Unit economics improve sharply once workflows cross 5,000 daily plates, prompting CROs to upgrade ahead of capacity bottlenecks. This trend anchors price premiums for robotic decks with multi-arm configurations and expanded tip racks. It also widens service opportunities in predictive maintenance, adding stability to revenue streams within the automated liquid handlers market.
Complete Report Scope:
- By Product Type
- Robotic Liquid-Handling Workstations
- Pipetting Systems
- Reagent Dispensers
- Consumables (Tips, Plates, Reagents)
- Software and Services
- By Throughput Capability
- Low Throughput (Less than 100 samples/run)
- Medium Throughput (100-1000 samples/run)
- High Throughput (Above 1 000 samples/run)
- By Platform Configuration
- Stand-Alone Benchtop Systems
- Integrated Modular Platforms
- By Application
- Drug Discovery and Lead Optimization
- Genomics and Proteomics
- Clinical Diagnostics
- Cell Biology and Stem-Cell Research
- Synthetic Biology and Bioprocess Development
- Other Applications
- By End User
- Pharmaceutical and Biotechnology Companies
- CROs and CMOs
- Academic and Research Institutes
- Clinical and Diagnostic Laboratories
- Forensic and Environmental Testing Labs
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- South East Asia
- Rest of Asia-Pacific
- South America
- Brazil
- Rest of South America
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America commanded 38.10% share of the automated liquid handlers market in 2025 on the back of permanent molecular diagnostic infrastructure and concentrated pharmaceutical clusters. US-based Thermo Fisher invested USD 2 billion in domestic manufacturing, ensuring short supply chains and compliance support. Canada adds strength in genomics research, while Mexico adopts automation for agrigenomics. The region benefits from venture capital that funds AI-driven lab-tech start-ups, though staffing shortages in robot programming still constrain scale.
Asia-Pacific is the fastest-growing region with a 6.82% CAGR through 2031, boosted by China's 1 trillion yuan robotics initiative and Korea's USD 128 million intelligent-robot program. Japan leverages decades of automation heritage, and Australia uses federal grants to build GMP-grade bioprocessing sites. Localized service centers cut downtime, overcoming historic reliance on imported technicians. Government procurement policies that favor domestic suppliers accelerate installed-base expansion, cementing Asia-Pacific as the primary incremental revenue source for the automated liquid handlers market.
Europe maintains a firm foothold in the automated liquid handlers market through stable pharma pipelines in Germany, the United Kingdom, and France. Regulatory alignment across the EU smooths cross-border tech transfer, while sustainability mandates drive preference for robots with validated CO2 footprints. Southern European labs deploy automation in food and environmental testing, enlarging the addressable demand. Skills gaps are mitigated by apprenticeship programs tied to equipment suppliers, enabling consistent uptime and moderating service costs.
- Thermo Fisher Scientific Inc.
- Danaher Corp. (Beckman Coulter Life Sciences)
- Tecan Group Ltd.
- Hamilton Company
- PerkinElmer Inc. (Revvity)
- Agilent Technologies Inc.
- Mettler-Toledo International Inc.
- Becton, Dickinson and Company
- Eppendorf AG
- Formulatrix Inc.
- Aurora Biomed Inc.
- Sartorius AG (Biohit)
- Synchron Lab Automation
- Hudson Robotics Inc.
- Analytik Jena AG (Endress + Hauser)
- Opentrons Labworks Inc.
- Biosero Inc. (BICO Group)
- Gilson Inc.
- Lab Services B.V.
- Andrew Alliance S.A. (Waters)
- Integra Biosciences AG
- Corning Incorporated
- SPT Labtech Ltd.
- Festo AG and Co. KG
- Starlab International GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Throughput Requirements in High-Volume Genomic Screening (North America)
- 4.2.2 Adoption of Miniaturized Assay Formats Reducing Reagent Costs
- 4.2.3 Integration with AI-Driven Drug-Discovery Platforms Accelerating Hit-to-Lead Timelines
- 4.2.4 Expansion of Personalized Medicine Driving High-Accuracy Liquid Handling (Europe and US)
- 4.2.5 Permanent Molecular-Diagnostic capacity Post-COVID-19 (Global Reference Labs)
- 4.2.6 Government Funding for Automated Bioprocessing (Asia-Pacific)
- 4.3 Market Restraints
- 4.3.1 High Initial CapEx for Flexible Deck Workstations in Emerging Markets
- 4.3.2 Skill Gap in Programming and Maintenance of Robotic Systems
- 4.3.3 Sample Cross-Contamination Risks in High-Viscosity Liquids
- 4.3.4 Legacy LIMS Integration Challenges in Big-Pharma Labs
- 4.4 Industry Ecosystem Analysis
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Robotic Liquid-Handling Workstations
- 5.1.2 Pipetting Systems
- 5.1.3 Reagent Dispensers
- 5.1.4 Consumables (Tips, Plates, Reagents)
- 5.1.5 Software and Services
- 5.2 By Throughput Capability
- 5.2.1 Low Throughput (Less than 100 samples/run)
- 5.2.2 Medium Throughput (100-1000 samples/run)
- 5.2.3 High Throughput (Above 1 000 samples/run)
- 5.3 By Platform Configuration
- 5.3.1 Stand-Alone Benchtop Systems
- 5.3.2 Integrated Modular Platforms
- 5.4 By Application
- 5.4.1 Drug Discovery and Lead Optimization
- 5.4.2 Genomics and Proteomics
- 5.4.3 Clinical Diagnostics
- 5.4.4 Cell Biology and Stem-Cell Research
- 5.4.5 Synthetic Biology and Bioprocess Development
- 5.4.6 Other Applications
- 5.5 By End User
- 5.5.1 Pharmaceutical and Biotechnology Companies
- 5.5.2 CROs and CMOs
- 5.5.3 Academic and Research Institutes
- 5.5.4 Clinical and Diagnostic Laboratories
- 5.5.5 Forensic and Environmental Testing Labs
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 South Korea
- 5.6.3.4 India
- 5.6.3.5 South East Asia
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 South America
- 5.6.4.1 Brazil
- 5.6.4.2 Rest of South America
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 United Arab Emirates
- 5.6.5.1.2 Saudi Arabia
- 5.6.5.1.3 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global-level Overview, Market-level Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)}
- 6.4.1 Thermo Fisher Scientific Inc.
- 6.4.2 Danaher Corp. (Beckman Coulter Life Sciences)
- 6.4.3 Tecan Group Ltd.
- 6.4.4 Hamilton Company
- 6.4.5 PerkinElmer Inc. (Revvity)
- 6.4.6 Agilent Technologies Inc.
- 6.4.7 Mettler-Toledo International Inc.
- 6.4.8 Becton, Dickinson and Company
- 6.4.9 Eppendorf AG
- 6.4.10 Formulatrix Inc.
- 6.4.11 Aurora Biomed Inc.
- 6.4.12 Sartorius AG (Biohit)
- 6.4.13 Synchron Lab Automation
- 6.4.14 Hudson Robotics Inc.
- 6.4.15 Analytik Jena AG (Endress + Hauser)
- 6.4.16 Opentrons Labworks Inc.
- 6.4.17 Biosero Inc. (BICO Group)
- 6.4.18 Gilson Inc.
- 6.4.19 Lab Services B.V.
- 6.4.20 Andrew Alliance S.A. (Waters)
- 6.4.21 Integra Biosciences AG
- 6.4.22 Corning Incorporated
- 6.4.23 SPT Labtech Ltd.
- 6.4.24 Festo AG and Co. KG
- 6.4.25 Starlab International GmbH
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


