


 |
市場調查報告書
商品編碼
2122937
資料倉儲即服務 (DWaaS):市場佔有率分析、產業趨勢與統計資料、成長預測 (2026-2031)Data Warehouse As A Service - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,資料倉儲即服務 (DWaaS) 市場預計到 2026 年價值 74.2 億美元,高於 2025 年的 60.9 億美元,預計到 2031 年將達到 199.4 億美元。
預計 2026 年至 2031 年的複合年成長率將達到 21.85%。
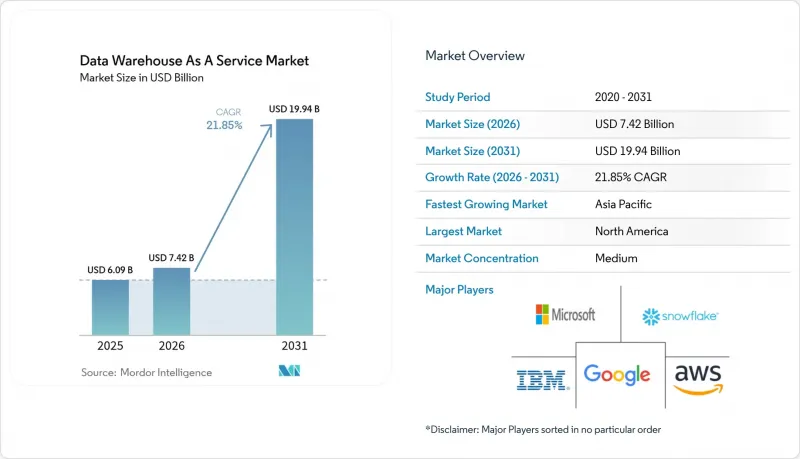
本報告按部署模式(公共雲端、私有雲端、混合/多重雲端)、最終用戶企業規模(大型企業、中小企業)、最終用戶行業(銀行、金融服務和保險、政府/公共部門、其他)、服務類型(企業資料倉儲即服務 (DWaaS)、營運資料儲存即服務 (ODSaaS)、其他)和地區進行細分。市場預測以美元 (USD) 為單位。
全球資料倉儲即服務 (DWaaS) 市場趨勢與洞察
雲端遷移和即時分析的快速成長
企業正從週期性的批量報告轉向串流架構,以亞秒級的增量將資料傳輸到儀表板和預測模型。 ABB 已將來自 40 個不同 ERP 系統的資料整合到單一 Snowflake 實例中,透過即時了解生產狀態,節省了數百萬美元的成本。邊緣閘道器現在可以在生產線附近過濾時效性強的遙測數據,而雲端資料倉儲則可以執行複雜的連接操作和歷史趨勢分析,而不會出現容量瓶頸。這些低延遲管道支援自主設備最佳化、動態定價和即時詐欺預防。隨著互聯設備的日益普及,即時分析將繼續成為最重要的投資重點,從而推動對彈性 DWaaS 容量的需求,這種容量可以根據資料擷取速率而非固定節點進行擴展。
人工智慧/機器主導的資料倉儲需求
最新的資料倉儲層級融合了結構化表和非結構化文件,從而能夠在儲存層內進行模型訓練。 Snowflake 與 NVIDIA 的合作將專用 GPU 整合到運算叢集集中,確保即使在加速推理期間,資料也始終處於安全邊界之內。 Databricks 整合了一種「湖倉式」儲存模型,使資料科學家能夠使用與驅動儀表板完全相同的 SQL 端點,從Petabyte級日誌中建立特徵。利用大規模語言模型的自然語言查詢助手,使業務用戶能夠更便捷地存取分析功能,從而加速企業內部的採用,並推動整個 DWaaS 市場運算資源的消耗成長。
網路安全和隱私風險
歐洲《一般資料保護規則》(GDPR) 和亞洲新推出的在地化相關法規限制了跨境資料傳輸,使跨國公司的雲端策略變得更加複雜。將敏感資產集中儲存在第三方雲端中,使其更容易成為網路威脅的目標,迫使企業實施全球加密、零信任存取和持續的安全態勢監控。共享責任安全模式本身也可能模糊責任界限,尤其是在缺乏專職雲端安全人員的團隊中,導致採購週期延長和部署延遲。
細分市場分析
到2025年,公共雲端平台將佔據資料倉儲即服務(DWaaS)市場64.80%的佔有率,因為企業優先考慮的是承包的可擴展性和全球可用性。 AWS透過深度服務整合佔據了約34%的全球收入,而微軟Azure則受益於Office 365成熟的部署基礎,這簡化了採購流程。在主權法規禁止外部託管的地區,私有雲端的採用仍在繼續,但高昂的營運成本阻礙了其成長。
隨著企業將分析能力分散到多個雲端服務供應商,以避免供應商鎖定、利用區域成本差異,並在自主平台上優先處理敏感資料集,預計到 2031 年,混合雲和多重雲端的採用率將以 23.90% 的複合年成長率成長。 Google Cloud 的 BigQuery Omni 支援跨雲端查詢執行,無需實體資料移動,充分展現了互通性功能如何降低出站費用和延遲。 Snowflake 的開放式 Polaris Catalog 透過標準化 AWS、Azure 和 Google Cloud 之間的元資料,進一步簡化了遷移過程。
由於大型組織機構複雜的管治需求和多功能分析環境,預計到2025年,它們將佔據資料倉儲即服務(DWaaS)市場61.55%的佔有率。這些組織機構實施了高階的安全防護,支援數千個同時上線用戶,並將其資料倉儲與傳統的ERP、CRM和風險管理引擎整合。
相較之下,中小企業預計將成為營收成長的主要驅動力,並有望在2031年之前以25.60%的複合年成長率實現成長,這得益於無伺服器引擎消除了容量規劃的障礙。低程式碼資料擷取連接器和自然語言查詢介面使業務分析師無需專門的資料科學團隊即可啟動預測模型,從而縮小了與大型企業的能力差距。學術研究表明,中小企業分析專案成功的關鍵因素並非硬體預算,而是文化轉變。
區域分析
預計到2025年,北美將佔全球收入的38.90%。這得益於北美豐富的資料中心容量、有利的雲端採購政策以及在科技、金融和醫療保健產業深厚的技能基礎。超大規模資料中心業者正在不斷部署區域特定的AI加速器和主權雲端區域,以滿足對高階分析服務的需求。聯邦和州政府的舉措,例如緬因州的雲端遷移,進一步凸顯了雲端倉庫在公共部門工作負載方面的有效性。
亞太地區是成長最快的地區,預計到2031年複合年成長率將達到24.10%,這得益於大規模超大規模基礎設施的擴張和各國政府數位經濟藍圖的推進。新加坡政府科技局(GovTech)等公共部門的最佳實踐表明,監管政策的明確和政府主導的雲端運算培訓可以縮短企業引進週期。
在歐洲,高分析需求與嚴格的主權相關法律之間正尋求平衡。供應商正透過提供歐盟專用區域、保密計算飛地和主權元元資料服務來應對這項挑戰。跨國金融機構正在採用分散式資料網格架構,以在遵守當地資料居住法規的同時,維持跨境風險分析能力。在南美洲、中東和非洲,隨著電子商務和智慧城市計畫的擴展,雖然商機雖小但成長迅速。然而,基礎設施差異和宏觀經濟波動在短期內減緩了這些技術的應用速度。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 市場定義與研究假設
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 雲端遷移和即時分析的快速成長
- 人工智慧/機器主導的資料倉儲需求
- 銀行、金融服務和保險業的「數位化優先」藍圖
- 向基於消費的定價模式過渡
- 邊緣到雲端的低延遲資料倉儲
- 關注綠色住宅碳彙報
- 市場限制因素
- 網路安全和隱私風險
- 雲端成本上漲難以預測
- 對供應商鎖定問題的擔憂
- 缺乏財務營運/數據可觀測性技能
- 價值鏈分析
- 重要法規結構的評估
- 對關鍵相關人員的影響評估
- 技術展望
- 波特五力分析
- 宏觀經濟因素的影響
第5章 市場規模與成長預測
- 按部署模式
- 公共雲端
- 私有雲端
- 混合多重雲端
- 按最終用戶公司規模分類
- 大公司
- 小型企業
- 按最終用戶行業分類
- BFSI
- 政府/公共部門
- 醫療保健和生命科學
- 零售與電子商務
- 通訊/IT
- 媒體與娛樂
- 製造業
- 按服務類型
- 企業資料倉儲即服務 (DWaaS)
- ODSaaS(Operational Data-Store-as-a-Service)
- DLaaS(Data Lakehouse-as-a-Service)
- 分析加速服務
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 澳洲和紐西蘭
- 其他亞太國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 埃及
- 其他非洲地區
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Amazon Web Services Inc.
- Microsoft Corporation
- Google LLC
- Snowflake Inc.
- IBM Corporation
- Oracle Corporation
- SAP SE
- Teradata Corp.
- Cloudera Inc.
- Databricks Inc.
- Micro Focus International plc
- Yellowbrick Data
- ClickHouse Inc.
- Dremio Corporation
- Alibaba Cloud
- Huawei Cloud
- Firebolt Analytics Ltd.
- Vertica(Micro Focus)
- Exasol AG
- Actian Corp.
第7章 市場機會與未來趨勢
- 對未開發市場和未滿足需求的評估
According to Mordor Intelligence, data warehouse as a service market size in 2026 is estimated at USD 7.42 billion, growing from 2025 value of USD 6.09 billion with 2031 projections showing USD 19.94 billion, growing at 21.85% CAGR over 2026-2031.
This report is Segmented by Deployment Model (Public Cloud, Private Cloud, Hybrid/Multi-cloud), End-User Enterprise Size (Large Enterprises, Small and Medium Enterprises), End-User Industry (BFSI, Government and Public Sector, and More), Service Type (Enterprise DWaaS, Operational Data-Store As A Service, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Data Warehouse As A Service Market Trends and Insights
Cloud Migration and Real-Time Analytics Boom
Enterprises are shifting from periodic batch reporting to streaming architectures that feed sub-second dashboards and predictive models. ABB consolidated data from 40 disparate ERP systems into a single Snowflake instance and unlocked multimillion-dollar savings through real-time production visibility . Edge gateways now filter time-sensitive telemetry close to manufacturing lines, while cloud data warehouses execute complex joins and historical trend analyses without capacity bottlenecks. These low-latency pipelines support autonomous-equipment optimization, dynamic pricing, and instantaneous fraud controls. As more connected devices proliferate, real-time analytics will remain a top spending priority, reinforcing demand for elastic DWaaS capacity that scales on ingestion rates rather than fixed nodes.
AI/ML-Driven Warehousing Demand
Modern data-warehouse layers blend structured tables with unstructured files, enabling model training inside the storage tier. Snowflake's collaboration with NVIDIA embeds specialized GPUs alongside compute clusters so data never leaves the security perimeter during inference acceleration . Databricks integrates lakehouse storage formats that let data scientists build features over petabyte-scale logs using the same SQL endpoints powering dashboards. Natural-language query assistants driven by large language models democratize analytics access for business users, fueling broader organizational adoption and increasing overall compute consumption across the data warehouse as a service market.
Cyber-Security and Privacy Risks
General Data Protection Regulation requirements in Europe and new localization statutes in Asia restrict cross-border data movement, complicating multinational cloud strategies. Consolidating sensitive assets inside third-party clouds heightens the appeal for threat actors, forcing enterprises to deploy pervasive encryption, zero-trust access and continuous posture monitoring. The shared-responsibility security model itself can blur accountability lines, especially for teams lacking dedicated cloud-security talent, thereby extending procurement cycles and slowing adoption.
Other drivers and restraints analyzed in the detailed report include:
- BFSI Digital-First Road-Maps
- Shift to Consumption-Based Pricing
- Unpredictable Cloud Cost Sprawl
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Public-cloud platforms held 64.80% of the data warehouse as a service market size in 2025 as enterprises prioritized turnkey scalability and global availability. AWS captured roughly 34% of worldwide revenue thanks to deep service integration, while Microsoft Azure benefited from established Office 365 footprints that eased procurement. Private-cloud instances persist where sovereignty mandates preclude external hosting, but higher operational overhead tempers growth.
Hybrid and multi-cloud deployments are projected to record a 23.90% CAGR through 2031 as firms distribute analytics across providers to avoid lock-in, exploit regional cost differentials and place sensitive datasets on preferred sovereign platforms. Google Cloud's BigQuery Omni allows cross-cloud querying without physical data moves, showing how interoperability features reduce egress fees and latency penalties . Snowflake's open Polaris Catalog further eases migration by standardizing metadata across AWS, Azure and Google Cloud.
Large organizations controlled 61.55% of the 2025 data warehouse as a service market share due to complex governance needs and multi-department analytics estates. They deploy advanced security layers, support thousands of concurrent users and integrate warehouses with legacy ERP, CRM and risk engines.
In contrast, SMEs will drive the highest incremental revenue, expanding at a 25.60% CAGR through 2031 as serverless engines remove capacity-planning hurdles. Low-code ingestion connectors and natural-language query interfaces allow business analysts to launch predictive models without dedicated data-science teams, narrowing capability gaps versus larger peers. Academic studies highlight cultural change as the primary success factor for SME analytics programs, not hardware budgets.
Complete Report Scope:
- By Deployment Model
- Public Cloud
- Private Cloud
- Hybrid / Multi-cloud
- By End-user Enterprise Size
- Large Enterprises
- Small and Medium Enterprises
- By End-user Industry
- BFSI
- Government and Public Sector
- Healthcare and Life Sciences
- Retail and E-commerce
- Telecom and IT
- Media and Entertainment
- Manufacturing
- By Service Type
- Enterprise DWaaS
- Operational Data-store as a Service
- Data Lakehouse as a Service
- Analytics Acceleration Services
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America accounted for 38.90% of global revenue in 2025, buoyed by abundant data-center capacity, favorable cloud procurement policies and a deep skills base across technology, finance and healthcare verticals. Hyperscalers continuously launch region-specific AI accelerators and sovereign-cloud zones, sustaining demand for premium analytics tiers. Federal and state agencies, exemplified by the State of Maine's cloud migration, further validate cloud warehouses for public-sector workloads .
Asia-Pacific is the fastest-growing region with a 24.10% CAGR through 2031, supported by massive hyperscale build-outs and government digital-economy roadmaps. Public-sector exemplars such as Singapore's GovTech highlight how regulatory clarity and state-sponsored cloud training shorten enterprise adoption cycles.
Europe balances high analytics demand with stringent sovereignty legislation. Vendors respond by launching EU-only regions, confidential computing enclaves and sovereign-metadata services. Multinational financial institutions implement distributed data-mesh architectures to comply with local residency rules while preserving cross-border risk analytics. South America plus the Middle East & Africa exhibit growing, albeit smaller, opportunity pools linked to e-commerce expansion and smart-city initiatives; however, infrastructure gaps and macro-economic volatility moderate near-term uptake.
- Amazon Web Services Inc.
- Microsoft Corporation
- Google LLC
- Snowflake Inc.
- IBM Corporation
- Oracle Corporation
- SAP SE
- Teradata Corp.
- Cloudera Inc.
- Databricks Inc.
- Micro Focus International plc
- Yellowbrick Data
- ClickHouse Inc.
- Dremio Corporation
- Alibaba Cloud
- Huawei Cloud
- Firebolt Analytics Ltd.
- Vertica (Micro Focus)
- Exasol AG
- Actian Corp.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Market Definition and Study Assumptions
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Cloud migration and real-time analytics boom
- 4.2.2 AI/ML-driven warehousing demand
- 4.2.3 BFSI digital-first road-maps
- 4.2.4 Shift to consumption-based pricing
- 4.2.5 Edge-to-cloud low-latency warehousing
- 4.2.6 Green warehousing and carbon reporting focus
- 4.3 Market Restraints
- 4.3.1 Cyber-security and privacy risks
- 4.3.2 Unpredictable cloud cost sprawl
- 4.3.3 Vendor lock-in concerns
- 4.3.4 Shortage of FinOps / data-observability skills
- 4.4 Value Chain Analysis
- 4.5 Evaluation of Critical Regulatory Framework
- 4.6 Impact Assessment of Key Stakeholders
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Consumers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
- 4.9 Impact of Macro-economic Factors
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Deployment Model
- 5.1.1 Public Cloud
- 5.1.2 Private Cloud
- 5.1.3 Hybrid / Multi-cloud
- 5.2 By End-user Enterprise Size
- 5.2.1 Large Enterprises
- 5.2.2 Small and Medium Enterprises
- 5.3 By End-user Industry
- 5.3.1 BFSI
- 5.3.2 Government and Public Sector
- 5.3.3 Healthcare and Life Sciences
- 5.3.4 Retail and E-commerce
- 5.3.5 Telecom and IT
- 5.3.6 Media and Entertainment
- 5.3.7 Manufacturing
- 5.4 By Service Type
- 5.4.1 Enterprise DWaaS
- 5.4.2 Operational Data-store as a Service
- 5.4.3 Data Lakehouse as a Service
- 5.4.4 Analytics Acceleration Services
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia and New Zealand
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Egypt
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Amazon Web Services Inc.
- 6.4.2 Microsoft Corporation
- 6.4.3 Google LLC
- 6.4.4 Snowflake Inc.
- 6.4.5 IBM Corporation
- 6.4.6 Oracle Corporation
- 6.4.7 SAP SE
- 6.4.8 Teradata Corp.
- 6.4.9 Cloudera Inc.
- 6.4.10 Databricks Inc.
- 6.4.11 Micro Focus International plc
- 6.4.12 Yellowbrick Data
- 6.4.13 ClickHouse Inc.
- 6.4.14 Dremio Corporation
- 6.4.15 Alibaba Cloud
- 6.4.16 Huawei Cloud
- 6.4.17 Firebolt Analytics Ltd.
- 6.4.18 Vertica (Micro Focus)
- 6.4.19 Exasol AG
- 6.4.20 Actian Corp.
7 MARKET OPPORTUNITIES AND FUTURE TRENDS
- 7.1 White-space and Unmet-need Assessment

 全球資料倉儲即服務 (DWaaS) 市場規模、佔有率、趨勢和成長分析報告(2026-2034 年)
 資料倉儲即服務 (DWaaS) 市場:市場規模、佔有率和趨勢分析(按部署方式、使用情況、公司規模、應用、最終用途和地區分類),細分市場預測(2026-2033 年)
 2026年全球資料倉儲即服務(DWaaS)市場報告全球資料倉儲即服務(DWaaS)市場:市場規模、佔有率、成長、依類型和應用劃分的行業分析、區域洞察和預測(2026–2034)
 資料倉儲即服務 (DWaaS) 市場規模、佔有率和成長分析(按部署模式、應用程式、組織規模、最終用戶產業和地區分類)—2026-2033 年產業預測
 資料倉儲即服務(DWaaS)市場規模、佔有率、趨勢及產業分析報告:依用途、部署、應用、垂直產業、地區,並預測2025-2034年市場規模