


 |
市場調查報告書
商品編碼
2122887
縫紉機:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Sewing Machines - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
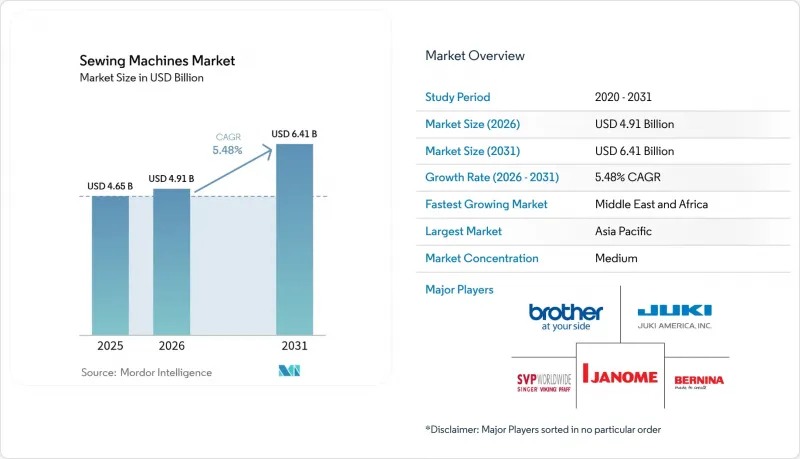
預計到 2026 年,縫紉機市場規模將達到 49.1 億美元,高於 2025 年的 46.5 億美元,預計到 2031 年將達到 64.1 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 5.48%。
本報告按機器類型(手動、電動等)、應用領域(服裝、非服裝紡織品等)、最終用戶(住宅、工業)、分銷管道(B2C/零售、B2B/廠商直銷)和地區(北美、南美等)進行分類。市場預測以美元計價。
全球縫紉機市場趨勢及洞察
亞太地區服裝製造業的快速擴張
在政府扶持措施和出口導向策略的推動下,亞洲服裝生產成長持續高於其他地區。光是印度就設定了2030年紡織品出口額達到3,500億美元的目標,這推動了高產能縫紉機生產線的大量採購。針對功能性紡織品的生產補貼計畫縮短了無需人工操作且可處理各種布料重量的自動化縫紉機的投資回收期。傳統低成本生產基地的薪資上漲促使製造商轉向採用伺服馬達和可程式設計縫紉模式的機型,以抵消人事費用。越南和孟加拉工廠的集中化簡化了售後服務物流,並鼓勵供應商建立區域服務中心。隨著訂單從基本款T卹轉向高附加價值的休閒和正裝,對能夠處理複雜縫紉結構和進行數位化壓板調節的縫紉機的需求日益成長。
成熟經濟體中DIY與手工藝文化的復興
Z世代消費者將居家縫紉視為打造專屬時尚、減少紡織品廢棄物的一種方式,社群媒體上的教學推動了這一趨勢,並帶動了特定縫紉機的銷售。零售商現在提供精心挑選的入門套裝,將入門級縫紉機與可下載的紙樣相結合,降低了入門門檻。這項嗜好在疫情期間迅速走紅,即使在封鎖解除後,它仍然成為人們主要的減壓方式,即便其他家居裝修品類逐漸恢復正常,零售依然居高不下。適合小戶型公寓的緊湊型設計和類似智慧型手機的觸控螢幕深受數位原住民的喜愛,迫使品牌優先考慮直覺的用戶體驗(UX),而非機械結構的複雜性。 Etsy等手工製品轉售平台的興起進一步推動了這項愛好的商業化,並鼓勵用戶在超越基本功能限制後升級設備。
工業機械的大量初始投資
雖然供應商提供融資方案,但這些方案僅涵蓋硬體,不包括培訓和維護。銀行通常要求提供抵押品,而小規模工坊無力承擔,導致現代化改造週期緩慢,生產基地仍在繼續使用已有十年歷史的鎖式縫紉機。隨著品牌對縫紉強度和數位化可追溯性的要求日益嚴格,延遲投資會降低競爭力。 JUKI 於 2024 年推出的租賃計劃在越南率先採用,但在其他地區仍相對較新。原因之一是企業擔心長期依賴專有軟體生態系統。
細分市場分析
預計到2025年,電動縫紉機將佔總銷售量的64.35%,凸顯其在工廠和家庭中的多功能性。許多工業買家將這一領域視為向全面自動化過渡的階段,透過加裝伺服驅動器和半自動切線器來延長縫紉機的使用壽命。同時,隨著工廠追求穩定的縫紉品質和減少返工,預計到2031年,自動化縫紉機的年複合成長率將達到6.62%。自動化系統的市場規模正在擴大,反映出運動服裝和功能性紡織品製造商的需求不斷成長。另一方面,在電力供應不穩定的地區,手動縫紉機仍然在使用,這在重視手感操作的工匠群體中建立了一個穩固的利基市場。
由於電動縫紉機擁有廣泛的替換零件和較短的培訓週期(這得益於操作人員的廣泛熟悉),因此電動縫紉機市場持續佔據主導地位。勝家(Singer)的M3330機型配備了Wi-Fi功能,展示瞭如何在不涉及全數控(CNC)複雜性的前提下,將智慧功能融入傳統縫紉機產品線。液壓驅動的絎縫機則屬於「其他」類別,它們在床墊製造領域取得了成功,並已將業務拓展至土耳其和波蘭。電動縫紉機和入門級自動化系統之間的價格差距已縮小至18%,這是財務長開始批准升級的閾值。
2025年,服飾業仍將維持57.85%的銷售佔有率,佔據主導地位,這主要得益於快時尚巨頭和製服供應商的大量訂單。運動服飾產業發展勢頭強勁,這主要得益於對用於縫製拉伸布料的差動送布包縫機的需求,目前原始設備製造商(OEM)已開始銷售配套的專用壓腳。家用紡織品(包括窗簾和靠墊套)是成長最快的細分市場,複合年成長率(CAGR)達6.69%,主要得益於住宅對個人化室內裝潢的日益重視。預計2024年至2025年,家用紡織品應用縫紉機的市佔率將成長120個基點,顯示居家客製化趨勢持續高漲。汽車內裝、一次性醫療產品和工業過濾器構成了非服裝業,這些行業都需要重型縫紉針和加固型工作台。
消費者對永續室內裝潢日益成長的偏好推動了對優質紗線的需求成長。這使像American & Efird這樣的環保染色紗線供應商受益。汽車座椅製造商將每秒40針的加固縫紉功能作為規格要求,為能夠整合高扭矩伺服馬達的供應商創造了商機。在醫療個人防護工具(PPE)領域,儘管超音波縫紉的替代技術正在湧現,但監管審計仍然傾向於關鍵罩衣的縫合連接。印度都市區可支配收入的成長擴大了僅用於刺繡的縫紉機市場,使用戶能夠透過家庭工作坊獲得收入。這種多元化有助於緩解服裝製造業的週期性低迷,即使在服裝市場低迷時期也能穩定OEM廠商的收益。
區域分析
預計到2025年,亞太地區將佔全球銷售額的50%至60%,這反映了該地區在從紡織到時尚的價值鏈中無可比擬的規模,以及中產階級消費的不斷成長。在印度,正在實施的生產連結獎勵計畫(PLI)可報銷高達15%的資本投資,這正推動紡紗廠的快速現代化。中國OEM製造商正擴大向全球品牌供應伺服組件和人機介面,從而縮短功能更新的前置作業時間。為了因應越南服裝出口的成長,供應商正在胡志明市建造服務倉庫,以減少因更換備件而造成的停機時間。此外,該地區消費者對工藝愛好的熱情日益高漲,雅加達和曼谷的零售連鎖店入門級家用電器的銷售額均實現了兩位數的成長。
中東和非洲地區正經歷最快的成長,預計複合年成長率將達到6.89%。這主要得益於將工業園區與關稅豁免結合的基礎設施走廊,例如埃及的蘇伊士運河經濟特區。埃塞俄比亞的哈瓦薩工業園區目前已入駐25家服裝製造商,根據海關數據顯示,這些公司將在2024年進口超過5,000台可程式鎖式縫紉機。波灣合作理事會(GCC)成員國正在其「2030願景」計畫下鼓勵對紡織業的投資,其中沙烏地阿拉伯已撥款5億美元用於建造綜合工廠。非洲消費市場也日趨成熟,中價位的可攜式縫紉機目前已在奈及利亞的電商平台上銷售,並在假日期間售罄。挑戰在於人力資源開發,原始設備製造商(OEM)正與內羅畢和阿克拉的職業培訓機構合作,為操作人員提供基礎維護的認證。
在北美,本土服裝生產正在復甦,這主要得益於消費者對本地服飾的重視以及品牌面臨的跨太平洋運輸不確定性。耐吉等品牌正在奧勒岡州試行自動化生產線,採用能縫製多種布料的數控縫紉機頭。在北卡羅來納州和南卡羅來納州,州政府津貼支持現有工廠購買設備,升級為智慧工廠。加拿大服裝中小企業正在採用線上配置器,允許終端用戶設計定製圖案,這間接增加了對能夠處理數位輸入檔案的機器的需求。隨著美國買家為了適應快節奏的零售模式而轉向本地採購,墨西哥也從中受益。
在歐洲,成熟的工業基礎與前沿的永續發展政策相融合,重新定義了設備規格。將於2027年實施的生態設計指令要求對機器層面的能耗進行精確測量,迫使原始設備製造商(OEM)轉向高效能伺服馬達。德國繼續保持其在汽車和航太技術紡織品領域的主導,推動了對高耐用性、可程式設計的打結機的需求。義大利高階時尚品牌在自動化設備之外,還使用專業的手工刺繡機,以保持「義大利製造」的純正品質。由於物流不穩定,羅馬尼亞和保加利亞等東歐國家的工廠正在獲得從亞洲轉移過來的訂單,這需要它們迅速擴充機械設備。
在南美洲,巴西聖卡塔琳娜州的服裝產業叢集正穩步發展,透過現代化改造和實施節能措施,例如為應對不斷上漲的電費而改用伺服馬達。烏拉圭和巴拉圭正吸引中國投資者建造一體化的「棉花到服裝」生產基地,以實現設備需求的本地化。同時,在智利,電子商務的興起帶動了愛好者對小型家用縫紉機的需求成長,這些縫紉機專為小戶型公寓設計。外匯波動仍然是一個主要阻力,購買進口縫紉機的決策往往會被推遲到外匯穩定後再做決定。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 亞太地區服裝製造業的快速擴張
- 成熟經濟體中DIY與手工藝文化的復興
- 物聯網和數控縫紉機技術的進步
- 推廣工業自動化以提高生產力
- 近岸外包正在推動對小規模工業專案需求的成長。
- 一場由永續發展驅動的「維修與再利用」消費運動。
- 市場限制因素
- 工業機械領域的高資本投入
- 低價再生產品的普及
- 電子產業供應鏈(MCU、伺服)的瓶頸
- 熟練操作人員短缺,無法處理先進型號
- 產業價值鏈分析
- 波特五力分析
- 洞察最新市場趨勢與創新
- 洞察近期市場趨勢(新產品發布、策略性舉措、投資、合作、合資、業務擴張、併購等)
第5章 市場規模與成長預測
- 按機器類型
- 手動的
- 電的
- 自動化
- 其他機器類型
- 透過使用
- 服裝與時尚
- 服裝以外的紡織品(汽車、室內裝潢)
- 鞋類和皮革製品
- 家用紡織品和工藝品
- 其他用途
- 最終用戶
- 住宅
- 產業
- 透過分銷管道
- B2C/零售
- 多品牌商店
- 品牌經銷店
- 線上
- 其他分銷管道
- B2B/廠商直銷
- B2C/零售
- 按地區
- 北美洲
- 加拿大
- 美國
- 墨西哥
- 南美洲
- 巴西
- 秘魯
- 智利
- 阿根廷
- 其他南美國家
- 歐洲
- 英國
- 德國
- 法國
- 西班牙
- 義大利
- 比荷盧經濟聯盟(比利時、荷蘭、盧森堡)
- 北歐國家(丹麥、芬蘭、冰島、挪威、瑞典)
- 其他歐洲國家
- 亞太地區
- 印度
- 中國
- 日本
- 澳洲
- 韓國
- 東南亞(新加坡、馬來西亞、泰國、印尼、越南、菲律賓)
- 其他亞太國家
- 中東和非洲
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 南非
- 奈及利亞
- 其他中東和非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Brother Industries, Ltd.
- JUKI Corporation
- SVP Worldwide(Singer(R), Husqvarna Viking(R), Pfaff(R))
- Janome Sewing Machine Co., Ltd.
- Bernina International AG
- Mitsubishi Electric Corp.(Industrial Sewing Machinery)
- Jack Sewing Machine Co., Ltd.
- Pegasus Sewing Machine Mfg. Co., Ltd.
- Toyota Industries Corp.(TACHINO)
- Baby Lock/Tacony Corporation
- Zoje Sewing Machine Co., Ltd.
- Feiyue Group Co., Ltd.
- Union Special LLC
- Rimoldi & CF
- SunStar Co., Ltd.
- Yamato Sewing Machine Mfg. Co., Ltd.
- Typical Sewing Machine Co., Ltd.
- Seiko Sewing Machine Co., Ltd.
- Merrow Sewing Machine Company
第7章 市場機會與未來展望
According to Mordor Intelligence, sewing machine market size in 2026 is estimated at USD 4.91 billion, growing from 2025 value of USD 4.65 billion with 2031 projections showing USD 6.41 billion, growing at 5.48% CAGR over 2026-2031.
This report is Segmented by Machine Type (Manual, Electric, and More), by Application (Apparel, Non-Apparel Textiles, and More), by End-User (Residential and Industrial), by Distribution Channel (B2C/Retail and B2B/Directly From the Manufacturers), and by Geography (North America, South America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Sewing Machines Market Trends and Insights
Rapid Apparel-Manufacturing Expansion in Asia-Pacific
Asia continues to outpace every other region in apparel output, fueled by public incentives and export-oriented strategies. India alone targets USD 350 billion in textile exports by 2030, stimulating bulk procurement of high-throughput sewing lines . Production-linked schemes covering technical textiles lower the payback period on automated machines that handle multiple fabric weights without manual intervention. Growing wages in legacy low-cost centers push manufacturers toward units with servo motors and programmable stitch patterns that offset labor costs. Factory clustering in Vietnam and Bangladesh simplifies after-sales logistics, encouraging suppliers to embed regional service hubs. As orders shift from basic tees to higher-value athleisure and formalwear, demand tilts toward machines capable of complex seam constructions and digital platen adjustments.
DIY & Craft Culture Revival in Mature Economies
Gen Z consumers view home sewing as a route to personalized fashion and lower textile waste, and social media tutorials convert that interest into measurable hardware sales. Retailers now curate starter bundles that pair entry-level machines with downloadable patterns, easing the learning curve. Pandemic-era hobby adoption has persisted post-lockdown as a stress-relief habit, keeping retail sell-through high even as other home-improvement categories normalize. Compact form factors that fit small apartments and smartphone-like touchscreens resonate with digital natives, forcing brands to prioritize intuitive UX over mechanical complexity. The rising tide of reseller platforms for handmade items, such as Etsy, further monetizes the hobby, reinforcing equipment upgrades once users outgrow basic functions.
High Capital Outlay for Industrial Machines
Vendor financing options exist yet cover only the hardware, leaving training and maintenance outside loan packages. Banks often require collateral that small workshops lack, delaying modernization cycles and leaving production stuck with 10-year-old lockstitch units. Deferred investment saps competitiveness when brands demand tight tolerances on seam strength and digital traceability. Leasing programs introduced by JUKI in 2024 showed early adoption in Vietnam but remain a novelty elsewhere, partly because operators fear long-term commitment to proprietary software ecosystems.
Other drivers and restraints analyzed in the detailed report include:
- Advancements in IoT-Enabled and CNC Sewing Machines
- Industrial Automation Push for Productivity
- Shortage of Skilled Operators
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Electric models accounted for 64.35% of revenue in 2025, underscoring their versatility for factories and households alike. Many industrial buyers regard the segment as an interim step toward full automation, adding servo drives and semi-automatic thread cutters to stretch machine life cycles. Automated units, meanwhile, are slated to expand at 6.62% CAGR through 2031 as factories chase consistent stitch quality and lower rework. The sewing machine market size for automated systems is growing, reflecting rising demand from sportswear and technical-textile plants. Manual machines linger in regions with unstable electricity grids, carving out a defensible niche among artisans who prize tactile control.
Continued dominance of the electric segment derives from abundant spare parts and universal familiarity among operators, decreasing training periods. Singer's Wi-Fi-ready M3330 illustrates how traditional categories absorb smart features without jumping to full CNC complexity. Hydraulically actuated quilting machines populate the "other" category and find success in mattress manufacturing, expanding geographic penetration into Turkey and Poland. Price gaps between electric and entry-level automated systems have narrowed to 18%, a threshold at which CFOs start green-lighting upgrades.
Apparel retained a commanding 57.85% slice of 2025 revenue due to vast order volumes from fast-fashion giants and uniform suppliers. Sportswear gains traction as stretch fabrics require differential-feed overlockers, prompting OEMs to bundle specialized presser feet. Home textiles, including curtains and cushion covers, represent the fastest-growing niche with a 6.69% CAGR as homeowners invest in personalized decor. The sewing machine market share for home-textile applications rose 120 basis points between 2024 and 2025, signaling a durable shift toward at-home customization. Automotive upholstery, medical disposables, and industrial filters round out the non-apparel group, each demanding heavy-duty needles and reinforced work tables.
Consumer preference for sustainable interiors boosts premium thread demand, benefiting subsidiaries like American & Efird that supply eco-dyed yarns. Car seat makers specify bar-tacking capabilities at 40 stitches per second, creating opportunities for providers that can integrate high-torque servo motors. In medical PPE, ultrasonic sewing alternatives compete, yet regulatory audits still favor stitched seams for critical gowns. Rising disposable income in urban India grows the market for embroidery-only machines that let users monetize home businesses. This diversification smooths cyclical dips in garment manufacturing, cushioning OEM revenue during apparel slowdowns.
Complete Report Scope:
- By Machine Type
- Manual
- Electric
- Automated
- Other Machine Types
- By Application
- Apparel & Fashion
- Non-apparel Textiles (Automotive, Upholstery)
- Footwear & Leather Goods
- Home Textiles & Crafts
- Other Applications
- By End User
- Residential
- Industrial
- By Distribution Channel
- B2C/Retail
- Multi-brand Stores
- Exclusive Brand Outlets
- Online
- Other Distribution Channels
- B2B/Directly from the Manufacturers
- B2C/Retail
- By Geography
- North America
- Canada
- United States
- Mexico
- South America
- Brazil
- Peru
- Chile
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- BENELUX (Belgium, Netherlands, Luxembourg)
- NORDICS (Denmark, Finland, Iceland, Norway, Sweden)
- Rest of Europe
- Asia-Pacific
- India
- China
- Japan
- Australia
- South Korea
- South-East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, Philippines)
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Nigeria
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific's 50.60% revenue leadership in 2025 reflects its unmatched scale in fiber-to-fashion value chains and ascending middle-class consumption. India continues to roll out Production Linked Incentives that reimburse up to 15% of capital investment, prompting mills to modernize quickly . Chinese OEMs increasingly supply servo components and human-machine interfaces to global brands, shortening lead times for feature updates. Vietnam's apparel export growth encourages suppliers to build service warehouses in Ho Chi Minh City, reducing downtime for spare-part replacements. The region also witnesses swelling consumer enthusiasm for craft hobbies, as retail chains in Jakarta and Bangkok report double-digit sales lift for entry-level home units.
The Middle East and Africa grows the fastest, projected at 6.89% CAGR, supported by infrastructure corridors like Egypt's Suez Canal Economic Zone that bundle industrial parks with duty exemptions. Ethiopia's Hawassa Industrial Park already houses 25 apparel manufacturers that collectively imported more than 5,000 programmable lockstitch machines in 2024 according to customs data. Gulf Cooperation Council states encourage textile investments under Vision-2030 plans, with Saudi Arabia earmarking USD 500 million loans for integrated mills. African consumer markets also mature; Nigeria's e-commerce platforms now list mid-range portable models that sell out during festival seasons. The challenge lies in training; OEMs partner with vocational institutes in Nairobi and Accra to certify operators on basic maintenance.
North America experiences a revival in domestic making, powered by consumers who value locally produced garments and by brands facing unpredictable trans-Pacific freight. Brands such as Nike pilot automated lines in Oregon that rely on CNC sewing heads capable of multi-material stitching. State-level grants in North Carolina and South Carolina subsidize equipment purchases for legacy mills upgrading to smart factories. Canada's apparel SMEs embrace online configurators that allow end-users to design custom patterns, indirectly boosting demand for machines that accept digital input files. Mexico secures spill-over benefits as US buyers near-source to comply with quick-response retail models.
Europe blends mature industrial bases with avant-garde sustainability policies that redefine equipment specifications. Eco-design directives coming into force by 2027 will require precise energy-consumption metrics at the machine level, nudging OEMs toward high-efficiency servo motors. Germany continues to lead in technical textiles for automotive and aerospace, prompting demand for heavy-duty programmable bartackers. Italy's luxury fashion houses employ specialized hand-guided embroiderers alongside automated equipment to uphold "Made in Italy" authenticity. Eastern European factories in Romania and Bulgaria win orders redirected from Asia due to logistics volatility, necessitating rapid scale-up in machine fleets.
South America exhibits steady momentum as Brazil's garment cluster in Santa Catarina modernizes, deploying servo-motor retrofits to capture energy savings under rising electricity tariffs. Uruguay and Paraguay court Chinese investors for integrated cotton-to-apparel complexes that could localize equipment demand. Meanwhile, Chile's e-commerce penetration fosters hobbyist uptake of compact home machines designed for small apartments. Currency fluctuations remain the principal headwind, often delaying purchase decisions for imported machines until exchange rates stabilize.
- Brother Industries, Ltd.
- JUKI Corporation
- SVP Worldwide (Singer(R), Husqvarna Viking(R), Pfaff(R))
- Janome Sewing Machine Co., Ltd.
- Bernina International AG
- Mitsubishi Electric Corp. (Industrial Sewing Machinery)
- Jack Sewing Machine Co., Ltd.
- Pegasus Sewing Machine Mfg. Co., Ltd.
- Toyota Industries Corp. (TACHINO)
- Baby Lock / Tacony Corporation
- Zoje Sewing Machine Co., Ltd.
- Feiyue Group Co., Ltd.
- Union Special LLC
- Rimoldi & CF
- SunStar Co., Ltd.
- Yamato Sewing Machine Mfg. Co., Ltd.
- Typical Sewing Machine Co., Ltd.
- Seiko Sewing Machine Co., Ltd.
- Merrow Sewing Machine Company
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid apparel-manufacturing expansion in APAC
- 4.2.2 DIY & craft culture revival in mature economies
- 4.2.3 Advancements in IoT-enabled and CNC sewing machines
- 4.2.4 Industrial automation push for productivity
- 4.2.5 Near-shoring boosts demand for small-batch industrial units
- 4.2.6 Sustainability-driven "repair & reuse" consumer movement
- 4.3 Market Restraints
- 4.3.1 High capital outlay for industrial machines
- 4.3.2 Proliferation of low-cost refurbished units
- 4.3.3 Electronics supply-chain bottlenecks (MCUs, servos)
- 4.3.4 Shortage of skilled operators for advanced models
- 4.4 Industry Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
- 4.6 Insights into the Latest Trends and Innovations in the Market
- 4.7 Insights on Recent Developments (New Product Launches, Strategic Initiatives, Investments, Partnerships, JVs, Expansion, M&As, etc.) in the Market
5 Market Size & Growth Forecasts
- 5.1 By Machine Type
- 5.1.1 Manual
- 5.1.2 Electric
- 5.1.3 Automated
- 5.1.4 Other Machine Types
- 5.2 By Application
- 5.2.1 Apparel & Fashion
- 5.2.2 Non-apparel Textiles (Automotive, Upholstery)
- 5.2.3 Footwear & Leather Goods
- 5.2.4 Home Textiles & Crafts
- 5.2.5 Other Applications
- 5.3 By End User
- 5.3.1 Residential
- 5.3.2 Industrial
- 5.4 By Distribution Channel
- 5.4.1 B2C/Retail
- 5.4.1.1 Multi-brand Stores
- 5.4.1.2 Exclusive Brand Outlets
- 5.4.1.3 Online
- 5.4.1.4 Other Distribution Channels
- 5.4.2 B2B/Directly from the Manufacturers
- 5.4.1 B2C/Retail
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 Canada
- 5.5.1.2 United States
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Peru
- 5.5.2.3 Chile
- 5.5.2.4 Argentina
- 5.5.2.5 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Spain
- 5.5.3.5 Italy
- 5.5.3.6 BENELUX (Belgium, Netherlands, Luxembourg)
- 5.5.3.7 NORDICS (Denmark, Finland, Iceland, Norway, Sweden)
- 5.5.3.8 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 India
- 5.5.4.2 China
- 5.5.4.3 Japan
- 5.5.4.4 Australia
- 5.5.4.5 South Korea
- 5.5.4.6 South-East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, Philippines)
- 5.5.4.7 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 South Africa
- 5.5.5.4 Nigeria
- 5.5.5.5 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Brother Industries, Ltd.
- 6.4.2 JUKI Corporation
- 6.4.3 SVP Worldwide (Singer(R), Husqvarna Viking(R), Pfaff(R))
- 6.4.4 Janome Sewing Machine Co., Ltd.
- 6.4.5 Bernina International AG
- 6.4.6 Mitsubishi Electric Corp. (Industrial Sewing Machinery)
- 6.4.7 Jack Sewing Machine Co., Ltd.
- 6.4.8 Pegasus Sewing Machine Mfg. Co., Ltd.
- 6.4.9 Toyota Industries Corp. (TACHINO)
- 6.4.10 Baby Lock / Tacony Corporation
- 6.4.11 Zoje Sewing Machine Co., Ltd.
- 6.4.12 Feiyue Group Co., Ltd.
- 6.4.13 Union Special LLC
- 6.4.14 Rimoldi & CF
- 6.4.15 SunStar Co., Ltd.
- 6.4.16 Yamato Sewing Machine Mfg. Co., Ltd.
- 6.4.17 Typical Sewing Machine Co., Ltd.
- 6.4.18 Seiko Sewing Machine Co., Ltd.
- 6.4.19 Merrow Sewing Machine Company
7 Market Opportunities & Future Outlook
- 7.1 Growing demand for compact and portable sewing machines
- 7.2 Increasing prevalence of smart (integration of IoT and AI) and computerized sewing machines

 可攜式物聯網封條市場:全球市場預測,2026-2032年
 第二層蓋熱封機市場規模、佔有率和成長分析:按機器類型、密封技術、容器材料、應用、最終用途產業和地區分類-產業預測(2026-2033 年)
 多針刺繡機市場分析及預測至 2035 年:類型、產品、技術、組件、應用、材料類型、最終用戶、功能、安裝配置。
 熱封機市場機會、成長要素、產業趨勢分析及2026-2035年預測。縫紉機市場-2026-2032年全球市場預測
 全球服裝裁剪和修改服務市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 半油式鎖式縫紉機市場預測至2034年:按產品類型、應用和地區分類的全球分析
 縫紉機市場報告:按產品類型、應用、銷售管道和地區分類(2026-2034 年)
 2026年全球服裝裁剪與修改服務市場報告家用縫紉機市場:按機器類型、價格範圍、分銷管道和應用分類,全球預測(2026-2032年)