


 |
市場調查報告書
商品編碼
2122752
LED驅動器:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031年)LED Driver - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
據 Mordor Intelligence 稱,LED 驅動器市場預計到 2026 年價值 247.1 億美元,高於 2025 年的 201.9 億美元,預計到 2031 年將達到 678.4 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 22.38%。
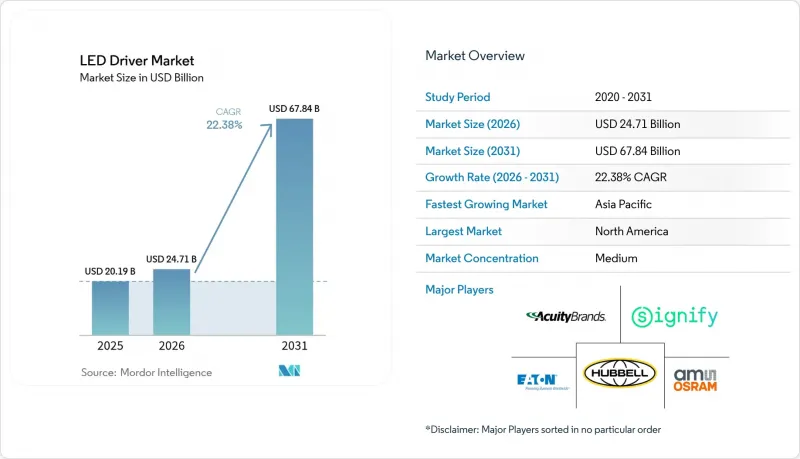
本報告按產品類型(恆定電流LED驅動器及其他)、控制功能(有線、無線)、輸出功率(25W以下、25-65W及其他)、外形規格(外部獨立式、整合/板載式及其他)、最終用途(住宅、商業/辦公室、零售/酒店及其他)和地區進行細分。市場預測以美元(USD)為單位。
全球LED驅動器市場趨勢與洞察
政府補貼的LED更換計畫正在推動市場加速發展。
印度的「UJALA」舉措表明,大規模採用高效節能燈具每年可減少20吉瓦的電力需求,並避免8,000萬噸二氧化碳排放。與以往的折扣方案不同,該計劃採用市場機制,維持了供應商的利潤率,並鼓勵持續的產品升級,重點是推廣具有能源監控功能的高級驅動器。中國、馬來西亞和歐盟的類似計畫正在從燈泡更換轉向整燈更換,從而刺激了對支援無線控制、目標功率因數為0.9或更高、並符合IEC閃爍標準的驅動器的需求。隨著LED燈具第一波普及浪潮在2015年前後全面展開,預計第二波58億檯燈具的更換週期將在2025年至2028年間達到高峰。這些計劃透過確保在整個預測期內可預測的大批量採購,為LED驅動器市場注入了整體動力。
GaN-on-Si驅動IC價格的快速下降正在推動其普及應用。
德州儀器 (TI) 從 6 吋到 8 吋 GaN 晶圓的過渡正在降低晶圓成本,提高良率穩定性,將功率轉換效率提升至 92% 以上,並降低散熱成本。英飛凌 (Infineon) 的 300 毫米試驗線預計將在 2025 年實現矽級定價,從而進入零售卡車照明和消費電子照明等主流市場。 GaN 的高開關頻率可使磁性元件尺寸縮小高達 40%,從而實現更薄的照明燈具和更低的機殼溫度,這對於板載晶片)模組至關重要。在汽車頭燈系統中,GaN 的高結溫耐受性也展現出巨大價值,支援電動車 (EV) 的自我調整光束架構。這些經濟優勢構成了一個良性循環的整合基礎:隨著產量的增加,成本將持續降低,從而進一步擴大 LED 驅動器市場。
矽材料持續供應緊張,導致驅動晶片生產出現瓶頸。
Wolfspeed的融資困境正威脅著用於高功率照明和電動車應用的碳化矽(SiC)晶圓的供應。代工廠優先生產先進的3nm邏輯晶片,導致用於LED驅動器混合訊號製程的16-90nm製程產能緊張。典型MOSFET的前置作業時間超過40週,而專用PMIC的交貨週期甚至可能超過一年,迫使企業修改設計並採用多供應商籌資策略。這些供應限制導致價格波動,擠壓了中型OEM廠商的利潤空間。因此,在諸如戶外照明項目等設有固定競標上限的領域,短期出貨前景正在放緩。在東南亞產能大幅提升之前,矽供不應求預計仍將嚴重拖累LED驅動器市場。
細分市場分析
恆流裝置憑藉著數十年來在高流明應用領域的設計經驗,預計2025年將佔據LED驅動器市場60.55%的佔有率。然而,轉換效率高達92%且無需重新設計即可適應可變電壓LED負載的恒定功率驅動器,預計將在2026年至2031年間以22.96%的複合年成長率成長。在車子頭燈這個細分市場,英飛凌的「Litix Power Flex」系列展現出顯著的性能提升。 SPI控制調光和多串保護等功能在不增加發熱量的情況下擴展了產品功能。
自我調整照明的普及正在推動這一轉變。對於建築立面、體育場館和可調光辦公照明燈具而言,能夠在保持電流在二極體容差範圍內的同時動態調節輸出是一項顯著優勢。這種多功能性使照明製造商能夠最大限度地減少產品型號的增加,並方便現場升級。隨著無線協定和韌體可選功率特性曲線的興起,恒定功率設計正成為不斷發展的LED驅動器市場中的首選平台。
以DALI和0-10V為主導的有線系統,由於控制線已嵌入現有結構中,預計到2025年將佔據LED驅動器市場64.82%的佔有率。然而,無線功能正處於快速普及階段,預計到2031年複合年成長率將達到23.62%。 Regran的Matter認證牆盒調光器展現出消費者對基於應用程式的初始設定的濃厚興趣。
從總成本角度來看,取消控制佈線可將商業設施維修預算中的人事費用降低 15% 至 25%,在許多情況下,LED 和控制系統的組合更具投資回報率優勢。 Thread 的 IPv6 基礎設施便於與建築管理系統整合,而 BLE 網狀網路則為不連續照明巡檢提供了低功耗的備用機制。隨著無線韌體更新的普及,無線驅動器透過支援未來的功能來延長其使用壽命。這些優勢鞏固了無線技術作為 LED 驅動器市場支柱的地位。
區域分析
預計到2025年,北美市場將佔據31.96%的銷售佔有率,這主要歸功於嚴格的燈具能源效率法規,該法規規定了83-195 lm/W的高標準,引導規範制定者選擇高效驅動器。企業維修案例,例如可口可樂聯合公司升級改造六家工廠,每年可節省97,063美元,印證了投資回報迅速的說法。 《晶片法案》(CHIPS Act)撥款2000億美元用於國內半導體製造工廠,加強了類比和功率元件的供應鏈。加拿大和墨西哥正利用一體化的供應鏈共用技術標準和認證測試實驗室,促進跨境運輸。
亞太地區正經歷最快的結構性成長,預計到2031年複合年成長率將達到23.51%。中國強大的製造業基礎正在大幅降低物料清單(BOM),而地方政府的智慧城市津貼正在刺激該地區對配備NB-IoT和LoRa閘道器的駕駛員的需求。在印度,史上規模最大的UJALA計畫正在補充報廢燈具庫存,開啟照明昇級的第二波浪潮。日本、韓國和台灣正在將電動車主導技術創新轉向可出口的自我調整光束驅動器。供應鏈多元化正在東協市場推進,越南正在崛起成為北美品牌的最終加工和組裝中心。
在歐洲,這一動能正透過「2019/2020生態設計計畫」得以延續,該計畫旨在2030年每年節省96太瓦時(TWh)的電力。德國復興信貸銀行(KfW)的補貼計畫將優惠利率與智慧照明的引入掛鉤,加速物流倉庫驅動器的更換。歐盟團結基金為東歐的維修計畫提供支持,而英國的建築法規「L部分」則包含動態照明指南,建議使用支持開放協議通訊的驅動器。在中東和非洲,「2030願景」計畫正在擴大全球LED驅動器市場,沙烏地阿拉伯的LED普及率(年複合成長率9.6%)在當地組裝計畫的推動下,便是一個典型的例子。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 政府補貼升級LED照明(從2025年開始實施)
- 氮化鎵矽基驅動積體電路價格快速下降
- 新建築規範強制要求安裝智慧照明系統。
- Matter/Thread無線控制的主流化
- 電動車頭燈用LED驅動器的需求正在激增。
- 透過企業淨零排放目標加速工業進步
- 市場限制因素
- 由於矽供應持續受限,驅動晶片生產出現瓶頸。
- 傳統有線協定互通性的局限性
- 非隔離驅動器的設計複雜性
- 對中國製造的恆流模組徵收高額進口關稅
- 供應鏈分析
- 技術展望
- 監理情勢
- 波特五力模型
- 對影響市場的宏觀經濟因素進行評估
第5章 市場規模與成長預測
- 依產品類型
- 恆定電流LED驅動器
- 恆壓LED驅動器
- 恒定功率LED驅動器
- 透過控制功能
- 有線
- 0~10V
- DALI
- DMX
- PLC
- 後緣
- 無線的
- Wi-Fi
- Bluetooth/BLE
- Zigbee
- Thread/Matter
- Li-Fi
- 有線
- 依輸出類型
- 25瓦或以下
- 25~65W
- 65~150W
- 超過150瓦
- 按外形規格
- 外部獨立型
- 整合/板載
- 線性驅動器
- 緊湊型模組化驅動器
- 按最終用途
- 住宅
- 商業和辦公
- 零售和酒店
- 戶外和街道照明
- 產業
- 醫療保健和教育
- 汽車照明系統
- 園藝和農業
- 家用電器背光燈
- 其他
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 韓國
- 印度
- 其他亞太國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 卡達
- 其他中東國家
- 非洲
- 南非
- 埃及
- 奈及利亞
- 肯亞
- 其他非洲地區
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Signify
- ams OSRAM
- Acuity Brands Lighting
- Hubbell Incorporated
- Eaton(Cooper Lighting)
- Lutron Electronics
- Cree LED(SGH)
- MEAN WELL Enterprises
- Inventronics
- Tridonic(Zumtobel)
- Delta Electronics
- Shenzhen Done Power
- ERP Power
- Lifud Technology
- Helvar
- Murata Manufacturing
- Texas Instruments
- ON Semi
- Allegro MicroSystems
- ROHM Semiconductor
- Macroblock Inc.
- TCI Srl
- MOSO Power
- Current(GE)
第7章 市場機會與未來展望
第8章 投資分析
According to Mordor Intelligence, LED driver market size in 2026 is estimated at USD 24.71 billion, growing from 2025 value of USD 20.19 billion with 2031 projections showing USD 67.84 billion, growing at 22.38% CAGR over 2026-2031.
This report is Segmented by Product Type (Constant Current LED Drivers, and More), Control Feature (Wired, Wireless), Power Output (Less Than25W, 25-65W, and More), Form Factor (External Stand-Alone, Integrated/On-Board, and More), End-Use Application (Residential, Commercial and Office, Retail and Hospitality, and More), and by Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global LED Driver Market Trends and Insights
Subsidy-fuelled LED Retrofit Programs Drive Market Acceleration
India's UJALA initiative illustrates how large-scale distribution of efficient lamps can slash electricity demand by 20 GW and avoid 80 million t of CO2 annually. Unlike earlier discount schemes, the program's market-based approach sustained vendor margins, encouraging continual product upgrades that now emphasize advanced drivers with energy-monitoring functions. Similar schemes in China, Malaysia and the European Union are moving from bulb replacements toward holistic luminaire swaps, triggering demand for drivers that support wireless controls, target power factors above 0.9 and meet IEC flicker criteria. Because early LED waves entered service around 2015, a secondary replacement cycle of 5.8 billion units begins peaking between 2025 and 2028. These programs collectively add momentum to the LED driver market by ensuring predictable, large-volume procurement pipelines over the forecast period.
Rapid Price Declines in GaN-on-Si Driver ICs Enable Mass Adoption
Texas Instruments' migration from 6-inch to 8-inch GaN wafers cuts die cost while improving yield consistency, pushing power-conversion efficiency beyond 92% and shrinking thermal budgets.Infineon's 300 mm pilot line is expected to reach silicon-parity pricing in 2025, opening mainstream channels such as retail track lighting and appliance illumination. GaN's higher switching frequencies reduce magnetics size by up to 40%, enabling slimmer luminaire profiles and lowering enclosure temperatures, a critical factor for chip-on-board modules. Automotive headlamp systems benefit from GaN's resilience at high junction temperatures, supporting adaptive-beam architectures in electric vehicles. These economics support a virtuous cycle of integration: as volumes climb, cost drops deepen, broadening the LED driver market even further.
Persistent Silicon Supply Constraints Create Bottlenecks in Driver IC Production
Wolfspeed's liquidity pressures threaten silicon-carbide wafer availability for high-power lighting and EV applications. Foundries prioritize advanced 3-nm logic, leaving 16-90 nm capacity thin for the mixed-signal processes used in LED drivers. Lead times exceed 40 weeks for common MOSFETs; speciality PMICs stretch beyond a year, forcing design pivots and multi-sourcing strategies. The constraint drives price volatility that squeezes mid-tier OEM margins, dampening near-term shipment potential in segments such as outdoor lighting projects with firm bid ceilings. Until capacity additions in Southeast Asia come online, silicon shortfalls remain a measurable drag on the LED driver market.
Other drivers and restraints analyzed in the detailed report include:
- Smart-Lighting Mandates in New-Build Codes Create Compliance-Driven Demand
- Mainstream Adoption of Matter/Thread Wireless Controls Standardizes Connectivity
- Limited Interoperability Across Legacy Wired Protocols Fragments Market Adoption
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Constant current devices held 60.55% LED driver market share in 2025, driven by decades of design familiarity in high-lumen applications. However, constant power drivers deliver up to 92% conversion efficiency and accommodate variable-voltage LED loads without redesign, supporting a projected 22.96% CAGR between 2026 and 2031. In the automotive front-lighting niche, Infineon's Litix Power Flex series illustrates the performance jump: SPI-controlled dimming and multi-string protection broaden functionality without thermal penalty.
The rise of adaptive lighting scenarios reinforces the shift. Architectural facades, sports arenas and tunable-white office fixtures benefit when output can adjust dynamically while current remains within diode tolerances. This versatility lowers SKU proliferation for luminaire makers and enhances field-upgrade paths. As wireless protocols proliferate, firmware-selectable power curves make constant power designs the preferred platform in the evolving LED driver market.
Wired systems, led by DALI and 0-10 V, accounted for 64.82% of the LED driver market size in 2025 because existing-bearing structures embed control cabling. Yet wireless features head into the steep part of the adoption curve, with a 23.62% CAGR through 2031. Legrand's Matter-approved wall-box dimmers demonstrate consumer enthusiasm for app-based commissioning.
From a total-cost lens, eliminating control wires trims labour 15-25% in commercial retrofit budgets, often swinging ROI in favour of LED plus controls. Thread's IPv6 foundation eases building-management integration, and BLE mesh provides low-energy fallback for emergency lighting checks. With over-the-air firmware updates now mainstream, wireless drivers extend operating lifetimes by accommodating future features. These advantages cement wireless as a pillar of the LED driver market.
Complete Report Scope:
- By Product Type
- Constant Current LED Drivers
- Constant Voltage LED Drivers
- Constant Power LED Drivers
- By Control Feature
- Wired
- 0-10 V
- DALI
- DMX
- PLC
- Trailing-Edge
- Wireless
- Wi-Fi
- Bluetooth/BLE
- Zigbee
- Thread / Matter
- Li-Fi
- Wired
- By Power Output
- Less than 25 W
- 25 - 65 W
- 65 -150 W
- Greater than 150 W
- By Form Factor
- External Stand-Alone
- Integrated / On-Board
- Linear Drivers
- Compact / Module Drivers
- By End-Use Application
- Residential
- Commercial and Office
- Retail and Hospitality
- Outdoor and Street Lighting
- Industrial
- Healthcare and Education
- Automotive Lighting Systems
- Horticulture and Agriculture
- Consumer-Electronics Backlighting
- Other Applications
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Qatar
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Nigeria
- Kenya
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America's 31.96% revenue share in 2025 derives from rigorous lamp-efficacy rules that raise the bar to 83-195 lm/W, steering specifiers toward high-efficiency drivers. Corporate retrofits such as Coca-Cola Consolidated's six-facility upgrade realize USD 97,063 annual savings and underline the quick payback narrative. The CHIPS Act allocates USD 200 billion for domestic fabs, improving resilience for analog and power components. Canada and Mexico leverage integrated supply chains to share technical standards and qualification labs, smoothing cross-border shipments.
Asia-Pacific exhibits the fastest structural rise, projecting a 23.51% CAGR through 2031. China's manufacturing depth slashes BOM costs, and its municipal smart-city grants stimulate local demand for drivers with NB-IoT or LoRa gateways. India's record-scale UJALA program replenishes lamp inventories at end-of-life, kick-starting a second-wave luminaire upgrade cycle. Japan, South Korea and Taiwan channel EV-led headlamp innovations into exportable adaptive-beam drivers. ASEAN markets absorb supply-chain diversification, with Vietnam emerging as a finish-and-assembly hub for North American brands.
Europe sustains momentum through Ecodesign 2019/2020, which targets 96 TWh savings annually by 2030. Germany's KfW-bank subsidies tie preferential interest rates to intelligent-lighting deployment, accelerating driver replacements in logistics warehouses. Eastern European retrofit pipelines receive cohesion-fund backing, while the United Kingdom's Building Regulations Part L references dynamic-lighting guidance that favours drivers capable of open-protocol communication. The Middle East and Africa supplement the global LED driver market with Vision 2030 programs, typified by Saudi Arabia's 9.6% CAGR LED adoption outlook underpinned by local assembly ventures.
- Signify
- ams OSRAM
- Acuity Brands Lighting
- Hubbell Incorporated
- Eaton (Cooper Lighting)
- Lutron Electronics
- Cree LED (SGH)
- MEAN WELL Enterprises
- Inventronics
- Tridonic (Zumtobel)
- Delta Electronics
- Shenzhen Done Power
- ERP Power
- Lifud Technology
- Helvar
- Murata Manufacturing
- Texas Instruments
- ON Semi
- Allegro MicroSystems
- ROHM Semiconductor
- Macroblock Inc.
- TCI Srl
- MOSO Power
- Current (GE)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Subsidy-fuelled LED retrofit programs (post-2025 roll-outs)
- 4.2.2 Rapid price declines in GaN-on-Si driver ICs
- 4.2.3 Smart-lighting mandates in new-build codes
- 4.2.4 Mainstream adoption of Matter/Thread wireless controls
- 4.2.5 Surge in EV headlamp LED driver demand
- 4.2.6 Corporate net-zero targets accelerating industrial upgrades
- 4.3 Market Restraints
- 4.3.1 Persistent silicon supply constraints for driver ICs
- 4.3.2 Limited interoperability across legacy wired protocols
- 4.3.3 Design-in complexity for non-isolated drivers
- 4.3.4 High import tariffs on Chinese constant-current modules
- 4.4 Supply-Chain Analysis
- 4.5 Technological Outlook
- 4.6 Regulatory Landscape
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Assesment of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Constant Current LED Drivers
- 5.1.2 Constant Voltage LED Drivers
- 5.1.3 Constant Power LED Drivers
- 5.2 By Control Feature
- 5.2.1 Wired
- 5.2.1.1 0-10 V
- 5.2.1.2 DALI
- 5.2.1.3 DMX
- 5.2.1.4 PLC
- 5.2.1.5 Trailing-Edge
- 5.2.2 Wireless
- 5.2.2.1 Wi-Fi
- 5.2.2.2 Bluetooth/BLE
- 5.2.2.3 Zigbee
- 5.2.2.4 Thread / Matter
- 5.2.2.5 Li-Fi
- 5.2.1 Wired
- 5.3 By Power Output
- 5.3.1 Less than 25 W
- 5.3.2 25 - 65 W
- 5.3.3 65 -150 W
- 5.3.4 Greater than 150 W
- 5.4 By Form Factor
- 5.4.1 External Stand-Alone
- 5.4.2 Integrated / On-Board
- 5.4.3 Linear Drivers
- 5.4.4 Compact / Module Drivers
- 5.5 By End-Use Application
- 5.5.1 Residential
- 5.5.2 Commercial and Office
- 5.5.3 Retail and Hospitality
- 5.5.4 Outdoor and Street Lighting
- 5.5.5 Industrial
- 5.5.6 Healthcare and Education
- 5.5.7 Automotive Lighting Systems
- 5.5.8 Horticulture and Agriculture
- 5.5.9 Consumer-Electronics Backlighting
- 5.5.10 Other Applications
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Russia
- 5.6.3.7 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 South Korea
- 5.6.4.4 India
- 5.6.4.5 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Saudi Arabia
- 5.6.5.1.2 United Arab Emirates
- 5.6.5.1.3 Turkey
- 5.6.5.1.4 Qatar
- 5.6.5.1.5 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Egypt
- 5.6.5.2.3 Nigeria
- 5.6.5.2.4 Kenya
- 5.6.5.2.5 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Signify
- 6.4.2 ams OSRAM
- 6.4.3 Acuity Brands Lighting
- 6.4.4 Hubbell Incorporated
- 6.4.5 Eaton (Cooper Lighting)
- 6.4.6 Lutron Electronics
- 6.4.7 Cree LED (SGH)
- 6.4.8 MEAN WELL Enterprises
- 6.4.9 Inventronics
- 6.4.10 Tridonic (Zumtobel)
- 6.4.11 Delta Electronics
- 6.4.12 Shenzhen Done Power
- 6.4.13 ERP Power
- 6.4.14 Lifud Technology
- 6.4.15 Helvar
- 6.4.16 Murata Manufacturing
- 6.4.17 Texas Instruments
- 6.4.18 ON Semi
- 6.4.19 Allegro MicroSystems
- 6.4.20 ROHM Semiconductor
- 6.4.21 Macroblock Inc.
- 6.4.22 TCI Srl
- 6.4.23 MOSO Power
- 6.4.24 Current (GE)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment
- 7.2 Emerging Opportunities in Non-Isolated Drivers
- 7.3 Visible-Light Communication Integration
- 7.4 GaN and SiC-based Driver IC Adoption
8 INVESTMENT ANALYSIS

 無電感LED驅動器市場:全球市場預測,2026-2032年
 脈衝寬度調變 (PWM) LED 驅動器市場規模、佔有率和成長分析:按產品類型、PWM 頻率、應用、最終用戶和地區分類-2026-2033 年產業預測
 LED驅動器市場報告:趨勢、預測和競爭分析(至2035年)LED驅動器市場:2026-2032年全球市場預測(按產品類型、輸出電流、輸入類型、安裝方式、應用、最終用戶和分銷管道分類)
 LED驅動器市場規模、佔有率、趨勢和預測:按組件、照明燈具類型、供應方式、最終用戶和地區分類,2026-2034年
 照明變壓器市場規模、佔有率和成長分析:按類型、功率等級、應用和地區分類-2026-2033年產業預測
 全球LED驅動器市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 LED驅動器市場規模、佔有率和趨勢分析報告:按照明燈具類型、組件、供應類型、應用、地區和細分市場預測,2026-2033年
 2026年全球LED驅動器市場報告LED照明驅動器全球市場報告(2026年)