


 |
市場調查報告書
商品編碼
2122649
越野車:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)Off-road Vehicle - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 估計,到 2026 年,越野車市值將達到 243.3 億美元,高於 2025 年的 224.7 億美元,預計到 2031 年將達到 362.5 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 8.28%。
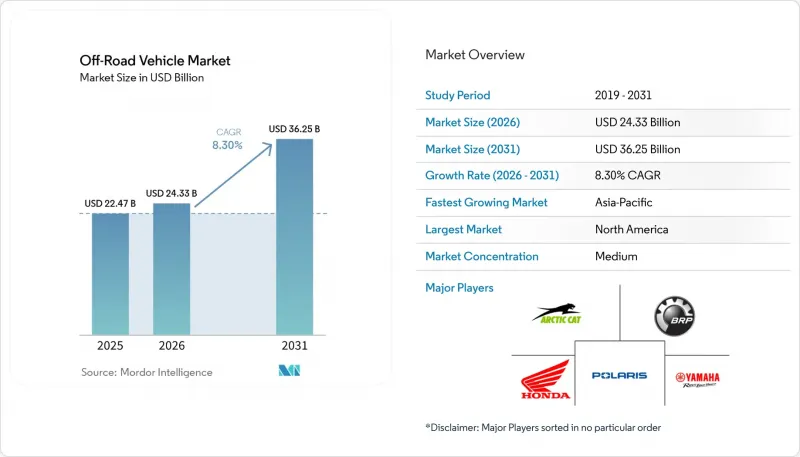
本報告按車輛類型(例如,全地形車)、應用領域(例如,運動和休閒)、動力類型(例如,內燃機)、引擎排氣量(例如,小於400cc)、功率輸出(例如,小於50kW)、驅動系統(例如,兩輪驅動)、座位數和地區進行分類。市場預測以貨幣價值(美元)和銷售(輛)兩種形式呈現。
全球越野車市場趨勢及洞察
戶外休閒旅遊的激增
2024年,戶外休閒為美國GDP貢獻了1.2兆美元,佔國內生產總值的2.3%,並創造了大量就業機會。參與人數的增加帶動了全地形車(ATV)和多用途車(UTV)的銷售成長,這些車輛主要用於越野騎行和長途旅行。 2024年,摩托車和全地形車的使用創造了相當大比例的經濟附加價值,凸顯了越野車市場的強勁需求。各州政府的津貼項目進一步放大了這項效應。科羅拉多州戶外休閒基金會撥款大量資金用於改善道路設施的項目,而奧勒岡州的配套津貼則促進了當地製造業叢集的發展。步道系統正在產生強大的連鎖效應。明尼蘇達州的雪上摩托車網路每年創造可觀的旅遊收入,增強了該行業對當地經濟的乘數效應,並穩定了季節性車輛銷售。
國防機構採購戰術全地形車/多用途車
國防機構正在尋求輕型、機動性強的裝備,用於邊防安全、特種作戰以及在惡劣地形中的後勤支援。即將進行的印度北部邊境競標明確要求裝備直升機吊掛能力、四人座艙佈局以及自主導航選項,以最大限度地提高戰術性柔軟性。由芬蘭協調的歐洲FAMOUS計畫專注於北極作戰能力,包括能夠在-46 度C低溫下啟動的車輛以及在冰雪融化季節具備兩棲作戰能力的裝備。美國每年撥出固定資金用於購買超輕型作戰車輛(ULCV),這些車輛的重量上限為4500磅,續航里程為250英里。這些項目的推動作用促使供應商開發可容納裝甲套件、反無人機感測器和混合動力傳動系統的模組化底盤,導致累積訂單增加,儘管民營市場存在週期性波動。
電動動力傳動系統所需的鋰供應鏈正面臨壓力。
目前,中國提煉了全球五分之三以上的鋰,並生產了五分之四的電池,隨著需求激增,這對全球原始設備製造商(OEM)構成了威脅。美國已根據《通貨膨脹控制法案》撥款用於國內鋰提煉,但授權障礙和社區擔憂延緩了採礦作業的啟動。電化學提取新創公司承諾提供環保解決方案,但它們仍處於商業化前期。在供應來源多元化之前,電池價格可能會繼續波動,這可能會阻礙實現“總成本平價”,而這對於加速電動全地形車(ATV)的普及至關重要,尤其是在對價格敏感的發展中市場。
細分市場分析
多功能越野車(UTV)和並排式越野車憑藉其載客量、載貨量和先進的懸吊技術,預計到2025年將佔據越野車市場50.68%的佔有率。在休閒、農業和國防等領域訂單的推動下,這個細分市場在越野車市場中已發展壯大。隨著原始設備製造商(OEM)推出15千瓦時電池組,最高時速可達80公里/小時,充電時間不到3小時,電動UTV衍生車型目前以8.32%的複合年成長率(CAGR)領先市場。
在對車身寬度限制嚴格且偏好窄底盤的地區,全地形車 (ATV) 的需求仍然強勁。相較之下,在極端天氣頻繁的地區,兩棲車和雪上摩托車的需求依然強勁。與競爭對手相比,其主要優勢包括可調節懸吊、北極星的「DYNAMIX」LiveValve 架構以及配備觸控螢幕 Ride Command 系統的數位化駕駛艙。因此,北極星的產品組合兼顧了傳統內燃機 (ICE) 車輛的銷售和新興的電氣化成長,使汽車製造商能夠有效規避動力系統的不確定性。
預計到2025年,體育休閒產業將佔越野車市場的41.05%,受益於數百萬美國人戶外活動帶來的創紀錄的越野車道使用率。軍方和執法機關的需求預計將以8.35%的複合年成長率成長,因為採購機構正在尋求可由直升機運輸並具備混合式靜音監視模式的吊掛戰術機動解決方案。
在農業和林業領域,對配備動力輸出軸驅動農具的中排量UTV的需求日益成長,而建設公司需要大負載容量車輛進行長途物流運輸。諸如嚮導式越野探險等新型旅遊模式,進一步拓展了UTV的商業應用場景。因此,UTV的多功能性確保了即使消費者自由裁量權支出下降,也能維持基準的銷售表現。
2025年,在完善的加油基礎設施和成熟的供應鏈的支持下,內燃機汽車將佔據非道路車輛市場83.05%的佔有率。然而,由於政策支持和電池成本下降,電池式電動車的複合年成長率預計將達到8.30%,成為成長最快的車型。
這種混合增程器概念將10千瓦時的電池組與緊湊型發電機相結合,在不犧牲低速扭矩的前提下延長續航里程,從而解決了客戶的顧慮。雖然氫燃料電池原型仍處於研發階段,但它們為在寒冷氣候下快速加氫的大型救援車輛的部署鋪平了道路。動力系統的多樣化降低了監管風險,同時也促進了電池租賃和回收等新型供應商生態系統的形成。
區域分析
預計到2025年,北美將佔據越野車市場37.84%的佔有率。這得益於戶外休閒在GDP中的高佔比,以及各州透過津貼發展起來的龐大越野車道網路。在被稱為「雪帶」的各州,每年都會對越野車道維護項目進行巨額投資,從而促進旅遊收入成長。威斯康辛州和阿拉斯加州透過補貼100%符合資格的越野車道維護費用,確保即使在經濟放緩時期也能維持穩定的需求。與經銷商建立的融資合作關係,例如謝菲爾德金融公司與北極星公司續約,使得購車者更容易獲得融資,並維持了展示室的周轉率。然而,加拿大各省對自然保護區的監管規定帶來了營運上的複雜性,迫使汽車製造商提供更安靜的動力傳動系統和符合排放氣體法規的引擎,以滿足許可證標準。
亞太地區預計將成為成長最快的地區,到2031年複合年成長率將達到8.42%,這主要得益於日益都市化的中產階級消費者對戶外生活方式品牌的追捧,以及政府對農村交通基礎設施的投資。在印度,全地形車(ATV)的銷售成長迅猛,這得益於探險旅遊的推廣和農業機械化的進步。像CFMOTO這樣的區域性原始設備製造商(OEM)正利用垂直整合的供應鏈提供具有競爭力的價格,這使它們贏得了出口契約,並佔據了全球五分之二的市場佔有率。
儘管歐洲經濟成長滯後,但監管法規的推廣與電氣化需求不謀而合。針對非道路車輛(NRMM)的第五階段排放氣體法規正在推動後後處理技術和替代動力傳動系統研發投入的增加,間接促進了混合動力和燃料電池概念的創新。將於2028年生效的新NRMM法規規定小批量生產的閾值為70輛,為小眾電動新創公司提供了切實可行的認證流程。北歐國家已推出長期步道維護補貼計畫以刺激旅遊業發展,德國和奧地利目前也考慮在阿爾卑斯山區推行類似措施。因此,儘管合規成本可能會限制短期銷量,但長期需求將轉向低排放車型,使歐洲供應商能夠透過溢價收回投資。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 戶外休閒旅遊的激增
- 國防部隊採購戰術全地形車/多用途車
- 中型農場的快速機械化
- 實施先進的EPS和遠端資訊處理技術
- 無人機攝影對低噪音/靜音電動全地形車的需求
- 斯堪的納維亞半島對步道維護的補貼正在擴大自行車網路。
- 市場限制因素
- 高昂的初始成本和生命週期成本
- 電動動力傳動系統所需的鋰供應鏈正面臨壓力。
- 更嚴格的法規和更廣泛的限速措施,以防止人員傷亡。
- 禁止在保護區內使用
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 車輛類型
- 全地形車(ATV)
- 多用途作業車輛(UTV)/並排式全地形車
- 越野摩托車
- 雪上摩托車
- 兩棲車輛與特殊越野車輛
- 透過使用
- 體育和休閒
- 農業和林業
- 工業與建築
- 軍事和執法機關
- 其他商業用途(旅遊、搜救)
- 依推進類型
- 內燃機(汽油/柴油)
- 混合
- 電池式電動車
- 氫燃料電池
- 按引擎排氣量(cc)
- 小於400毫升
- 400~800 cc
- 超過 800 毫升
- 按輸出功率(千瓦)
- 小於50千瓦
- 50~100 kW
- 超過100千瓦
- 透過驅動系統
- 兩輪驅動
- 四輪驅動/全輪驅動
- 按座位數
- 單人騎乘
- 雙座
- 3人或以上
- 按地區
- 北美洲
- 美國
- 加拿大
- 其他北美國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 德國
- 法國
- 英國
- 義大利
- 西班牙
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 澳洲
- 其他亞太國家
- 中東和非洲
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 土耳其
- 埃及
- 南非
- 其他中東和非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Polaris Inc.
- Bombardier Recreational Products Inc.(Can-Am)
- Yamaha Motor Corp.
- Textron Inc.(Arctic Cat)
- Kawasaki Heavy Industries Ltd.
- Suzuki Motor Corp.
- Honda Motor Co. Ltd.
- CFMOTO Powersports Inc.
- Kwang Yang Motor Co. Ltd.(Kymco)
- American LandMaster
- Tracker Off-Road(Bass Pro Shops)
- Kubota Corp.(RTV)
- John Deere(Gator)
- Mahindra & Mahindra Ltd.
- Segway Powersports
- Hisun Motors Corp.
- Linhai Group
- TGB(Taiwan Golden Bee)
- DRR USA
第7章 市場機會與未來展望
According to Mordor Intelligence, off-road vehicle market size in 2026 is estimated at USD 24.33 billion, growing from 2025 value of USD 22.47 billion with 2031 projections showing USD 36.25 billion, growing at 8.28% CAGR over 2026-2031.
This report is Segmented by Vehicle Type (All-Terrain Vehicles and More), Application (Sports & Recreation and More), Propulsion Type (Internal-Combustion and More), Engine Displacement (Less Than 400 Cc and More), Power Output (Less Than 50 KW and More), Drive Type (2-Wheel Drive and More), Seating Capacity, and Geography. The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
Global Off-road Vehicle Market Trends and Insights
Surge In Outdoor Recreational Tourism
Outdoor recreation contributed USD 1.2 trillion to U.S. GDP in 2024, equal to 2.3% of national output and supporting multiple jobs. Participation increased, spurring ATV and UTV purchases for trail riding and overlanding. In 2024, motorcycling and ATVing generated a large share of value-added economic output, underscoring strong demand in the off-road vehicle market. State grant programs amplify the effect: Colorado's Outdoor Recreation Fund distributed a massive amount to access projects, while Oregon's matching grants nurtured rural manufacturing clusters. Trail systems create powerful spillovers; Minnesota's snowmobile network generates significant annual tourism revenue, reinforcing the sector's multiplier effect on local economies and stabilizing seasonal vehicle sales.
Tactical ATV/UTV Procurement By Defense Forces
Defense agencies seek light mobility assets for border patrol, special operations, and logistics in difficult terrain. India's upcoming northern-border tender specifies helicopter-sling capability, four-seat layouts, and autonomous navigation options to maximize tactical flexibility. Europe's FAMOUS program, coordinated by Finland, focuses on Arctic operability with vehicles tolerating -46 °C start-up and amphibious functionality for thaw periods. The United States allocates some amount annually to acquire Ultra-Light Combat Vehicles with 4,500-pound curb-weight caps and 250-mile range requirements. Such multi-program momentum encourages vendors to develop modular chassis that accept armor kits, counter-drone sensors, and hybrid powertrains, strengthening order backlogs despite civilian cyclical swings.
Lithium Supply-Chain Crunch For E-Powertrains
China currently refines more than three-fifths of global lithium and fabricates four-fifths of batteries, creating exposure for global OEMs as demand surges. The United States allocated funding under the Inflation Reduction Act for domestic processing, but permitting hurdles and community concerns are delaying mine openings. Electro-chemical extraction startups promise lower-impact solutions yet remain pre-commercial. Until diversified supply materializes, battery prices may remain volatile, constraining the total-cost parity that accelerates electric ATV adoption, particularly in price-sensitive developing markets.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Mechanization Of Midsize Farms
- Adoption Of Advanced EPS & Telematics
- Rising Injury-Related Regulations & Speed Caps
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
UTVs and side-by-sides captured 50.68% of the off-road vehicle market share in 2025 by blending passenger capacity, cargo utility, and suspension sophistication. The segment reached a robust level of off-road vehicle market size, buoyed by recreation, agriculture, and defense orders. Electric UTV derivatives now post the fastest 8.32% CAGR as OEMs introduce 15 kWh battery packs delivering 80 km/h top speed and sub-3-hour recharge cycles.
Demand for all-terrain vehicles (ATVs) remains robust in regions with strict width restrictions that favor narrower chassis. In contrast, niche demand for amphibious and snowmobile platforms persists where climatic extremes prevail. Competitive differentiation hinges on adjustable suspension, Polaris's DYNAMIX live valve architecture, and cabin digitization through touchscreen ride-command systems. The vehicle-type portfolio, therefore, balances legacy ICE volumes against emerging electric growth vectors, enabling OEMs to hedge against propulsion uncertainty.
Sports and recreation account for 41.05% of the off-road vehicle market in 2025, benefiting from record trail participation as millions of Americans venture outdoors. Military and law enforcement demand will escalate at an 8.35% CAGR as procurement agencies seek light tactical mobility with helicopter-sling compatibility and hybrid silent-watch modes.
Agriculture and forestry absorb mid-displacement UTVs outfitted with PTO-driven implements, while construction firms requisition high-payload units for remote-site logistics. Emerging tourism concepts such as guided overlanding expeditions further widen commercial use cases. Multi-role adaptability, therefore, sustains baseline volumes even when consumer discretionary spending dips.
Internal-combustion engines commanded 83.05% of the off-road vehicle market share in 2025, backed by ubiquitous fueling infrastructure and mature supply chains. Battery-electric models, however, record the steepest 8.30% CAGR, reflecting policy push and falling cell costs.
Hybrid range-extender concepts bridge customer anxiety by pairing 10 kWh packs with compact generators, extending runtime without compromising low-speed torque. Hydrogen fuel-cell prototypes remain R&D efforts but signal pathways for heavy-duty rescue fleets requiring rapid cold-weather refueling. Propulsion diversification mitigates regulatory risks while inviting new supplier ecosystems around battery leasing and recycling.
Complete Report Scope:
- By Vehicle Type
- All-Terrain Vehicles (ATV)
- Utility Task Vehicles (UTV) / Side-by-Sides
- Dirt / Off-road Motorcycles
- Snowmobiles
- Amphibious & Specialty ORVs
- By Application
- Sports & Recreation
- Agriculture & Forestry
- Industrial & Construction
- Military & Law-Enforcement
- Other Commercial (tourism, search-and-rescue)
- By Propulsion Type
- Internal-Combustion (Gasoline / Diesel)
- Hybrid
- Battery-Electric
- Hydrogen Fuel-Cell
- By Engine Displacement (cc)
- Less than 400 cc
- 400 - 800 cc
- More than 800 cc
- By Power Output (kW)
- Less than 50 kW
- 50 - 100 kW
- More than 100 kW
- By Drive Type
- 2-Wheel Drive
- 4-Wheel / All-Wheel Drive
- By Seating Capacity
- 1 Rider
- 2 Riders
- More than or equal to 3 Passengers
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- Turkey
- Egypt
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
North America secured 37.84% of off-road vehicle market share in 2025, underpinned by the outdoor recreation GDP contribution and extensive trail networks subsidized by state grants. Snowbelt states invested huge amount annually in grooming programs that stimulated in tourism receipts, while Wisconsin and Alaska reimbursed 100% of eligible trail maintenance costs, anchoring steady demand even during economic slowdowns. Dealer financing partnerships, such as Sheffield Financial's renewal with Polaris, ease credit access for buyers and sustain showroom turnover. Nevertheless, conservation-area restrictions across Canadian provinces introduce operational complexity, nudging OEMs to supply quieter powertrains and emission-compliant engines to satisfy permitting criteria.
Asia-Pacific delivers the fastest 8.42% CAGR through 2031 as urbanizing middle-class consumers embrace outdoor lifestyle brands and governments fund rural connectivity. India's ATV sales grew drastically which was supported by adventure-tourism marketing and agricultural mechanization drives. Regional OEMs such as CFMOTO leverage vertically integrated supply chains to offer competitive pricing, enabling them to capture export contracts and reach two-fifth global market share.
Europe's growth lags but regulatory thrust aligns with electrification imperatives. Stage V emission norms for non-road machinery elevate R&D spending on after-treatment and alternative powertrains, indirectly spurring innovation in hybrid and fuel-cell concepts. New NRMM rules effective 2028 set small-series thresholds of 70 units, granting boutique electric startups manageable certification pathways. Nordic countries deploy long-run trail-maintenance subsidies to catalyze tourism, a template that Germany and Austria now evaluate for alpine regions. Consequently, although compliance burdens restrain short-term volumes, long-term demand will pivot toward low-emission models, allowing European suppliers to recoup investments through premium pricing.
- Polaris Inc.
- Bombardier Recreational Products Inc. (Can-Am)
- Yamaha Motor Corp.
- Textron Inc. (Arctic Cat)
- Kawasaki Heavy Industries Ltd.
- Suzuki Motor Corp.
- Honda Motor Co. Ltd.
- CFMOTO Powersports Inc.
- Kwang Yang Motor Co. Ltd. (Kymco)
- American LandMaster
- Tracker Off-Road (Bass Pro Shops)
- Kubota Corp. (RTV)
- John Deere (Gator)
- Mahindra & Mahindra Ltd.
- Segway Powersports
- Hisun Motors Corp.
- Linhai Group
- TGB (Taiwan Golden Bee)
- DRR USA
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge In Outdoor Recreational Tourism
- 4.2.2 Tactical ATV/UTV Procurement By Defense Forces
- 4.2.3 Rapid Mechanization Of Midsize Farms
- 4.2.4 Adoption Of Advanced EPS & Telematics
- 4.2.5 Demand For Low-Noise E-Atvs For Drone Cinematography
- 4.2.6 Nordic Trail-Maintenance Subsidies Expanding Riding Networks
- 4.3 Market Restraints
- 4.3.1 High Upfront & Lifecycle Costs
- 4.3.2 Lithium Supply-Chain Crunch For E-Powertrains
- 4.3.3 Rising Injury-Related Regulations & Speed Caps
- 4.3.4 Conservation-Area Usage Bans
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Vehicle Type
- 5.1.1 All-Terrain Vehicles (ATV)
- 5.1.2 Utility Task Vehicles (UTV) / Side-by-Sides
- 5.1.3 Dirt / Off-road Motorcycles
- 5.1.4 Snowmobiles
- 5.1.5 Amphibious & Specialty ORVs
- 5.2 By Application
- 5.2.1 Sports & Recreation
- 5.2.2 Agriculture & Forestry
- 5.2.3 Industrial & Construction
- 5.2.4 Military & Law-Enforcement
- 5.2.5 Other Commercial (tourism, search-and-rescue)
- 5.3 By Propulsion Type
- 5.3.1 Internal-Combustion (Gasoline / Diesel)
- 5.3.2 Hybrid
- 5.3.3 Battery-Electric
- 5.3.4 Hydrogen Fuel-Cell
- 5.4 By Engine Displacement (cc)
- 5.4.1 Less than 400 cc
- 5.4.2 400 - 800 cc
- 5.4.3 More than 800 cc
- 5.5 By Power Output (kW)
- 5.5.1 Less than 50 kW
- 5.5.2 50 - 100 kW
- 5.5.3 More than 100 kW
- 5.6 By Drive Type
- 5.6.1 2-Wheel Drive
- 5.6.2 4-Wheel / All-Wheel Drive
- 5.7 By Seating Capacity
- 5.7.1 1 Rider
- 5.7.2 2 Riders
- 5.7.3 More than or equal to 3 Passengers
- 5.8 By Geography
- 5.8.1 North America
- 5.8.1.1 United States
- 5.8.1.2 Canada
- 5.8.1.3 Rest of North America
- 5.8.2 South America
- 5.8.2.1 Brazil
- 5.8.2.2 Argentina
- 5.8.2.3 Rest of South America
- 5.8.3 Europe
- 5.8.3.1 Germany
- 5.8.3.2 France
- 5.8.3.3 United Kingdom
- 5.8.3.4 Italy
- 5.8.3.5 Spain
- 5.8.3.6 Russia
- 5.8.3.7 Rest of Europe
- 5.8.4 Asia-Pacific
- 5.8.4.1 China
- 5.8.4.2 Japan
- 5.8.4.3 India
- 5.8.4.4 South Korea
- 5.8.4.5 Australia
- 5.8.4.6 Rest of Asia-Pacific
- 5.8.5 Middle East and Africa
- 5.8.5.1 United Arab Emirates
- 5.8.5.2 Saudi Arabia
- 5.8.5.3 Turkey
- 5.8.5.4 Egypt
- 5.8.5.5 South Africa
- 5.8.5.6 Rest of Middle East and Africa
- 5.8.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Polaris Inc.
- 6.4.2 Bombardier Recreational Products Inc. (Can-Am)
- 6.4.3 Yamaha Motor Corp.
- 6.4.4 Textron Inc. (Arctic Cat)
- 6.4.5 Kawasaki Heavy Industries Ltd.
- 6.4.6 Suzuki Motor Corp.
- 6.4.7 Honda Motor Co. Ltd.
- 6.4.8 CFMOTO Powersports Inc.
- 6.4.9 Kwang Yang Motor Co. Ltd. (Kymco)
- 6.4.10 American LandMaster
- 6.4.11 Tracker Off-Road (Bass Pro Shops)
- 6.4.12 Kubota Corp. (RTV)
- 6.4.13 John Deere (Gator)
- 6.4.14 Mahindra & Mahindra Ltd.
- 6.4.15 Segway Powersports
- 6.4.16 Hisun Motors Corp.
- 6.4.17 Linhai Group
- 6.4.18 TGB (Taiwan Golden Bee)
- 6.4.19 DRR USA
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

 越野車市場:按車輛類型、產品類型、應用和地區分類
 非公路用車輛照明市場-2026-2032年全球市場預測
 全球越野車市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 2026年全球休閒越野車市場報告2026年全球越野車市場報告2026年全球非公路用車輛照明市場報告
 全球非公路用塑膠市場:依材料類型、製程類型、最終用戶和地區分類-預測(至2030年)
 日本越野車市場規模、佔有率、趨勢和預測:按產品、地區分類,2026-2034年非公路用電氣設備市場按產品類型、推進類型、功率輸出、應用和分銷管道分類 - 全球預測(2026-2032 年)
 越野車市場-全球產業規模、佔有率、趨勢、機會及預測(按車輛類型(全地形車和多用途車)、應用類型、地區和競爭格局分類,2021-2031年預測)