


 |
市場調查報告書
商品編碼
2122619
環境感測器:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Environmental Sensors - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
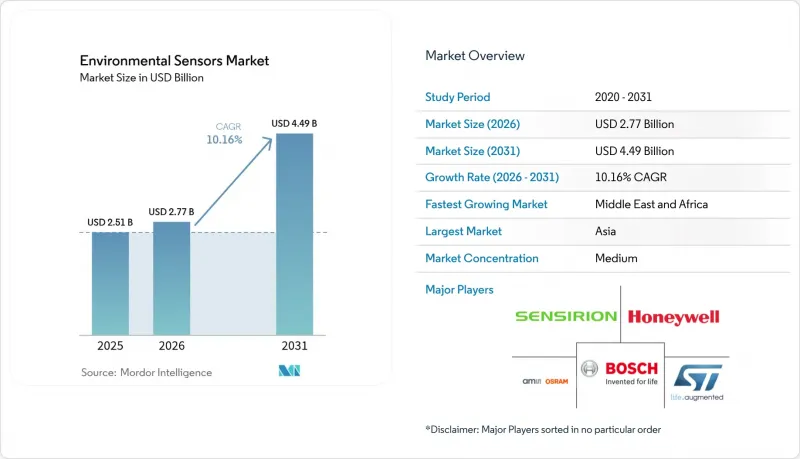
根據 Mordor Intelligence 估計,環境感測器市場在 2026 年的價值為 27.7 億美元,高於 2025 年的 25.1 億美元,預計到 2031 年將達到 44.9 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 10.16%。
本報告按產品類型(固定式、可攜式、穿戴式式)、檢測類型(氣體、溫度、濕度、壓力、顆粒物 (PM)、多參數模組)、連接方式(有線、無線)、終端用戶行業(工業、醫療保健、家用電子電器、汽車)和地區進行細分。市場預測以美元 (USD) 為單位。
全球環境感測器市場趨勢與洞察
NB-IoT部署的擴展正在推動高密度都市區感測器網路的實現(亞洲)。
中國電信業者目前營運超過9億個NB-IoT連接,並計畫在2030年將連接數擴展至19億。深圳等城市正在鋪設街區級空氣品質測繪基礎設施。這種低功耗廣域通訊標準擁有長達10年的電池壽命、極強的室內訊號穿透力以及透過授權頻寬實現的可靠性,使地方政府高層建築區域。從泰國到阿拉伯聯合大公國等鄰國也正在藉鏡此模式,加速智慧城市建設並推動ESG合規。
歐盟空氣品質指令 2023/2119 加強了標準
2025年3月發布的指令將PM2.5的年均限值從25微克/立方米降至10微克/立方米,並強制要求監測超細顆粒物,迫使成員國用高密度感測器叢集來補充昂貴的參考站。即時公共數據存取機制優先考慮將測量數據流傳輸到中央控制面板的物聯網模組,同時,對能夠在都市區霧霾環境中達到±5微克/立方米精度的校準型微機電系統(MEMS)單元的需求也日益成長。
惡劣戶外環境下的校準漂移和維護成本
安裝在戶外環境中的電化學感測器會因溫度波動、濕度變化和氣體干擾而出現顯著的校準漂移。因此,為了保持可接受的精度,需要每三個月進行一次重新校準。這種維護負擔會產生大量的運行成本,尤其是在惡劣氣候條件下,環境壓力會加速感測器的劣化,其成本甚至可能在部署的第一年就超過感測器的初始採購成本。研究表明,超過90%的感測器在定期檢查中仍保持在校準規格範圍內,這表明目前的維護計劃過於保守,而違規會造成巨大的成本,因此定期檢查至關重要。
細分市場分析
到2025年,固定式環境感測器將佔市場佔有率的61.30%,這反映出工廠營運商需要證明其持續符合監管要求。這些壁掛式或管道插入式探頭將為環境管理系統提供全天候數據,而審計人員正是依靠這些數據進行範圍1檢驗。攜帶式設備雖然目前市佔率仍然較小,但預計到2031年將以12.31%的複合年成長率成長。這主要是由於緊急應變人員、礦業公司和建築聯合體越來越重視在行動作業現場快速部署設備。美國國防安全保障部開展的野火響應試點計畫證明了行動網路的商業價值,該計畫表明,拖車式PM節點能夠比衛星影像提前30分鐘提供資訊。
可攜式設備正日益成為固定陣列的補充,而非替代品。例如,公共產業為了符合監管要求而安裝有線二氧化硫測量設備,並在停電期間使用電池供電的揮發性有機化合物(VOC)檢測器進行維護。穿戴式裝置仍處於早期發展階段,但對於消費性電子製造商而言,它們提供了一種差異化競爭的方式,例如將花粉計數和污染警報整合到健身儀錶板中,從而強調健康。在整個預測期內,結合永久基準和可移動叢集的混合架構將重新定義整個環境感測器市場的採購指南。
氣體分析儀(用於檢測工廠、隧道和鍋爐中的一氧化碳、氮氧化物和揮發性有機化合物)預計到2025年將佔據環境感測器市場25.60%的佔有率,這主要得益於成熟的電化學電池和非分散紅外線(NDIR)光學技術。同時,隨著公共衛生機構收緊PM2.5暴露閾值,顆粒物分析儀預計將以12.95%的複合年成長率成長。受歐盟和加州將PM2.5年均濃度限值設定為10微克/立方公尺的法規推動,PM測量儀器的環境感測器市場規模預計到2031年將達到11.6億美元。
溫度、濕度和壓力感測器仍然是普遍存在的環境監測參數,通常與關鍵氣體和顆粒物監測功能整合在多參數模組中。 BoschSensortec的BME688整合了四個實體感測器和板載AI推理功能,可為先前單獨購買組件的OEM廠商降低20%的組件成本。這種整合模糊了傳統的產品類別界限,鼓勵廠商購買綜合性的“環境監測軟體包”,而不是單一參數的組件。
區域分析
到2025年,亞太地區將佔全球銷售額的37.60%,成為環境感測器市場的主要驅動力。這主要得益於中國和印度的大型智慧大型企劃,這些項目正在將NB-IoT節點整合到路燈、公車和學校等設施中。光是深圳就經營超過37,000個空氣品質監測箱,並將資料上傳至開放資料入口網站。強大的電子供應鏈有效降低了零件成本,使得市政當局能夠以不到15,000美元的成本部署覆蓋一平方公里的網路。日本和韓國的半導體工廠正在投資先進的MEMS生產能力,而澳洲各州則在投資顆粒物(PM)和煙霧偵測陣列,以應對野火。
北美市場規模位居第二。由於美國證券交易委員會(SEC)的氣候變遷資訊揭露要求以及加州、奧勒岡州和不列顛哥倫比亞省的野火救災資金,該地區的環境感測器市場正蓬勃發展。雲端邊緣整合也日趨活躍,Honeywell和亞德諾半導體(Analog Devices)於2024年達成合作,使建築自動化閘道器能夠直接連接到Azure IoT中心,從而將整合時間縮短一半。根據《晶片和科學法案》(CHIPS and Science Act)提供的聯邦津貼正在加速具有網路彈性的感測器韌體的研發。
歐洲仍然是一個至關重要的市場,針對PM2.5和超細懸浮微粒的更嚴格法規正在推動400多個城市進行感測器升級。在德國,環境遙測技術正與工業4.0數位孿生技術結合;北歐的公共產業正在區域供熱地下室安裝露點測量陣列,以控制因冷凝造成的能源損失。在「地平線歐洲」計畫下,歐盟資金目前補貼高達75%的空氣品質監測網路成本,從而縮短了實施前置作業時間。
中東和非洲目前市佔率僅為個位數,但複合年成長率高達13.65%。海灣產油國正在部署連續洩漏檢測系統,為發行環境、社會和治理(ESG)掛鉤債券做準備;南非採礦業正在試點建設低成本的顆粒物(PM)測量網路,以加強職業安全審計。儘管校準實驗室短缺仍然是一個挑戰,但預計在2026年至2027年間由捐助者資助的參考站將在內羅畢、阿克拉和拉各斯等城市帶來大量訂單。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- NB-IoT部署的擴展正在推動高密度都市區感測器網路的實現(亞洲)。
- 歐盟空氣品質指令 2023/2119 的更嚴格標準
- 強制揭露與環境、社會和治理 (ESG) 相關的工業排放(美國證券交易委員會、公司及社會責任條例)
- 在穿戴式和可聽設備中採用多參數感測器模組
- 建造一座需要濕度和氣體感測器的綠色氫氣和電池超級工廠。
- 利用分散式PM感測器的北美野火早期預警網路
- 市場限制因素
- 惡劣戶外環境下的校準漂移和維護成本
- 新興國家缺乏標準級校準基礎設施
- 圍繞雲端連接工業感測器的網路安全和智慧財產權問題
- 由於MEMS元件商品化,價格下降。
- 價值供應鏈分析
- 監管和技術展望
- 波特五力分析
第5章 市場規模與成長預測
- 依產品類型
- 固定的
- 可攜式的
- 穿戴式裝置
- 檢測方法
- 氣體
- 溫度
- 濕度
- 壓力
- 顆粒物(PM)
- 多參數模組
- 連結性別
- 有線
- 無線的
- 按最終用戶行業分類
- 產業
- 醫療保健
- 家用電子產品
- 車
- 智慧家庭與智慧建築
- 農業
- 其他最終用戶
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 英國
- 德國
- 法國
- 義大利
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 其他亞太國家
- 中東
- 以色列
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 埃及
- 其他非洲國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- ams OSRAM AG
- Sensirion Holding AG
- Bosch Sensortec GmbH
- Honeywell International Inc.
- Texas Instruments Inc.
- Analog Devices Inc.
- STMicroelectronics NV
- NXP Semiconductors NV
- TDK Corporation(InvenSense)
- Omron Corporation
- Sensata Technologies Inc.
- AlphaSense Inc.
- Figaro Engineering Inc.
- Banner Engineering Corp.
- Renesas Electronics Corp.
- Teledyne FLIR LLC
- Hanwei Electronics Group Corp.
- Powelectrics Ltd.
- Eurotech SpA
- Omega Engineering Inc.
- Nesa Srl
- Eko Instruments BV
第7章 市場機會與未來展望
According to Mordor Intelligence, environmental sensors market size in 2026 is estimated at USD 2.77 billion, growing from 2025 value of USD 2.51 billion with 2031 projections showing USD 4.49 billion, growing at 10.16% CAGR over 2026-2031.
This report is Segmented by Product Type (Fixed, Portable, Wearable), Sensing Type (Gas, Temperature, Humidity, Pressure, Particulate Matter (PM), Multi-Parameter Modules), Connectivity (Wired, Wireless), End-User Industry (Industrial, Medical and Healthcare, Consumer Electronics, Automotive), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Environmental Sensors Market Trends and Insights
Increased NB-IoT Deployments Enabling Dense Urban Sensor Networks (Asia)
Chinese operators now run more than 900 million NB-IoT connections, and expansion plans aim for 1.9 billion by 2030, giving cities like Shenzhen the backbone for block-level air-quality mapping. The low-power wide-area standard supports decade-long battery life, deep-indoor penetration, and licensed-spectrum reliability, letting municipalities blanket high-rise districts without trenching cables. Neighboring economies from Thailand to the UAE mirror this model to accelerate smart-city roll-outs and ESG compliance.
Tightening EU Ambient Air-Quality Directive 2023/2119 Standards
The March 2025 directive slices the annual PM2.5 limit from 25 µg/m3 to 10 µg/m3 and mandates ultrafine particle tracking, forcing member states to supplement costly reference stations with dense sensor clusters. Real-time public-data access clauses privilege IoT-ready modules that stream measurements to central dashboards, spurring demand for calibrated MEMS units capable of +-5 µg/m3 accuracy in urban smog.
Calibration Drift & Maintenance Costs in Harsh Outdoor Environments
Electrochemical sensors deployed in outdoor environments experience significant calibration drift due to temperature fluctuations, humidity variations, and exposure to interfering gases, requiring recalibration intervals as frequent as every 3 months to maintain acceptable accuracy. This maintenance burden creates substantial operational costs that can exceed initial sensor procurement costs within the first year of deployment, particularly in harsh climates where environmental stressors accelerate sensor degradation. Research indicates that over 90% of sensors remain within calibration specifications during routine checks, suggesting that current maintenance schedules are overly conservative but necessary due to the high cost of compliance failures.
Other drivers and restraints analyzed in the detailed report include:
- ESG-Linked Industrial Emissions Disclosure Mandates (SEC, CSRD)
- Adoption of Multi-parameter Sensor Modules in Wearables & Hearables
- Limited Reference-Grade Calibration Infrastructure in Emerging Economies
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Fixed installations dominated the environmental sensors market size with 61.30% revenue in 2025, reflecting plant operators' need for uninterrupted proof of regulatory conformity. These wall-mounted or duct-inserted probes feed 24/7 data to environmental management systems that auditors rely on for Scope 1 verification. Portable devices, although smaller in volume, are pacing a 12.31% CAGR through 2031 as first-responders, mining firms, and construction consortia favor rapid deployment along shifting work sites. The Department of Homeland Security's wildfire pilot showed that trailer-mounted PM nodes delivered 30-minute lead times over satellite imagery, validating the business case for mobile grids.
Portables increasingly complement-not replace-fixed arrays. Utilities, for instance, install hard-wired SO2 stacks for compliance, then wheel battery-powered VOC sniffers during maintenance outages. Wearable units remain nascent but give consumer OEMs a route to health-centric differentiation, bundling pollen counts or pollution alerts into fitness dashboards. Over the forecast cycle, hybrid architectures blending permanent baselines with redeployable clusters will redefine procurement guidelines across the environmental sensors market.
Gas analyzers captured 25.60% of environmental sensors market share in 2025 thanks to mature electrochemical cells and NDIR optics that detect CO, NOx, and volatile organic compounds in factories, tunnels, and boilers. Particulate-matter devices, however, are charting a 12.95% CAGR as public-health agencies tighten PM2.5 exposure thresholds. Environmental sensors market size for PM instruments is forecast to reach USD 1.16 billion by 2031, buoyed by EU and California mandates demanding 10 µg/m3 annual averages.
Temperature, humidity, and pressure chips remain ubiquitous housekeeping parameters, often bundled with primary gas or PM functions inside multi-parameter modules. Bosch Sensortec's BME688 unites four physical sensors plus on-board AI inference, slicing bill-of-materials cost by 20% for OEMs that previously bought discrete components. Convergence blurs historical category lines, steering purchasing toward holistic "environment packs" rather than single-parameter parts.
Complete Report Scope:
- By Product Type
- Fixed
- Portable
- Wearable
- By Sensing Type
- Gas
- Temperature
- Humidity
- Pressure
- Particulate Matter (PM)
- Multi-parameter Modules
- By Connectivity
- Wired
- Wireless
- By End-User Industry
- Industrial
- Medical and Healthcare
- Consumer Electronics
- Automotive
- Smart Homes and Buildings
- Agriculture
- Other End-Users
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- Middle East
- Israel
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
Asia-Pacific led the environmental sensors market with 37.60% revenue in 2025, powered by smart-city mega-projects in China and India that embed NB-IoT nodes in streetlights, buses, and schools. Shenzhen alone operates more than 37,000 air-quality boxes feeding open data portals. Strong electronics supply chains lower bill-of-materials, letting municipalities deploy square-kilometer grids for less than USD 15,000. Japanese and South Korean fabs inject advanced MEMS capacity, while Australian states invest in PM-and-smoke arrays for bushfire response.
North America ranks second by value. The environmental sensors market here gains momentum from SEC climate disclosure obligations and wildfire-defense funding across California, Oregon, and British Columbia. Cloud-edge alliances flourish: Honeywell's 2024 pact with Analog Devices links building-automation gateways directly to Azure IoT hubs, cutting integration times by half. Federal grants under the CHIPS and Science Act funnel R&D toward cyber-resilient sensor firmware.
Europe remains pivotal; tightened PM2.5 and ultrafine norms drive sensor retrofits across 400+ cities. Germany ties environmental telemetry to Industry 4.0 digital twins, while Nordic utilities install dew-point arrays inside district-heating vaults to manage condensation energy losses. Implementation lead times shorten because EU funds now reimburse up to 75% of air-quality network costs under Horizon Europe.
The Middle East and Africa presently represent a single-digit share but exhibit 13.65% CAGR. Gulf petro-states adopt continuous-leak detection for ESG-linked bond issuance, and South Africa's mining sector pilots low-cost PM nets to bolster labor-safety audits. Scarce calibration labs remain a hurdle, but donor-funded reference stations scheduled for 2026-2027 will unlock volume orders across Nairobi, Accra, and Lagos.
- ams OSRAM AG
- Sensirion Holding AG
- Bosch Sensortec GmbH
- Honeywell International Inc.
- Texas Instruments Inc.
- Analog Devices Inc.
- STMicroelectronics N.V.
- NXP Semiconductors N.V.
- TDK Corporation (InvenSense)
- Omron Corporation
- Sensata Technologies Inc.
- AlphaSense Inc.
- Figaro Engineering Inc.
- Banner Engineering Corp.
- Renesas Electronics Corp.
- Teledyne FLIR LLC
- Hanwei Electronics Group Corp.
- Powelectrics Ltd.
- Eurotech S.p.A.
- Omega Engineering Inc.
- Nesa Srl
- Eko Instruments B.V.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increased NB-IoT Deployments Enabling Dense Urban Sensor Networks (Asia)
- 4.2.2 Tightening EU Ambient Air-Quality Directive 2023/2119 Standards
- 4.2.3 ESG-Linked Industrial Emissions Disclosure Mandates (SEC, CSRD)
- 4.2.4 Adoption of Multi-parameter Sensor Modules in Wearables and Hearables
- 4.2.5 Green-Hydrogen and Battery Gigafactory Build-outs Requiring Humidity/Gas Sensors
- 4.2.6 Wild-fire Early-Warning Networks in North America Using Distributed PM Sensors
- 4.3 Market Restraints
- 4.3.1 Calibration Drift and Maintenance Costs in Harsh Outdoor Environments
- 4.3.2 Limited Reference-Grade Calibration Infrastructure in Emerging Economies
- 4.3.3 Cyber-security and IP Concerns Around Cloud-Connected Industrial Sensors
- 4.3.4 Price Erosion from Commoditization of MEMS Components
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory and Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Consumers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Fixed
- 5.1.2 Portable
- 5.1.3 Wearable
- 5.2 By Sensing Type
- 5.2.1 Gas
- 5.2.2 Temperature
- 5.2.3 Humidity
- 5.2.4 Pressure
- 5.2.5 Particulate Matter (PM)
- 5.2.6 Multi-parameter Modules
- 5.3 By Connectivity
- 5.3.1 Wired
- 5.3.2 Wireless
- 5.4 By End-User Industry
- 5.4.1 Industrial
- 5.4.2 Medical and Healthcare
- 5.4.3 Consumer Electronics
- 5.4.4 Automotive
- 5.4.5 Smart Homes and Buildings
- 5.4.6 Agriculture
- 5.4.7 Other End-Users
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 United Kingdom
- 5.5.2.2 Germany
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Rest of Asia-Pacific
- 5.5.4 Middle East
- 5.5.4.1 Israel
- 5.5.4.2 Saudi Arabia
- 5.5.4.3 United Arab Emirates
- 5.5.4.4 Turkey
- 5.5.4.5 Rest of Middle East
- 5.5.5 Africa
- 5.5.5.1 South Africa
- 5.5.5.2 Egypt
- 5.5.5.3 Rest of Africa
- 5.5.6 South America
- 5.5.6.1 Brazil
- 5.5.6.2 Argentina
- 5.5.6.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 ams OSRAM AG
- 6.4.2 Sensirion Holding AG
- 6.4.3 Bosch Sensortec GmbH
- 6.4.4 Honeywell International Inc.
- 6.4.5 Texas Instruments Inc.
- 6.4.6 Analog Devices Inc.
- 6.4.7 STMicroelectronics N.V.
- 6.4.8 NXP Semiconductors N.V.
- 6.4.9 TDK Corporation (InvenSense)
- 6.4.10 Omron Corporation
- 6.4.11 Sensata Technologies Inc.
- 6.4.12 AlphaSense Inc.
- 6.4.13 Figaro Engineering Inc.
- 6.4.14 Banner Engineering Corp.
- 6.4.15 Renesas Electronics Corp.
- 6.4.16 Teledyne FLIR LLC
- 6.4.17 Hanwei Electronics Group Corp.
- 6.4.18 Powelectrics Ltd.
- 6.4.19 Eurotech S.p.A.
- 6.4.20 Omega Engineering Inc.
- 6.4.21 Nesa Srl
- 6.4.22 Eko Instruments B.V.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 2026年全球監測感測器市場報告
 藍菌感測器市場:全球市場預測,2026-2032年管道溫濕度感測器市場:全球市場預測,2026-2032年
 高精度無線雨量計市場規模、佔有率和成長分析:按雨量計類型、無線技術、應用、最終用戶和地區分類 - 產業預測,2026-2033年5G無線溫度與振動感測器市場:全球市場預測,2026-2032年智慧無線溫度與振動整合感測器市場:全球市場預測,2026-2032年
 二氧化碳資料記錄器市場規模、佔有率和成長分析:按產品類型、連接方式、應用、最終用戶和地區分類-2026-2033年產業預測
 游泳池水質感測器市場報告:趨勢、預測和競爭分析(至2035年)
 紫外線資料記錄器市場規模、佔有率和成長分析:按產品類型、連接方式、應用、最終用戶、分銷管道和地區分類-2026-2033年產業預測
 降水感測器市場規模、佔有率和成長分析:按感測器類型、應用、安裝類型、最終用戶、輸出格式和地區分類-2026-2033年產業預測