


 |
市場調查報告書
商品編碼
2122521
標記化解決方案:市場佔有率分析、行業趨勢和統計數據、成長預測(2026-2031 年)Tokenization Solution - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,標記化解決方案市場規模將從 2025 年的 43.7 億美元成長到 2026 年的 52.3 億美元,然後在 2031 年達到 127.8 億美元,2026 年至 2031 年的複合年成長率為 19.57%。
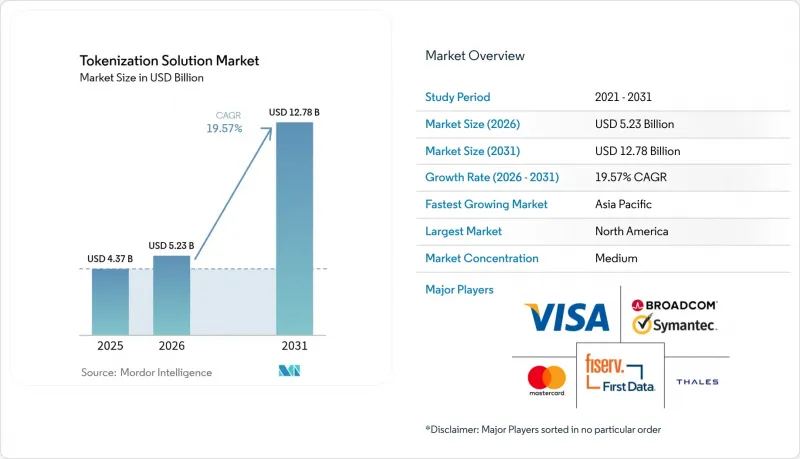
本報告按組件(解決方案、服務)、部署模式(本地部署、雲端部署)、標記化方法(金庫標記化等)、應用領域(支付安全、客戶認證等)、最終用戶行業(銀行、金融服務和保險、零售/電子商務等)以及地區進行細分。市場預測以美元計價。
全球標記化解決方案市場趨勢與洞察
亞洲非接觸式和行動錢包支付中代幣化應用程式激增
2024年初,亞太地區的行動支付交易量年增超過一倍,代幣化正逐漸成為該地區付款基礎的核心組成部分。日本計劃在2025年前建成覆蓋全國200萬家門市的東協聯合2D碼網路,這清楚地表明了目前錢包間的互通性在很大程度上依賴於網路代幣。預計到2029年,中國的行動支付交易額將超過1,100兆元人民幣,而代幣化憑證正是保護其超級應用生態系統的重要保障。日本2024年的無現金支付率預計將超過39.3%,區域政策目標要求商家推廣代幣化,以此作為獲得補貼的先決條件。這種網路效應正迫使全球支付處理商加強在亞洲的夥伴關係,以維持既定的交易量目標。
強制執行 PCI DSS 4.0 標準的最後期限正在推動北美地區對代幣化的投資。
PCI DSS 4.0 強化了對持卡人資料處理的義務,使得令牌化成為縮小審計範圍和降低審計成本的最快途徑。對高度敏感欄位進行令牌化的公司可以減少需要接受年度評估的系統數量,從而將安全預算重新分配到主動威脅搜尋和零信任計畫中。新標準中的持續監控條款與現代令牌化平台內建的即時分析功能相契合,使董事會能夠根據需要提供合規性證據。基於雲端的代幣化服務進一步縮短了部署時間,加快了全通路零售商和金融科技發卡機構實現價值的速度。
專有令牌服務供應商之間的互通性差距
不同的代幣格式和專有API阻礙了多軌支付的普及,增加了整合成本和供應商鎖定風險。政府機構被要求實現供應商多元化,卻往往被迫並行維護多個代幣基礎設施,不僅加重了資本支出,也使管治更加複雜。缺乏通用的代幣交換協議也阻礙了跨境貿易,因為方案不匹配需要複雜的轉換閘道器和高昂的處理費用。
細分市場分析
到2025年,解決方案將佔總收入的71.35%,這表明平台軟體在標記化解決方案市場中扮演著基礎性角色。專業服務服務和託管服務預計將以20.35%的複合年成長率成長,這主要受內部專業知識匱乏和持續合規義務的推動,促使企業選擇外包。企業正在利用諮詢合約來了解資料流並降低PCI風險,然後再轉向持續的服務合約進行代幣維護。 「代幣化即服務(ToA-S)」框架模糊了產品和服務之間的界限,降低了中型企業採用該技術的門檻。諸如Marqeta Docs AI之類的AI驅動的文件工具透過自動產生程式碼片段,進一步加速了這個採用過程。
對於尋求擴充性自身支付流程和混合本地部署的企業而言,解決方案領域仍然至關重要。功能藍圖擴大融入人工智慧 (AI) 分析,以視覺化令牌流中的詐欺模式,從而將被動控制轉變為主動決策引擎。將高度擴充性的API 與合規認證結合的供應商,更有能力贏得長期的企業客戶。
預計到2025年,雲端運算將佔總營收的63.10%,以20.65%的複合年成長率保持主導地位。這反映了雲端運算透過全球網路實現覆蓋範圍廣、彈性擴展的結構性優勢。與現有身分和存取管理 (IAM) 堆疊的整合,使安全團隊能夠統一執行策略,並加快稽核和漏洞回應。擴展邊緣運算減少了網路躍點,消除了曾經有利於本地部署的延遲差距。超大規模超大規模資料中心業者提供的後量子密碼學藍圖,透過降低未來演算法轉型帶來的風險,進一步增強了這項優勢。
在資料居住要求嚴格且依賴大型主機的產業中,本地部署仍然十分普遍。混合架構提供了一種折衷方案,它既能保持本地金鑰管理,又能根據季節性需求高峰將令牌化工作負載快速遷移到雲端。隨著零信任框架的日趨成熟,即使是較保守的產業也將開始卸載非核心工作負載,預計在預測期內,本地部署規模將持續縮小。
區域分析
北美地區憑藉早期雲端技術應用和完善的支付安全合規體系,預計到2025年將佔據標記化解決方案市場38.60%的收入佔有率。 PCI DSS 4.0的實施期限縮短了升級週期,促使許多後發企業遷移到託管代幣化服務。隨著主要信用卡領域的市場接近飽和,服務提供者正將重點轉向醫療保健支付和政府福利支付等相關應用情境。
亞太地區正以19.95%的複合年成長率推動市場成長,預計到2031年將持續成長,這主要得益於行動錢包的普及和公共部門數位化資金的投入。日本的東協2D碼計畫和支付寶+商家的擴張是跨國錢包利用網路代幣實現無貨幣支付的典型案例。中國的超級應用生態系統持續發展,催生了對能夠應對購物節高峰期的超高吞吐量代幣引擎的需求。印度的統一支付基礎設施為能夠根據當地Aadhaar身分標準進行客製化的代幣化服務提供者提供了一個充滿潛力的市場。
在歐洲,GDPR的實施正穩步推進,在應對其限制的同時,也注重強而有力的反詐欺獎勵。監管機構對集中式資料儲存持謹慎態度,傾向於採用無保險庫的實施方案,而各國數位身分計畫則為公民服務的代幣化創造了新的機會。儘管歐洲各地的監管碎片化問題依然複雜,但隨著方案層面協調工作的推進,技術壁壘正逐漸降低。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究的先決條件
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 在亞洲,非接觸式支付和行動錢包支付的代幣化技術正迅速普及。
- 強制性 PCI DSS 4.0 合規期限的臨近,正在推動北美地區對代幣化技術的投資。
- 非面對面交易中詐欺行為造成的損失日益增加,推動了歐洲對保險箱無風險代幣化的採用。
- 「先買後付」平台的擴充功能需要整合令牌化身分驗證資訊。
- 信用卡品牌推出的網路代幣化計畫正在加速商家註冊。
- 市場限制因素
- 專有令牌服務供應商之間的互通性差距
- 高頻交易公司對代幣庫架構高延遲的擔憂
- 中型醫療機構對非支付用例中的代幣化認知有限。
- 供應商鎖定風險限制了政府機構採用此方案。
- 價值供應鏈分析
- 監管和技術展望
- 監理情勢
- 技術創新(令牌化即服務、雲端 HSM)
- 波特五力分析
第5章 市場規模與成長預測
- 按組件
- 解決方案
- 服務
- 部署模式
- 現場
- 雲
- 標記化詞法
- Vault 型標記化
- 標記化
- 按應用程式字段
- 支付安全
- 客戶身份驗證
- 詐欺防制和風險管理
- 合規與審計管理
- 其他
- 按最終用戶行業分類
- BFSI
- 零售與電子商務
- 資訊科技/通訊
- 醫療保健和生命科學
- 運輸/物流
- 政府/公共部門
- 能源公用事業
- 媒體與娛樂
- 其他
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 歐洲
- 英國
- 德國
- 法國
- 北歐的
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- ASEAN
- 澳洲
- 紐西蘭
- 其他亞太國家
- 中東和非洲
- 中東
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 其他非洲國家
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略性措施與資金籌措
- 市佔率分析
- 公司簡介
- Thales Group
- Broadcom Inc.(Symantec Enterprise)
- Visa Inc.
- Mastercard Inc.
- Fiserv Inc.(First Data)
- Worldpay LLC(FIS)
- PayPal Holdings Inc.(Braintree)
- American Express Company
- Protegrity USA Inc.
- TokenEx LLC
- Entrust Corporation
- Rambus Inc.(Bell ID)
- Sequent Software Inc.
- CardConnect Corporation
- Bluefin Payment Systems
- Marqeta Inc.
- Adyen NV
第7章 市場機會與未來展望
According to Mordor Intelligence, the tokenization solution market size is expected to grow from USD 4.37 billion in 2025 to USD 5.23 billion in 2026 and is forecast to reach USD 12.78 billion by 2031 at 19.57% CAGR over 2026-2031.
This report is Segmented by Component (Solutions, Services), Deployment Mode (On-Premise, Cloud), Tokenization Technique (Vaulted Tokenization, and More), Application Area (Payment Security, Customer Authentication, and More), End-User Industry (BFSI, Retail and E-Commerce, and More), and by Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Tokenization Solution Market Trends and Insights
Surge in Tokenisation Adoption for Contactless & Mobile Wallet Payments in Asia
Mobile payment transactions in Asia Pacific more than doubled year-on-year in early 2024, drawing tokenisation into the region's core payments stack. Japan's plan for a joint ASEAN QR network by fiscal 2025, covering 2 million domestic merchants, showcases the scale at which cross-wallet interoperability now depends on network tokens. China's mobile payment throughput, projected above CNY 1,100 trillion by 2029, relies on tokenised credentials to secure super-app ecosystems. With Japan's cashless ratio topping 39.3% in 2024, regional policy targets drive merchants toward tokenisation as a precondition for subsidy eligibility. This network effect compels global processors to deepen Asian partnerships to retain addressable volume.
Mandatory PCI DSS 4.0 Compliance Deadlines Boosting Tokenisation Investments in North America
PCI DSS 4.0 elevates cardholder-data obligations, making tokenisation the quickest path to scope reduction and audit-cost containment. Enterprises that tokenise sensitive fields can quarantine fewer systems under annual assessment, freeing security budgets for proactive threat-hunting and zero-trust initiatives. Continuous-monitoring clauses in the new standard align with real-time analytics embedded in modern token platforms, allowing boards to evidence compliance on demand. Cloud-delivered tokenisation services further compress deployment timelines, accelerating time-to-value for omnichannel retailers and fintech issuers.
Interoperability Gaps Among Proprietary Token Service Providers
Disparate token formats and proprietary APIs hinder multi-rail payment acceptance, elevating integration cost and vendor-lock-in risk. Government agencies mandated to diversify suppliers must often maintain parallel token infrastructures, draining CapEx and complicating governance. Absence of a universal token exchange protocol also impedes cross-border commerce, where mismatched schemes require complex translation gateways that inflate processing fees.
Other drivers and restraints analyzed in the detailed report include:
- Rising Fraud Losses in Card-Not-Present Transactions Driving Vaultless Tokenisation Uptake in Europe
- Expansion of BNPL Platforms Demanding Tokenised Credentials Integration
- High Latency Concerns in Token Vault Architectures for High-Frequency Trading Firms
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Solutions accounted for 71.35% of 2025 revenue, testifying to the foundational role of platform software in the tokenization solution market. Professional and managed services are forecast to grow at a 20.35% CAGR, aided by scarce in-house expertise and continuous compliance obligations that favour outsourcing. Enterprises leverage advisory engagements to map data flows and reduce PCI exposure, then transition to ongoing service contracts for token maintenance. Tokenization-as-a-Service frameworks blur the boundary between product and service, lowering entry barriers for mid-market adopters. AI-enabled documentation tools, such as Marqeta Docs AI, further accelerate onboarding by automating code-snippet generation.
The solutions segment remains critical for enterprises demanding extensibility into proprietary payment flows or hybrid on-premise deployments. Feature roadmaps increasingly embed artificial-intelligence analytics that surface fraud patterns within the token stream, turning passive controls into active decision engines. Vendors that pair extensible APIs with compliance attestation are best placed to lock in long-cycle enterprise accounts.
Cloud held 63.10% of 2025 revenue and will sustain leadership with a 20.65% CAGR, reflecting the structural advantage of global point-of-presence coverage and elastic scaling. Integrations with existing identity-and-access-management stacks allow security teams to unify policy enforcement, speeding audits and breach preparation. Edge compute extensions reduce network hops, closing the latency gap that once favoured on-premise deployments. Post-quantum cryptography roadmaps hosted by hyperscalers further tip the balance by de-risking future algorithmic transitions.
On-premise installations persist in industries with strict residency mandates or mainframe dependencies. Hybrid architectures offer a middle path, retaining local key custody while bursting tokenisation workloads to the cloud during seasonal spikes. As zero-trust frameworks mature, even conservative sectors may offload non-core workloads, shrinking the on-premise footprint over the forecast horizon.
Complete Report Scope:
- By Component
- Solutions
- Services
- By Deployment Mode
- On-Premise
- Cloud
- By Tokenization Technique
- Vaulted Tokenization
- Vaultless Tokenization
- By Application Area
- Payment Security
- Customer Authentication
- Fraud Prevention and Risk Management
- Compliance and Audit Management
- Others
- By End-User Industry
- BFSI
- Retail and E-commerce
- IT and Telecommunications
- Healthcare and Life Sciences
- Transportation and Logistics
- Government and Public Sector
- Energy and Utilities
- Media and Entertainment
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Nordics
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- ASEAN
- Australia
- New Zealand
- Rest of Asia Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America generated 38.60% of 2025 revenue for the tokenization solution market, anchored by early cloud adoption and a strict payment-security compliance regime. PCI DSS 4.0 deadlines have compressed upgrade cycles, tipping many late adopters toward managed tokenisation services. Market saturation is approaching in core credit-card verticals, so providers are pivoting to adjacent use cases such as healthcare payments and government disbursements.
Asia Pacific is pacing the field with a 19.95% CAGR through 2031, catalysed by mobile-wallet penetration and public-sector digitalisation funds. Japan's ASEAN QR project and Alipay+ merchant expansion exemplify how cross-border wallets leverage network tokens for currency-agnostic settlement. China's super-app ecosystems continue to scale, demanding ultra-high-throughput token engines capable of handling peak shopping festivals. India's unified payments infrastructure offers fertile ground for tokenisation providers that can tailor to local Aadhaar identity norms.
Europe remains a steady adopter, balancing GDPR constraints with strong fraud-prevention incentives. Vaultless implementations resonate with regulators wary of centralised data stores, while national digital-ID programmes open fresh opportunities for citizen-service tokenisation.Fragmented rule sets still complicate pan-European roll-outs, but scheme-level harmonisation is gradually lowering technical barriers.
- Thales Group
- Broadcom Inc. (Symantec Enterprise)
- Visa Inc.
- Mastercard Inc.
- Fiserv Inc. (First Data)
- Worldpay LLC (FIS)
- PayPal Holdings Inc. (Braintree)
- American Express Company
- Protegrity USA Inc.
- TokenEx LLC
- Entrust Corporation
- Rambus Inc. (Bell ID)
- Sequent Software Inc.
- CardConnect Corporation
- Bluefin Payment Systems
- Marqeta Inc.
- Adyen N.V.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in Tokenization Adoption for Contactless and Mobile Wallet Payments in Asia
- 4.2.2 Mandatory PCI DSS 4.0 Compliance Deadlines Boosting Tokenization Investments in North America
- 4.2.3 Rising Fraud Losses in Card-Not-Present Transactions Driving Vaultless Tokenization Uptake in Europe
- 4.2.4 Expansion of "Buy Now Pay Later" Platforms Demanding Tokenized Credentials Integration
- 4.2.5 Emergence of Network Tokenization Programs by Card Schemes Accelerating Merchant Enrolment
- 4.3 Market Restraints
- 4.3.1 Interoperability Gaps among Proprietary Token Service Providers
- 4.3.2 High Latency Concerns in Token Vault Architectures for High-Frequency Trading Firms
- 4.3.3 Limited Awareness of Non-Payment Tokenization Use-Cases in Mid-Tier Healthcare Providers
- 4.3.4 Vendor Lock-in Risk Restricting Adoption by Government Agencies
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory or Technological Outlook
- 4.5.1 Regulatory Landscape
- 4.5.2 Technological Innovations (Tokenization-as-a-Service, Cloud HSM)
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Solutions
- 5.1.2 Services
- 5.2 By Deployment Mode
- 5.2.1 On-Premise
- 5.2.2 Cloud
- 5.3 By Tokenization Technique
- 5.3.1 Vaulted Tokenization
- 5.3.2 Vaultless Tokenization
- 5.4 By Application Area
- 5.4.1 Payment Security
- 5.4.2 Customer Authentication
- 5.4.3 Fraud Prevention and Risk Management
- 5.4.4 Compliance and Audit Management
- 5.4.5 Others
- 5.5 By End-User Industry
- 5.5.1 BFSI
- 5.5.2 Retail and E-commerce
- 5.5.3 IT and Telecommunications
- 5.5.4 Healthcare and Life Sciences
- 5.5.5 Transportation and Logistics
- 5.5.6 Government and Public Sector
- 5.5.7 Energy and Utilities
- 5.5.8 Media and Entertainment
- 5.5.9 Others
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 United Kingdom
- 5.6.3.2 Germany
- 5.6.3.3 France
- 5.6.3.4 Nordics
- 5.6.3.5 Rest of Europe
- 5.6.4 Asia Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 ASEAN
- 5.6.4.6 Australia
- 5.6.4.7 New Zealand
- 5.6.4.8 Rest of Asia Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 United Arab Emirates
- 5.6.5.1.2 Saudi Arabia
- 5.6.5.1.3 Turkey
- 5.6.5.1.4 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Nigeria
- 5.6.5.2.3 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves and Funding
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Thales Group
- 6.4.2 Broadcom Inc. (Symantec Enterprise)
- 6.4.3 Visa Inc.
- 6.4.4 Mastercard Inc.
- 6.4.5 Fiserv Inc. (First Data)
- 6.4.6 Worldpay LLC (FIS)
- 6.4.7 PayPal Holdings Inc. (Braintree)
- 6.4.8 American Express Company
- 6.4.9 Protegrity USA Inc.
- 6.4.10 TokenEx LLC
- 6.4.11 Entrust Corporation
- 6.4.12 Rambus Inc. (Bell ID)
- 6.4.13 Sequent Software Inc.
- 6.4.14 CardConnect Corporation
- 6.4.15 Bluefin Payment Systems
- 6.4.16 Marqeta Inc.
- 6.4.17 Adyen N.V.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment
- 7.2 Emerging Use-Cases Beyond Payments (Healthcare Records, Digital Twins)
- 7.3 Tokenization in IoT Edge Devices

 全球代幣化市場規模、佔有率、趨勢和成長分析報告(2026-2034年)
 2026-2030年全球代幣化市場
 代幣化市場-2026-2032年全球市場預測
 2026年LLM代幣化最佳化全球市場報告
 資產代幣化市場規模、佔有率和趨勢分析報告:按資產類別、投資者類型、代幣化平台、產品、地區和細分市場預測(2026-2033 年)2026年全球標記化市場報告代幣化市場規模、佔有率、成長及全球產業分析:依類型、應用和地區劃分的洞察與預測(2026-2034 年)
 代幣化市場-全球產業規模、佔有率、趨勢、機會與預測:按組件、應用、產業、地區和競爭格局分類,2021-2031年
 中心化交易所代幣(CEX)市場規模、佔有率和成長分析(按區塊鏈平台、代幣類型、交易所類型和地區分類)—2026-2033年產業預測
 代幣化:全球市場佔有率和排名、總收入和需求預測(2025-2031年)