


 |
市場調查報告書
商品編碼
2122515
資料湖:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Data Lake - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,資料湖市場規模將從 2025 年的 186.8 億美元成長到 2026 年的 228 億美元,然後在 2031 年達到 618.4 億美元,2026 年至 2031 年的複合年成長率為 22.08%。
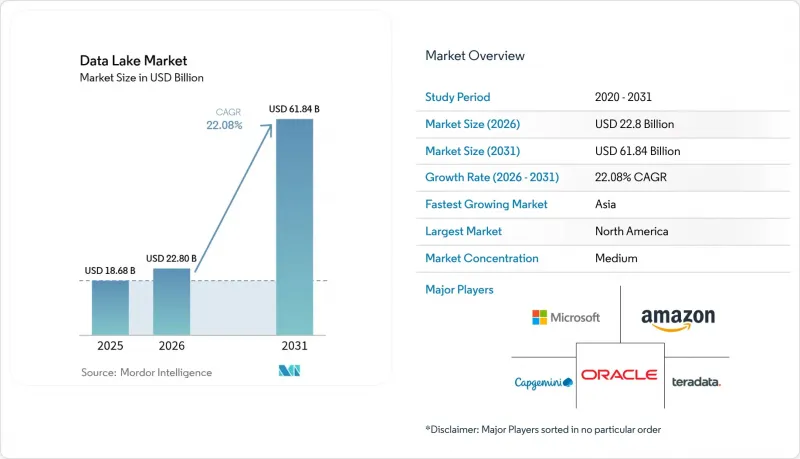
本報告按交付類型(解決方案和服務)、部署類型(雲端和混合/多重雲端)、組織規模(大型企業和中小企業)、業務職能(營運和供應鏈、財務和風險、其他)、最終用戶產業(IT和電信、醫療保健和生命科學、其他)以及地區(北美、亞洲、其他)進行細分。市場預測以美元計價。
全球數據湖市場趨勢及洞察
由於 GenAI 工作負載,非結構化和多模態資料呈現爆炸性成長。
生成式人工智慧應用會產生大量的圖像、音訊和文字數據,因此需要讀取時模式儲存。企業預測,到 2025 年,全球 175 Zetta位元組的資料總量中,將有 30% 需要即時處理,而靜態資料倉儲無法滿足這項需求。因此,資料湖已成為用於提示工程循環的多模態語料庫的預設儲存位置。谷歌雲端的「Lakehouse」藍圖展示如何將原生格式儲存與向量索引結合,從而在降低儲存成本的同時,加速底層模型的微調。延遲採用資料湖的企業將面臨創新週期延長和人工智慧工作負載單位成本增加的風險。
歐洲的資料居住要求正在加速雲端資料湖的普及。
歐盟資料管治法和資料法要求企業對高度敏感的工作負載進行在地化管理。超大規模資料中心業者正在積極響應這項要求,例如AWS已投資78億歐元建置具有內建資料位置控制功能的獨立雲端區域。企業目前正在部署區域分段的資料湖,這些資料湖可以透過聯合引擎進行查詢,同時滿足居住需求。此外,企業對富含資料沿襲資訊的元元資料目錄的需求也日益成長,這些目錄能夠在審計報告中提供跨境資料使用情況的可見性。
元資料漂移正在造成「資料沼澤」。
當資料攝取速度超過目錄更新速度時,資料湖就會變成搜尋的儲存庫。預計到 2025 年,全球資料量將達到 163 Zetta位元組,資料孤島缺乏情境資訊的風險也隨之增加。企業正在透過部署類似 Unity Catalog 的自動化血緣追蹤器來應對這一問題,這些追蹤器會記錄每一次讀寫操作,並標記孤立資產。如果沒有類似的控制措施,管治成本可能會抵銷資料湖整合帶來的預期成本節約。
細分市場分析
到2025年,解決方案將佔資料湖市場收入的69.35%,資料湖市場規模將達到129.5億美元。這一主導地位歸功於企業對儲存引擎、查詢加速器和管治套件的標準化,這些組件構成了人工智慧環境的基礎。隨著工作負載的不斷演變,供應商正在將成本最佳化儀表板、自動分層和原生OpenTable支援等功能捆綁在一起,以保持競爭力。
預計到2031年,「服務」子領域將以24.77%的複合年成長率快速成長,這反映出市場對遷移藍圖、效能調校和全天候維運服務的需求。由於能夠執行平台遷移的人員短缺,許多公司將傳統Hadoop環境的遷移外包給能夠提供可預測服務等級協定(SLA)結果的專家。人才市場的緊張狀況確保了專業服務訂單的成長速度將持續高於整體資料湖市場。
隨著企業對即時可擴展性和整合安全性的需求日益成長,到 2025 年,雲端部署將佔據資料湖市場 64.20% 的佔有率。 Amazon S3 等彈性物件儲存支援生命週期自動化,可自動將冷資料分層儲存到成本更低的類別,從而降低資本支出 (CapEx)。分析引擎可按需啟動,並根據專案進度調整計算成本。
混合雲和多重雲端配置預計將以 23.1% 的複合年成長率成長至 2031 年。 OpenTable 格式允許單一元元資料定義跨越本機和公共雲端儲存桶,從而顯著降低了資料複製的需求。區域法令遵循進一步推動了混合雲策略的發展,企業將受監管的查詢部署在主權區域,同時跨雲端架構進行查詢。因此,混合環境的資料湖市場規模正隨著主權雲的推出同步成長。
區域分析
到2025年,北美將佔全球收入的37.40%,並在架構成熟度方面繼續保持領先地位。金融機構正在延長時間序列資料的保留期限,以適應不斷演進的壓力測試範本;醫院網路正在建立多模態態病患圖譜,為人工智慧驅動的診斷奠定基礎。創業投資也正在推動管治相關新創企業的建立,從而確保生態系統的蓬勃發展。
亞太地區是成長最快的區域,預計到2031年複合年成長率將達到23.5%。日本、印度和新加坡政府正在支持主權雲端項目,從而推動了對符合區域法規的「湖區」(資料湖)的需求。中國電信業者正在分析大量的5G日誌以進行容量規劃,而印尼金融科技公司則在共用大量的詐欺偵測資訊以遏止網路犯罪。像日本的Wasabi這樣的供應商正在亞太地區設立總部,旨在抓住預計36%的IaaS需求成長。
在歐洲,嚴格的資料主權法規正在加速推動雲端運算的普及。 「歐洲數據戰略」正在促進對本地託管的投資,AWS計劃在2025年底前開設勃蘭登堡區域以滿足居住要求。製造商正在儲存用於CSRD報告的即時範圍3排放數據,銀行則在符合審計要求的雲端平台中最佳化巴塞爾協議III的運算。歐洲銀行管理局(EBA)2025年壓力測試範本進一步提高了雲端平台必須滿足的技術要求。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 由於人工智慧(GenAI)工作負載,非結構化和多模態資料呈現爆炸性成長。
- 歐洲的資料居住要求正在加速雲湖的普及。
- Lakehouse Convergence 可將財富 500 強企業的總擁有成本 (TCO) 降低 35-40%。
- 無伺服器表格式(Iceberg/Delta):支援跨多重雲端。
- 工業領域即時ESG範圍3資料收集的要求
- 金融服務領域的監管壓力測試要求保留交易資料長達十年。
- 市場限制因素
- 元資料漂移正在造成“資料沼澤”,推高管治成本。
- 新興地區湖泊工程技術人才短缺
- 對於對延遲敏感的工作負載,資料倉儲仍然優於資料湖。
- 不透明的、基於消費的雲端收費系統使得預算預測變得困難。
- 技術展望
- 波特五力模型
第5章 市場規模與成長預測
- 報價
- 解決方案
- 資料發現與編目
- 資料整合和 ETL/ELT
- 分析和視覺化工具
- 管治與安全平台
- 服務
- 專業服務(諮詢、整合)
- 託管服務
- 解決方案
- 不同的發展
- 雲
- 公共雲端
- 私有雲端
- 混合/多重雲端
- 現場
- 雲
- 按組織規模
- 大公司
- 中小企業
- 業務職能
- 營運和供應鏈
- 金融與風險
- 銷售與行銷
- 人力資源
- 按最終用戶行業分類
- 資訊科技/通訊
- BFSI
- 醫療保健和生命科學
- 零售與電子商務
- 製造業和工業
- 媒體與娛樂
- 政府/公共部門
- 能源公用事業
- 其他(教育、酒店管理)
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 智利
- 秘魯
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 澳洲
- 紐西蘭
- 其他亞太國家
- 中東
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 其他非洲國家
- 北美洲
第6章 競爭情勢
- Strategic Developments
- Vendor Positioning Analysis
- 公司簡介
- Amazon Web Services(AWS)
- Microsoft Corporation
- Google LLC
- IBM Corporation
- Oracle Corporation
- Snowflake Inc.
- SAP SE
- Cloudera Inc.
- Teradata Corporation
- Informatica Inc.
- Databricks Inc.
- Hitachi Vantara LLC
- Dell Technologies Inc.
- Atos SE
- SAS Institute Inc.
- Zaloni Inc.
- Dremio Corporation
- Qubole Inc.
- Talend SA
- HPE(Ezmeral)
第7章 市場機會與未來展望
According to Mordor Intelligence, the data lakes market size is expected to grow from USD 18.68 billion in 2025 to USD 22.8 billion in 2026 and is forecast to reach USD 61.84 billion by 2031 at 22.08% CAGR over 2026-2031.
This report is Segmented by Offering (Solutions, and Services), Deployment (Cloud, and Hybrid/Multi-Cloud), Organization Size (Large Enterprises, and SMEs), Business Function (Operations and Supply-Chain, Finance and Risk, and More), End-User Vertical (IT and Telecom, Healthcare and Life Sciences, and More), and Geography (North America, Asia, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Data Lake Market Trends and Insights
Explosion of unstructured and multimodal data from GenAI workloads
Generative-AI applications create vast image, audio, and text payloads that demand schema-on-read storage. Enterprises expect 30% of the global 175 zettabyte data sphere to require real-time processing by 2025, a profile unsuited to rigid warehouses. Data lakes therefore become the default landing zone for multi-modal corpora used in prompt-engineering loops.Google Cloud's lakehouse blueprint shows how native-format storage paired with vector indexing accelerates foundation-model fine-tuning while lowering storage bills. Firms delaying adoption risk slower innovation cycles and higher unit-costs on AI workloads.
Data-residency mandates in Europe accelerating cloud-based lake adoption
The EU Data Governance Act and Data Act compel organizations to localize sensitive workloads. Hyperscalers are responding: AWS is investing EUR 7.8 billion in a sovereign-cloud region that ships with embedded data-location controls. Enterprises now deploy region-segmented data lakes that meet residency rules yet remain queryable through federated engines, sparking demand for lineage-rich metadata catalogs capable of surfacing cross-border data usage in audit reports.
Metadata drift creating "data swamps"
When ingestion outpaces catalog updates, data lakes devolve into unsearchable repositories. By 2025, global data volume will reach 163 zettabytes, heightening the risk of siloed files with missing context. Enterprises are responding by adopting automated lineage trackers such as Unity Catalog, which logs every read-write and flags orphaned assets. Without similar controls, governance overhead can erase savings projected from lakehouse consolidation.
Other drivers and restraints analyzed in the detailed report include:
- Lakehouse convergence delivering 35-40% TCO savings
- Serverless table formats unlocking multi-cloud portability
- Skilled lake-engineering talent shortfall in emerging regions
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Solutions generated 69.35% of data lakes market revenue in 2025, equating to a data lakes market size of USD 12.95 billion. The dominance comes from enterprises standardizing on storage engines, query accelerators, and governance suites that form the backbone of AI-ready environments. Vendors bundle cost-optimizer dashboards, automated tiering, and native open-table support, maintaining relevance as workloads evolve.
The services sub-segment is racing ahead at a 24.77% CAGR to 2031, reflecting demand for migration blueprints, performance tuning, and 24X7 managed operations. Many firms lack staff who can re-platform legacy Hadoop estates, so they contract specialists that promise predictable SLA outcomes. The tight talent market ensures professional-services bookings will keep growing faster than the overall data lakes market
Cloud deployments captured 64.20% of the data lakes market share in 2025 as organizations sought instant scalability and integrated security. Elastic object stores like Amazon S3 eliminate CapEx while delivering lifecycle automation that auto-tiers cold data to low-cost classes. Analytics engines then spin up on demand, keeping compute spend aligned with project tempo.
Hybrid and multi-cloud configurations are expanding at 23.1% CAGR to 2031. Open-table formats let one metadata definition span on-prem and public-cloud buckets, slashing replication needs. Regional compliance rules further fuel hybrid strategies, as firms pin regulated workloads in sovereign regions yet still query them through cross-cloud fabrics. As a result, the data lakes market size for hybrid environments is rising in lockstep with sovereign-cloud launches.
Complete Report Scope:
- By Offering
- Solutions
- Data Discovery and Cataloging
- Data Integration and ETL/ELT
- Analytics and Visualization Tools
- Governance and Security Platforms
- Services
- Professional Services (Consulting, Integration)
- Managed Services
- Solutions
- By Deployment
- Cloud
- Public Cloud
- Private Cloud
- Hybrid/Multi-Cloud
- On-Premise
- Cloud
- By Organization Size
- Large Enterprises
- Small and Mid-Size Enterprises (SMEs)
- By Business Function
- Operations and Supply-Chain
- Finance and Risk
- Sales and Marketing
- Human Resources
- By End-User Vertical
- IT and Telecom
- BFSI
- Healthcare and Life Sciences
- Retail and E-commerce
- Manufacturing and Industrial
- Media and Entertainment
- Government and Public Sector
- Energy and Utilities
- Others (Education, Hospitality)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Peru
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- New Zealand
- Rest of Asia-Pacific
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- North America
Geography Analysis
North America generated 37.40% of 2025 revenue and continues to set benchmarks in architecture maturity. Financial institutions lengthen time-series retention to meet evolving stress-test templates, while hospital networks build multimodal patient graphs that underpin AI-driven diagnostics. Venture capital also fuels governance-start-up formation, ensuring a vibrant ecosystem.
Asia-Pacific is the fastest-expanding region, clocking a 23.5% CAGR through 2031. Governments in Japan, India, and Singapore sponsor sovereign-cloud projects, spurring demand for region-compliant lake zones. Telcos in China analyze massive 5G logs for capacity planning, whereas Indonesian fintechs share fraud-intelligence lakes to curb cybercrime. Vendors establishing APAC headquarters, such as Wasabi in Japan, aim to catch the projected 36% IaaS upturn.
Europe accelerates adoption under strict data-sovereignty mandates. The European Strategy for Data drives investment in local hosting, and AWS will open a Brandenburg region by late 2025 to satisfy residency rules. Manufacturers store real-time Scope-3 emissions for CSRD reporting, and banks refine Basel III calculations inside audit-ready lakes. The European Banking Authority's 2025 stress-test templates reinforce technical requirements that lakehouses fulfill.
- Amazon Web Services (AWS)
- Microsoft Corporation
- Google LLC
- IBM Corporation
- Oracle Corporation
- Snowflake Inc.
- SAP SE
- Cloudera Inc.
- Teradata Corporation
- Informatica Inc.
- Databricks Inc.
- Hitachi Vantara LLC
- Dell Technologies Inc.
- Atos SE
- SAS Institute Inc.
- Zaloni Inc.
- Dremio Corporation
- Qubole Inc.
- Talend SA
- HPE (Ezmeral)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Explosion of Unstructured and Multimodal Data from GenAI Workloads
- 4.2.2 Data-Residency Mandates in Europe Accelerating Cloud-based Lake Adoption
- 4.2.3 Lakehouse Convergence Driving 35-40% TCO Savings for Fortune-500 Firms
- 4.2.4 Serverless Table Formats (Iceberg/Delta) Unlocking Multi-Cloud Portability
- 4.2.5 Real-Time ESG Scope-3 Data Capture Requirements in Industrial Sector
- 4.2.6 Regulatory Stress-Testing in Financial Services Demanding Decade-Scale Tick Data Retention
- 4.3 Market Restraints
- 4.3.1 Metadata Drift Creating "Data Swamps" and Raising Governance Cost
- 4.3.2 Skilled Lake Engineering Talent Shortfall in Emerging Regions
- 4.3.3 Latency-Sensitive Workloads Still Favoring Warehouses over Lakes
- 4.3.4 Opaque Consumption-Based Cloud Pricing Complicating Budget Forecasts
- 4.4 Technological Outlook
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Offering
- 5.1.1 Solutions
- 5.1.1.1 Data Discovery and Cataloging
- 5.1.1.2 Data Integration and ETL/ELT
- 5.1.1.3 Analytics and Visualization Tools
- 5.1.1.4 Governance and Security Platforms
- 5.1.2 Services
- 5.1.2.1 Professional Services (Consulting, Integration)
- 5.1.2.2 Managed Services
- 5.1.1 Solutions
- 5.2 By Deployment
- 5.2.1 Cloud
- 5.2.1.1 Public Cloud
- 5.2.1.2 Private Cloud
- 5.2.1.3 Hybrid/Multi-Cloud
- 5.2.2 On-Premise
- 5.2.1 Cloud
- 5.3 By Organization Size
- 5.3.1 Large Enterprises
- 5.3.2 Small and Mid-Size Enterprises (SMEs)
- 5.4 By Business Function
- 5.4.1 Operations and Supply-Chain
- 5.4.2 Finance and Risk
- 5.4.3 Sales and Marketing
- 5.4.4 Human Resources
- 5.5 By End-User Vertical
- 5.5.1 IT and Telecom
- 5.5.2 BFSI
- 5.5.3 Healthcare and Life Sciences
- 5.5.4 Retail and E-commerce
- 5.5.5 Manufacturing and Industrial
- 5.5.6 Media and Entertainment
- 5.5.7 Government and Public Sector
- 5.5.8 Energy and Utilities
- 5.5.9 Others (Education, Hospitality)
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Chile
- 5.6.2.4 Peru
- 5.6.2.5 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 Australia
- 5.6.4.5 New Zealand
- 5.6.4.6 Rest of Asia-Pacific
- 5.6.5 Middle East
- 5.6.5.1 United Arab Emirates
- 5.6.5.2 Saudi Arabia
- 5.6.5.3 Turkey
- 5.6.5.4 Rest of Middle East
- 5.6.6 Africa
- 5.6.6.1 South Africa
- 5.6.6.2 Rest of Africa
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Strategic Developments
- 6.2 Vendor Positioning Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.3.1 Amazon Web Services (AWS)
- 6.3.2 Microsoft Corporation
- 6.3.3 Google LLC
- 6.3.4 IBM Corporation
- 6.3.5 Oracle Corporation
- 6.3.6 Snowflake Inc.
- 6.3.7 SAP SE
- 6.3.8 Cloudera Inc.
- 6.3.9 Teradata Corporation
- 6.3.10 Informatica Inc.
- 6.3.11 Databricks Inc.
- 6.3.12 Hitachi Vantara LLC
- 6.3.13 Dell Technologies Inc.
- 6.3.14 Atos SE
- 6.3.15 SAS Institute Inc.
- 6.3.16 Zaloni Inc.
- 6.3.17 Dremio Corporation
- 6.3.18 Qubole Inc.
- 6.3.19 Talend SA
- 6.3.20 HPE (Ezmeral)
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment

 資料湖市場-2026-2032年全球市場預測
 資料湖市場預測至 2034 年—按組件、業務功能、部署模式、組織規模、最終用戶和地區分類的全球分析資料湖平台市場預測至2034年:按組件、部署模式、最終用戶和區域分類的全球分析
 2026年全球資料湖分析市場報告2026年全球能源資料湖平台市場報告2026年全球銀行資料湖平台市場報告2026年全球網格資料湖平台市場報告2026年全球資料倉儲湖平台市場報告2026年全球資料湖市場報告
 資料湖市場分析及預測(至2035年):按類型、產品類型、服務、技術、組件、應用、部署類型、最終用戶和功能分類