


 |
市場調查報告書
商品編碼
2122432
冷媒:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031 年)Refrigerants - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
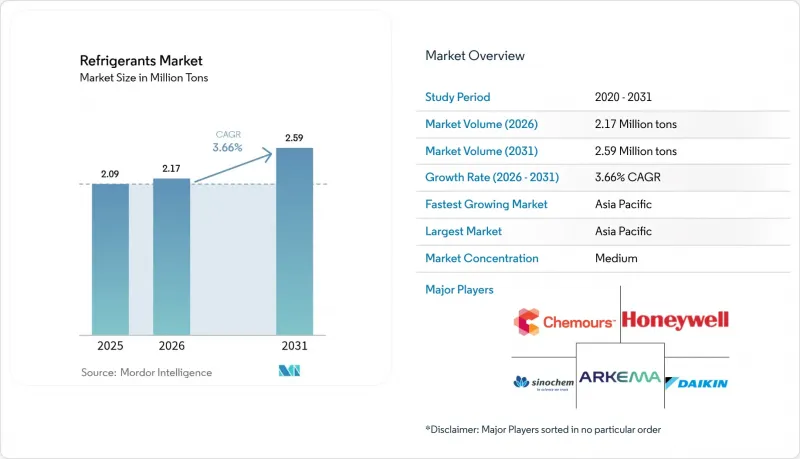
根據 Mordor Intelligence 預測,冷媒市場將從 2025 年的 209 萬噸成長到 2026 年的 217 萬噸,然後在 2031 年達到 259 萬噸,2026 年至 2031 年的複合年成長率為 3.66%。
本報告按類型(氟碳化合物、無機化合物、碳氫化合物、其他)、應用(製冷、空調、其他應用)、最終用戶行業(住宅和商業建築、食品和飲料加工、製藥和醫療保健、汽車和電動汽車、其他)以及地區(亞太地區、北美、歐洲、南美、中東和非洲)進行分類。
全球冷媒市場趨勢與洞察
亞洲新興國家對室內空調和車載空調的需求不斷成長。
快速的都市化推動了二、三線城市對住宅空調需求的成長,同時,汽車產業正從內燃機轉型為電動驅動系統。預計到2030年,中國熱泵的年出貨量將達到5,000萬台,而印度的家用空調普及率仍低於10%,顯示其市場需求潛力巨大。日本修訂的《氟碳化合物法》和韓國的能源效率管理計畫設定了全球暖化潛勢(GWP)上限,加速了丙烷、R-32和部分重油(HFO)混合冷媒的採購。該地區的汽車製造商正在將R-1234yf作為車載冷媒和電池迴路冷媒進行標準化應用,加速了亞太地區的冷媒轉換。預計在預測期內,住宅空調普及率的提高和電動車的普及將成為冷媒市場絕對噸位成長的最大驅動力。
電動車的溫度控管要求
電動車 (EV) 的電池化學特性要求在較窄的溫度範圍內運行,以確保電池壽命和充電速度。 R-1234yf 在美國新型緊湊型轎車的滲透率高達 95%,目前全球已有 2.2 億輛汽車安裝了這種冷媒。同時,現有車隊正在採用改裝套件,用同種分子冷媒取代 R-134a。整合了車廂供暖和電池冷卻功能的熱泵系統正逐漸普及到大眾市場,推動了基於 A2L 的冷媒混合物的消費,這些混合物針對 -30 度C至 +45 度C的溫度範圍內的效率曲線進行了最佳化。壓縮機製造商透過調整外殼和變頻器,將渦旋噪音降低了 6 分貝,這對於高階電動車車型而言是一項關鍵指標。預計這些協同效應將推動汽車冷媒市場在 2020 年代中期實現成長。
全球更嚴格地逐步淘汰氫氟碳化合物(基加利協議、歐盟氟化氣體法規)
歐盟第2024/573號法規將氫氟碳化合物(HFC)配額從2025年基準水準的60%降至2036年的15%,目標是在2050年之前完全淘汰。基加利修正案下類似的產量凍結措施正同時給所有生產商帶來壓力,導致冷媒市場供應緊張,並推高現貨價格。營運商必須為容量超過500噸二氧化碳當量(tCO2e)的新系統安裝自動洩漏檢測系統,這增加了合規預算,並將資金從產能擴張中轉移。由此產生的不確定性正在延緩大規模安裝專案的決策週期,並將使轉型中期的預期複合年成長率(CAGR)降低近2個百分點。
細分市場分析
預計到2025年,碳氫化合物將佔冷媒市場佔有率的49.02%,這主要得益於多項含氟氣體法規的豁免以及其極具吸引力的總體擁有成本(TCO)優勢。領先企業報告稱,住宅熱泵和商用即插即用型空調機組的出貨量實現了兩位數成長,而R-290分離式空調機組在全球採用修訂版最低能源效率標準(MEPS)的地區正加速部署。氫氟烯烴的複合年成長率(CAGR)最高,達到9.86%,這主要得益於其在汽車和固定式暖通空調(HVAC)領域的應用,這兩個領域即將禁止使用全球暖化潛勢(GWP)超過750的冷媒。這兩個低GWP領域抵消了含氟冷媒銷售的下降,並支撐了整體冷媒市場的成長。
在下游市場,氨和二氧化碳等無機製冷劑在大規模食品加工廠和超級市場的市場規模持續擴大。工程師們正在採用將二氧化碳用於下迴路、合成冷媒用於上迴路的設計方案來提高效率,而這種配置的有效性已在近期對各種級聯組合的性能係數(COP)比較中得到證實。雖然資料中心和製藥冷凍庫的浸沒式冷卻推動了二氧化碳冷媒的成長,但氨冷媒在倉庫冷水機組中仍然佔據著重要地位。針對天然冷媒的排碳權計畫使商業前景更加誘人,並持續推動市場佔有率從傳統氫氟碳化合物(HFC)轉移到天然冷卻器的使用。
區域分析
預計到2025年,亞太地區將佔據全球冷媒市場50.10%的佔有率,反映了該地區龐大的製造業基礎、快速上升的都市區氣溫以及有利的政策框架。中國室內空調的出口量正隨著國內市場滲透率的提高而成長,R-32和R-290冷媒的大規模分銷也正透過垂直整合的供應鏈逐步建立。印度針對白色家電的生產連結獎勵計畫計畫(PLI)包含對低全球暖化潛值(GWP)冷媒研發的津貼,從而加速了本地零件生態系統的發展。日本和韓國在尖端材料的研發方面處於領先地位,並向全部區域輸出其混合技術。東南亞國家透過持續投資冷鏈基礎建設,進一步鞏固了亞太地區在冷媒市場的領先地位。
北美正採取一種平衡的策略:美國《AIM法案》強制分階段降低氫氟碳化合物(HFC)的消費上限,同時推動暖通空調(HVAC)維修中對氫氟烯烴(HFO)的需求快速成長。由於科珀斯克里斯蒂工廠產能提升,Chemores公司2025年第一季的Option產品銷售量激增40%。加拿大的碳定價機制進一步加速了食品零售業設備規格向天然冷媒的過渡。同時,在墨西哥的工業區,在過渡期內,氟化冷媒在GWP上限範圍內仍被用作製程冷卻設備。
歐洲正在最嚴格的法律規範下應對。 F-Gas 2024配額和生態設計法規迫使原始設備製造商(OEM)大規模部署R-290熱泵,德國和法國的補貼計畫也為此提供了支持。由於高溫最佳化包裝技術,超臨界二氧化碳冷媒正逐漸成為超級市場的標配,即使在南部氣候區也是如此。英國雖然保留了自己的配額制度,但也遵循歐盟的時間表,因此整個歐洲的冷媒市場前景正在趨於一致。
南美洲、中東和非洲等新興地區構成了冷媒市場的長尾部分。儘管分階段減排計畫的延遲延長了對氫氟碳化合物(HFCs)的需求,但人均製冷需求的成長正在推動未來低全球暖化潛值(GWP)冷媒的引進週期。多邊開發銀行正透過一系列專案來解決基礎設施不平衡問題,這些專案將冷鏈物流與農業生產力的提升相結合。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 亞洲新興國家對室內空調和車載空調的需求不斷成長。
- 冷藏倉庫和第三方物流冷鏈設施的擴建
- 電動車的溫度控管要求
- 用於mRNA疫苗的超低溫冷凍庫
- 天然冷媒排碳權貨幣化
- 市場限制因素
- 全球更嚴格地逐步淘汰氫氟碳化合物(基加利協議、歐盟氟化氣體法規)
- 易燃 A3/A2L 氣體的初始成本高,且處理風險大。
- 下一代HFO分子的價格暴漲暴跌
- 價值鏈分析
- 監理情勢
- 波特五力模型
第5章 市場規模與成長預測
- 按類型
- 氟碳化合物
- 氟烴塑膠(HCFCs)
- 氫氟碳化合物(HFCs)
- 無機物
- 氨
- 二氧化碳
- 其他無機化合物
- 碳氫化合物
- 異丁烷
- 丙烷
- 其他碳氫化合物
- 其他類型(氫氟烯烴(HFOs))
- 氟碳化合物
- 透過使用
- 冰凍
- 家用
- 商業的
- 用於運輸
- 工業的
- 空調
- 獨立式室內空調/箱型冷氣
- 冷卻器
- 移動的
- 其他用途
- 冰凍
- 按最終用戶行業分類
- 住宅及商業建築
- 食品和飲料加工
- 製藥和醫療保健
- 汽車和電動旅行
- 化工/石油化工
- 其他終端用戶產業
- 按地區
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- ASEAN
- 其他亞太國家
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 法國
- 英國
- 義大利
- 俄羅斯
- 其他歐洲國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 南非
- 其他中東和非洲國家
- 亞太地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率/排名分析
- 公司簡介
- A-Gas International Ltd
- AGC Inc.
- Arkema
- Brothers Gas
- Daikin Industries, Ltd.
- Dongyue Group
- Gulfcryo.
- Harp International Ltd
- Honeywell International Inc
- Linde PLC
- Messer SE & Co. KGaA
- Navin Fluorine International Ltd
- Orbia
- Shandong Yuean Chemical Industry Co., Ltd
- Sinochem Holdings Corporation Ltd
- SRF Limited
- The Chemours Company
- Zhejiang Juhua Co. Ltd.
第7章 市場機會與未來展望
According to Mordor Intelligence, the refrigerants market size is expected to grow from 2.09 million tons in 2025 to 2.17 million tons in 2026 and is forecast to reach 2.59 million tons by 2031 at 3.66% CAGR over 2026-2031.
This report is Segmented by Type (Fluorocarbons, Inorganics, Hydrocarbons, Other Types), Application (Refrigeration, Air-Conditioning, Other Applications), End-User Industry (Residential and Commercial Buildings, Food and Beverage Processing, Pharmaceuticals and Healthcare, Automotive and E-Mobility, and More), and Geography (Asia-Pacific, North America, Europe, South America, Middle-East and Africa).
Global Refrigerants Market Trends and Insights
High Demand for Room and Car Air-Conditioners in Emerging Asia
Rapid urbanization is pushing residential cooling deeper into tier-2 and tier-3 city households while the automotive sector simultaneously swaps internal-combustion platforms for electric drivetrains. China's heat-pump shipments are projected to hit 50 million units annually by 2030, and India's household air-conditioner penetration remains under 10%, underscoring significant latent demand. Japan's revised F-Gas Law and South Korea's efficiency management program impose GWP ceilings that funnel procurement toward propane, R-32, and shortlisted HFO blends. Vehicle OEMs in the region are standardizing R-1234yf for cabin and battery loops, accelerating molecule transition volumes throughout Asia-Pacific. Together, residential uptake and e-mobility adoption underpin the largest absolute tonnage additions in the refrigerant market during the forecast window.
Electrified-Vehicle Thermal-Management Requirements
Electric vehicle (EV) battery chemistries demand narrow temperature windows for longevity and charging speed. R-1234yf enjoys 95% penetration in new U.S. light-duty vehicles, with 220 million cars worldwide now equipped, while legacy fleets adopt retrofit kits that swap out R-134a for the same molecule. Heat-pump architectures unifying cabin heating and battery cooling are spreading into mass-market segments, spurring consumption of blended A2L fluids optimized for -30 °C to +45 °C efficiency curves. Compressor suppliers have cut scroll noise by 6 dBA through housing and inverter tuning, a key specification for premium EV models. The aggregate effect widens the addressable refrigerant market for mobility applications through mid-decade.
Stringent Global HFC Phase-Down (Kigali, EU F-Gas)
EU Regulation 2024/573 cuts HFC quotas from 60% of baseline levels in 2025 to 15% in 2036, with full phase-out targeted by 2050. Similar freezes under the Kigali Amendment pressure all producers simultaneously, tightening supply and elevating spot prices across the refrigerant market. Operators installing new systems must adopt automated leak detection above 500 tCO2e capacity, raising compliance budgets and reallocating capital away from volume growth. The resulting uncertainty slows decision cycles for large installations, shaving nearly two percentage points from projected CAGR during mid-transition years.
Other drivers and restraints analyzed in the detailed report include:
- Ultralow-Temperature Freezers for mRNA-Type Vaccines
- Carbon-Credit Monetization for Natural Refrigerants
- High First-Cost and Handling Risk of Flammable A3/A2L Gases
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hydrocarbons commanded 49.02% refrigerant market share in 2025 on the back of exemption status under multiple F-Gas schedules and compelling cost-of-ownership economics. Market leaders report double-digit shipment growth into residential heat-pumps and plug-in commercial cabinets, while global roll-outs of R-290 split units accelerate in regions adopting MEPS revisions. Hydrofluoro-olefins are delivering the fastest 9.86% CAGR, propelled by automotive and stationary HVAC debuts where regulatory cut-off dates for GWP greater than 750 fluids are imminent. Collectively, these two low-GWP segments offset contracting fluorocarbon tonnage, anchoring overall refrigerant market growth.
Downstream, the refrigerant market size for inorganic options such as ammonia and CO2 continues to expand in large food-processing plants and big-box supermarkets. Engineers pair CO2 in low-stage loops with synthetic high-stage fluids for efficiency gains, an architecture validated by recent COP comparisons across cascade permutations. Data-center immersion cooling and pharma freezers add pocket growth for CO2, while ammonia remains entrenched in warehouse chillers. Natural-refrigerant carbon-credit programs further sweeten the business case, ensuring sustained share migration away from legacy HFCs.
Complete Report Scope:
- By Type
- Fluorocarbons
- Hydrochlorofluorocarbons (HCFC)
- Hydrofluorocarbons (HFC)
- Inorganics
- Ammonia
- Carbon Dioxide
- Other Inorganics
- Hydrocarbons
- Isobutane
- Propane
- Other Hydrocarbons
- Other Types (Hydrofluoro-olefins (HFO))
- Fluorocarbons
- By Application
- Refrigeration
- Domestic
- Commercial
- Transportation
- Industrial
- Air-Conditioning
- Stationary Room/Packaged
- Chillers
- Mobile
- Other Applications
- Refrigeration
- By End-user Industry
- Residential and Commercial Buildings
- Food and Beverage Processing
- Pharmaceuticals and Healthcare
- Automotive and e-Mobility
- Chemicals and Petrochemicals
- Other Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- United Kingdom
- Italy
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific's 50.10% refrigerant market share in 2025 reflects the region's outsized manufacturing base, urban temperature spikes, and supportive policy frameworks. China's room-air-conditioner exports grow with domestic uptake, locking in bulk R-32 and R-290 flows through vertically integrated supply chains. India's Production Linked Incentive (PLI) scheme for white goods includes grants for low-GWP refrigerant R&D, expediting local component ecosystems. Japan and South Korea anchor advanced-material development for A2L blends, exporting formulation know-how across the region. Southeast Asian economies follow with cold-chain infrastructure funding, reinforcing Asia-Pacific's reinforced leadership of the refrigerant market.
North America tracks a balanced path as the U.S. AIM Act mandates an HFC consumption-cap glide path while simultaneously turbo-charging demand for HFOs in HVAC retrofits. Chemours logged a 40% surge in Opteon sales during Q1 2025, enabled by its Corpus Christi capacity expansion. Canada's carbon-pricing architecture further skews equipment specifications toward natural refrigerants in food retail, whereas Mexico's industrial corridor demands process-cooling fluorocarbons under transitional GWP ceilings.
Europe navigates the tightest regulatory straitjacket. F-Gas 2024 quotas and eco-design rules push OEMs to deploy R-290 heat-pumps at scale, supported by German and French subsidy pools. Transcritical CO2 has become the default supermarket specification even in southern climates thanks to high-ambient optimization packages. The United Kingdom maintains an independent quota system but mirrors EU timelines, keeping the refrigerant market outlook convergent across the continent.
Emerging regions across South America and Middle East & Africa constitute the long-tail of the refrigerant market. Delayed phase-down schedules prolong HFC demand, yet rising per-capita cooling expectations seed future low-GWP adoption cycles. Infrastructure gaps are being addressed through multilateral development-bank programs that bundle cold-chain logistics with agricultural productivity mandates.
- A-Gas International Ltd
- AGC Inc.
- Arkema
- Brothers Gas
- Daikin Industries, Ltd.
- Dongyue Group
- Gulfcryo.
- Harp International Ltd
- Honeywell International Inc
- Linde PLC
- Messer SE & Co. KGaA
- Navin Fluorine International Ltd
- Orbia
- Shandong Yuean Chemical Industry Co., Ltd
- Sinochem Holdings Corporation Ltd
- SRF Limited
- The Chemours Company
- Zhejiang Juhua Co. Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 High demand for room and car air-conditioners in emerging Asia
- 4.2.2 Expansion of refrigerated warehousing and 3PL cold-chain nodes
- 4.2.3 Electrified-vehicle thermal-management requirements
- 4.2.4 Ultralow-temperature freezers for mRNA-type vaccines
- 4.2.5 Carbon-credit monetisation for natural refrigerants
- 4.3 Market Restraints
- 4.3.1 Stringent global HFC phase-down (Kigali, EU F-Gas)
- 4.3.2 High first-cost and handling risk of flammable A3/A2L gases
- 4.3.3 Boom-bust price swings for next-gen HFO molecules
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Porter's Five Forces
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Type
- 5.1.1 Fluorocarbons
- 5.1.1.1 Hydrochlorofluorocarbons (HCFC)
- 5.1.1.2 Hydrofluorocarbons (HFC)
- 5.1.2 Inorganics
- 5.1.2.1 Ammonia
- 5.1.2.2 Carbon Dioxide
- 5.1.2.3 Other Inorganics
- 5.1.3 Hydrocarbons
- 5.1.3.1 Isobutane
- 5.1.3.2 Propane
- 5.1.3.3 Other Hydrocarbons
- 5.1.4 Other Types (Hydrofluoro-olefins (HFO))
- 5.1.1 Fluorocarbons
- 5.2 By Application
- 5.2.1 Refrigeration
- 5.2.1.1 Domestic
- 5.2.1.2 Commercial
- 5.2.1.3 Transportation
- 5.2.1.4 Industrial
- 5.2.2 Air-Conditioning
- 5.2.2.1 Stationary Room/Packaged
- 5.2.2.2 Chillers
- 5.2.2.3 Mobile
- 5.2.3 Other Applications
- 5.2.1 Refrigeration
- 5.3 By End-user Industry
- 5.3.1 Residential and Commercial Buildings
- 5.3.2 Food and Beverage Processing
- 5.3.3 Pharmaceuticals and Healthcare
- 5.3.4 Automotive and e-Mobility
- 5.3.5 Chemicals and Petrochemicals
- 5.3.6 Other Industries
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 France
- 5.4.3.3 United Kingdom
- 5.4.3.4 Italy
- 5.4.3.5 Russia
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share**/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 A-Gas International Ltd
- 6.4.2 AGC Inc.
- 6.4.3 Arkema
- 6.4.4 Brothers Gas
- 6.4.5 Daikin Industries, Ltd.
- 6.4.6 Dongyue Group
- 6.4.7 Gulfcryo.
- 6.4.8 Harp International Ltd
- 6.4.9 Honeywell International Inc
- 6.4.10 Linde PLC
- 6.4.11 Messer SE & Co. KGaA
- 6.4.12 Navin Fluorine International Ltd
- 6.4.13 Orbia
- 6.4.14 Shandong Yuean Chemical Industry Co., Ltd
- 6.4.15 Sinochem Holdings Corporation Ltd
- 6.4.16 SRF Limited
- 6.4.17 The Chemours Company
- 6.4.18 Zhejiang Juhua Co. Ltd.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

 冷媒沖洗市場:依產品類型、應用、通路、最終用戶、國家及地區分類-全球產業分析、市場規模、市場佔有率及2026年至2033年預測
 冷媒市場:全球市場預測,2026-2032年
 冷媒充填機市場預測至2034年-按冷媒類型、型號、銷售管道、技術、應用、最終用戶和地區分類的全球分析
 冷媒市場規模、佔有率、趨勢和預測:按產品類型、應用和地區分類(2026-2034 年)
 HFO-1234YF全球市場報告(2026年)
 冷媒市場規模、佔有率、成長及全球產業分析:按類型、應用和地區分類的洞察,2026-2034 年預測
 2026-2030年全球冷媒市場低全球暖化潛勢浸沒式冷卻液市場:依最終用戶、產品類型、成分、安裝類型、黏度等級及應用分類,2026-2032年全球預測
 R402b冷媒市場規模、佔有率和成長分析:按冷媒類型、產品配方、應用、終端用戶產業、分銷通路、地區和產業預測分類,2026-2033年
 氟碳冷媒市場規模、佔有率和成長分析:按冷媒類型、配方類型、應用、終端用戶產業、分銷通路、地區和產業預測分類,2026-2033年