


 |
市場調查報告書
商品編碼
2122389
空氣清淨機:市佔率分析、產業趨勢及統計、成長預測(2026-2031)Air Purifier - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
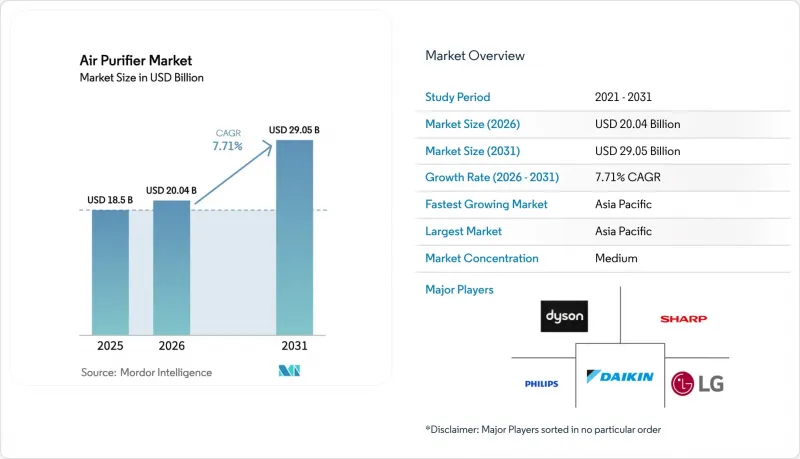
根據 Mordor Intelligence 預測,空氣清淨機市場規模將從 2025 年的 185 億美元成長到 2026 年的 200.4 億美元,然後在 2031 年達到 290.5 億美元,2026 年至 2031 年的複合年成長率為 7.71%。
本報告按過濾技術(HEPA、活性碳、離子/靜電除塵器、UV-C/光催化氧化、混合/多級系統)、類型(獨立式、管道式)、連接方式(非智慧、智慧/物聯網)、最終用戶(住宅、商業、工業)和地區(北美、歐洲、亞太、南美、中東和非洲)進行分類。
全球空氣清淨機市場趨勢及洞察
新冠疫情後,健康型設備在東亞主要城市普及。
在北京、首爾和東京,PM2.5濃度持續超過國家標準,導致空氣清淨機全年普及,並推動空氣清淨機市場在疫情引發的激增後持續成長。中國生態環境部確認,在2024年監測的168個城市中,有38個城市未能達到PM2.5標準。日本厚生勞動省於2024年修訂了室內空氣品質指南,建議在托兒機構和養老機構使用高效能空氣微粒過濾器(HEPA過濾器),並規範過濾器更換週期。在韓國,在超潔淨晶圓廠工作的半導體工程師擴大將職場的標準帶到家中,催生了一群追求高階住宅的消費者。小米計劃於2025年在武漢開設一家投資25億元人民幣的智慧家電工廠,新增年產能700萬台,並可靈活調整以滿足國內外訂單需求。這些監管措施的推動,加上消費者的需求,正在鞏固東亞穩定的需求基礎。
北美地區對商業房地產PM2.5含量製定了更嚴格的標準(LEED v4.1)
LEED v4.1 的「室內環境品質」認證要求使用 MERV 13 或更高級別的過濾器,並持續監測 PM2.5,這迫使美國和加拿大的業主要么維修,要么從設計階段就將先進的淨化系統納入其規範。 10 萬平方英尺辦公空間的合規預算在 5 萬至 15 萬美元之間,但隨著租戶要求健康建築認證以吸引人才和進行 ESG 報告,此類投資的合理性日益凸顯。 ASHRAE 62.1-2022 進一步提高了室外空氣通風率,並建議在會議空間中採用管道式 HEPA 模組與可攜式設備相結合的混合解決方案。據加拿大綠色建築委員會稱,到 2025 年,68% 的新建商業項目將獲得 LEED 認證,這表明 LEED 認證正逐漸成為主流。預計這些標準將在歐洲推廣,因為修訂後的《建築能源性能指令》將於 2027 年納入室內空氣品質指標。
加州和日本對離子產生器的臭氧排放法規
2024年,加州空氣資源委員會將室內空氣清淨機的臭氧排放量限制在0.050 ppm,這實際上淘汰了依賴電離技術的產品。日本厚生勞動省也於2025年實施了類似的標籤規定,限制在托兒機構銷售離子產生器。依賴電離技術的品牌,例如夏普和Panasonic,將不得不承擔每台設備15至25美元的重新設計成本以符合標準,這將對入門級產品的利潤率造成壓力。這項監管變化促使市場需求轉向僅配備HEPA過濾器或混合型產品,從而使不採用離子發生器的競爭對手受益。
細分市場分析
預計到2025年,高效能空氣微粒過濾器(HEPA過濾器)將佔據空氣清淨機市場68.1%的佔有率,這主要得益於其對0.3微米顆粒高達99.97%的捕獲效率,以及美國環保署(EPA)和世界衛生組織(WHO)的建議。隨著家庭和企業越來越希望在機殼空氣清淨機預計將以9.3%的複合年成長率成長。大金的「Streamer」等離子模組在2024年的實驗室測試中展現出對SARS-CoV-2病毒99.9%的去活化率。Panasonic的「nanoe X」羥基自由基發生器在日本養老市場越來越受歡迎,因為在該市場,病原體控制與顆粒物捕獲同等重要。同時,隨著加州和日本臭氧排放法規的日益嚴格,離子集塵機正逐漸轉向小眾工業應用領域。然而,由於混合式設備缺乏統一的性能標準,醫院和製藥廠對風險規避的重視程度較低,導致混合式設備的應用速度放緩。
此混合系統可搭配智慧感測器陣列,可自動切換過濾階段,進而降低能耗並延長濾芯壽命。與傳統離心風機相比,LG 的「潔淨增壓」渦流氣流可將 CADR 值提升 47%,並在更緊湊的機殼內實現相同的房間覆蓋率。 UV-C 和光催化模組仍然是昂貴的選配功能,每個模組售價 80 至 120 美元,限制了它們在 500 美元以下價位段的普及。未來有關 UV-C 照射的法規可能會進一步影響市場競爭格局,但目前尚未達成全球共識。
預計到2025年,獨立式空氣清淨機將佔據79.5%的市場。這主要是因為居住者和住宅更傾向於選擇價格在150美元至800美元之間的「即插即用」型解決方案。然而,管道式系統預計到2031年將以8.8%的複合年成長率成長,這一趨勢在偏好集中維護的商業設施中尤為明顯。一套價值2萬至4萬美元的管道式HEPA過濾器維修即可滿足5萬平方英尺辦公大樓的LEED通風率要求。相較之下,如果使用可攜式達到相同的覆蓋範圍,則需要50台設備,並且需要持續支付更換過濾器的人事費用。三星於2025年收購了Flakt集團,將其暖通空調業務拓展至淨化模組領域,目標客戶為醫院和機場。資料中心操作員採用管道式系統,將空氣中顆粒物濃度維持在 10µg/m³ 以下,以防止高密度伺服器過熱和短路。另一方面,在住宿設施和多用戶住宅中,房間的獨立控制和美觀性優先於運行整合,因此可攜式設備仍然是主流。
區域暖通空調(HVAC)普及率影響著這些趨勢。在北美和歐洲,中央空調已覆蓋約85%的商業建築,自然地推動了風管式解決方案的普及。相較之下,由於建築結構的多樣性,亞太地區對可攜式的需求依然強勁。然而,在北京、首爾和新加坡,新建的甲級辦公大樓擴大採用靜壓箱空間來安裝過濾器。能夠同時提供可攜式和風管式解決方案的供應商,更有能力應對專案的整個生命週期,從故障更換到滿足新建築的設計規格。
區域分析
預計到2025年,亞太地區將佔全球空氣清淨機市場銷售額的42.9%,並預計在2031年之前以8.5%的複合年成長率成長。這主要得益於都市區PM2.5濃度持續高企、半導體產業的積極投資、政府的空氣淨化計畫。中國環境保護部在2024年發布的報告顯示,有38個城市的空氣品質未達標,為穩定的家庭需求奠定了基礎。小米武漢工廠的年產能增加了700萬台,進一步增強了其在該地區的成本優勢。日本修訂了托幼機構的室內空氣品質(IAQ)指南,促進了高效能空氣微粒過濾器(HEPA過濾器)的安裝,從而形成了一個穩定的更換週期。
儘管銷售量較低,但北美地區正經歷政策主導的最快成長,這主要得益於LEED v4.1、ASHRAE 62.1標準以及《晶片法案》(CHIPS Act)的資金支持。在亞利桑那州、德克薩斯州和俄亥俄州,新建半導體工廠必須配備高效能空氣微粒過濾器(HEPA)/超高效空氣微粒過濾器(ULPA)基礎設施,這為企業對企業(B2B)領域帶來了大量訂單。加拿大新建築中68%的LEED認證採用率也印證了北美地區在統一室內空氣品質(IAQ)標準方面的進展。
在歐洲,即將生效的《建築能源性能指令》(EPBD)修正案預計於2027年正式確立室內空氣品質測量標準,這將加速德國、法國和北歐國家的採用。在中東,沙烏地阿拉伯和阿拉伯聯合大公國(阿拉伯聯合大公國)在應對氣候變遷方面的承諾推動了酒店業的維修工程,儘管規模較小,但仍實現了兩位數的成長。南美洲由於經濟波動和缺乏法規結構阻礙了相關標準的廣泛應用,因此落後於其他地區,但聖保羅和布宜諾斯艾利斯的空氣污染正在推動住宅銷售的逐步成長。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 市場分析與定義的前提條件
- 分析範圍
第2章 分析方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 新冠疫情後,以健康為中心的設備在東亞主要大都會圈的普及情況。
- 北美地區對商業房地產PM2.5含量製定了更嚴格的標準(LEED v4.1)
- 擴大美國和韓國的半導體無塵室生產能力
- 與歐盟和美國智慧家庭的融合正在推動對連網空氣清淨機的需求。
- 海灣合作理事會國家以ESG主導的飯店設施維修
- 印度國家清潔空氣計畫(NCAP)為公立學校的HEPA空氣清淨機提供補貼
- 市場限制因素
- 加州和日本對離子發生器的臭氧排放法規
- 東協大眾市場對濾芯更換成本高度敏感。
- 消費者對CADR標籤持懷疑態度-缺乏統一的測試規程
- 在大型辦公大樓中,暖通空調管道過濾器抑制了對獨立式過濾器的需求。
- 供應鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
第5章:預測市場規模與成長率
- 過濾技術
- HEPA
- 活性碳
- 離子/靜電沉澱器
- 紫外線C波段/光催化氧化
- 混合多層次系統
- 按類型
- 獨立式/可攜式
- 中央空調
- 透過連接功能
- 非智慧型(手動/類比)
- 相容於智慧/物聯網(應用程式和語音控制)
- 最終用戶
- 家用
- 商業用途(飯店和休閒、醫療設施和診所、教育機構、公司辦公室、零售)
- 工業(製造/倉儲、食品/飲料加工、製藥/無塵室、資料中心/伺服器機房)
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 英國
- 德國
- 法國
- 西班牙
- 北歐國家
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 東南亞國協
- 澳洲
- 其他亞太國家
- 南美洲
- 巴西
- 阿根廷
- 哥倫比亞
- 其他南美國家
- 中東和非洲
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 南非
- 埃及
- 其他中東和非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢(併購、聯盟、購電協議)
- 市場佔有率分析(主要公司的市場排名和佔有率)
- 公司簡介
- Daikin Industries Ltd
- Sharp Corporation
- Dyson Ltd
- Koninklijke Philips NV
- LG Electronics Inc.
- Panasonic Corporation
- Whirlpool Corporation
- Resideo Technologies Inc.
- Samsung Electronics Co. Ltd
- Xiaomi Corp.
- Honeywell International Inc.
- IQAir AG
- Coway Co. Ltd
- Winix Inc.
- Blueair AB
- AllerAir Industries Inc.
- Airdog(IAQ Tech)
- Austin Air Systems Ltd
- Kent RO Systems Ltd
- TruSens(ACCO Brands)
- Medify Air LLC
第7章 市場機會與未來展望
According to Mordor Intelligence, the air purifier market is expected to grow from USD 18.5 billion in 2025 to USD 20.04 billion in 2026 and is forecasted to reach USD 29.05 billion by 2031 at 7.71% CAGR over 2026-2031.
This report is Segmented by Filtration Technology (HEPA, Activated Carbon, Ionic/Electrostatic Precipitators, UV-C and Photocatalytic Oxidation, and Hybrid and Multi-Stage Systems), Type (Stand-Alone and In-Duct), Connectivity (Non-Smart and Smart/IoT-Enabled ), End User (Residential, Commercial, and Industrial), and Geography (North America, Europe, Asia-Pacific, South America, and Middle East and Africa).
Global Air Purifier Market Trends and Insights
Post-COVID Health-Centric Device Adoption in East Asian Metros
Persistent PM2.5 readings above national targets in Beijing, Seoul, and Tokyo have normalized year-round purifier ownership, extending the air purifier market beyond the pandemic spike. China's Ministry of Ecology and Environment confirmed that 38 of 168 monitored cities missed PM2.5 goals in 2024. Japan's health ministry updated indoor-air guidelines in 2024 to recommend HEPA filtration in childcare and eldercare facilities, institutionalizing a replacement cycle. Semiconductor engineers in South Korea, exposed to ultra-clean fabs, increasingly mirror workplace standards at home, creating a premium residential cohort. Xiaomi's RMB 2.5 billion smart-appliance factory opened in Wuhan in 2025, adding 7 million units of annual capacity that can flex between domestic and export orders. This combination of regulatory push and consumer pull solidifies a stable East-Asian demand base.
Stricter PM2.5 Commercial Real-Estate Standards in North America (LEED v4.1)
LEED v4.1's Indoor Environmental Quality credit mandates MERV 13 or higher filtration and continuous PM2.5 monitoring, compelling U.S. and Canadian building owners to retrofit or specify advanced purification from the design stage. Compliance budgets ranging from USD 50,000 to USD 150,000 for a 100,000-square-foot office are increasingly justified as tenants demand healthy-building certification for talent attraction and ESG reporting. ASHRAE 62.1-2022 further tightens outdoor-air ventilation rates, encouraging hybrid solutions that pair in-duct HEPA modules with portable units in meeting spaces. The Canada Green Building Council noted that 68% of new commercial projects sought LEED certification in 2025, signaling mainstream adoption. These standards are likely to cascade into Europe as revisions to the Energy Performance of Buildings Directive embed indoor-air metrics by 2027.
Ozone-Emission Restrictions on Ionizers in California & Japan
California's Air Resources Board capped ozone output from indoor cleaners at 0.050 ppm in 2024, effectively sidelining ionizer-centric designs. Japan's health ministry imposed parallel labeling rules in 2025 that limit ionizer sales in childcare facilities. Brands dependent on ionization, including Sharp and Panasonic, face USD 15-USD 25 per-unit redesign costs to meet thresholds, crimping margins in entry segments. The rule change funnels demand toward HEPA-pure or hybrid devices, benefiting competitors without ion emitters.
Other drivers and restraints analyzed in the detailed report include:
- Semiconductor Cleanroom Capacity Build-out in the US & South Korea
- Smart-Home Integration Pull for Connected Purifiers in EU & US
- High Filter Replacement Cost Sensitivity in ASEAN Mass Market
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
HEPA media captured 68.1% of the air purifier market share in 2025, favored for its 99.97% efficiency at 0.3 µm and endorsements from the U.S. EPA and WHO. Hybrid configurations that pair HEPA with activated carbon, UV-C, or photocatalytic oxidation are slated for a 9.3% CAGR because households and businesses now target VOCs, pathogens, and odors in a single chassis. Daikin's Streamer plasma module showed 99.9% SARS-CoV-2 inactivation in 2024 lab tests. Panasonic's nanoe X hydroxyl-radical generator is popular in Japan's eldercare market, where pathogen control ranks with particulate capture. Ionic precipitators retreat to niche industrial uses as ozone-cap rules in California and Japan tighten. Lack of harmonized efficacy standards for hybrid units, however, tempers adoption in risk-averse hospitals and pharmaceutical plants.
Hybrid systems also dovetail with smart-sensor arrays that trigger stage-specific filtration to curb energy draw and extend filter life. LG's Clean Booster vortex airflow increases CADR 47% over conventional centrifugal fans, enabling similar room coverage with smaller form factors. UV-C and photocatalytic modules remain premium add-ons costing USD 80-USD 120 per unit, limiting penetration below the USD 500 price tier. Prospective regulation around UV-C exposure could further shape the competitive field, but no global consensus exists yet.
Stand-alone devices accounted for 79.5% of the air purifier market volume in 2025 as renters and homeowners favored plug-and-play solutions priced between USD 150 and USD 800. Nevertheless, in-duct installations are scaling at an 8.8% CAGR through 2031, especially within commercial campuses that prefer centralized maintenance. A single in-duct HEPA retrofit costing USD 20,000-USD 40,000 can meet LEED air-change requirements for a 50,000-square-foot office, whereas equivalent coverage with portables would need 50 units and recurring labor for filter swaps. Samsung's 2025 acquisition of FlaktGroup extends its HVAC reach into purification modules that target hospitals and airports. Data-center operators adopt in-duct systems to keep airborne particulates below 10 µg/m3, protecting high-density servers from overheating or shorts. Portable units remain dominant in hospitality and multifamily housing, where room-specific control and aesthetics outweigh operational consolidations.
Regional HVAC penetration shapes these trends: North America and Europe, with about 85% central-HVAC adoption in commercial buildings, naturally migrate to in-duct solutions. By contrast, Asia-Pacific's heterogeneous building stock sustains portable demand, although new Grade-A offices in Beijing, Seoul, and Singapore are increasingly designed with built-in filtration plenum space. Suppliers that can package both portable and in-duct offerings stand to address the full project life cycle, from break-fix replacements to green-field architectural specs.
Complete Report Scope:
- By Filtration Technology
- HEPA
- Activated Carbon
- Ionic/Electrostatic Precipitators
- UV-Cand Photocatalytic Oxidation
- Hybrid and Multi-stage Systems
- By Type
- Stand-alone/Portable
- In-duct/Central HVAC
- By Connectivity
- Non-Smart (Manual/Analog)
- Smart/IoT-Enabled (App and Voice Controlled)
- By End User
- Residential
- Commercial (Hospitality and Leisure, Healthcare Facilities and Clinics, Educational Institutions and Corporate Offices and Retail)
- Industrial (Manufacturing and Warehousing, Food and Beverage Processing, Pharmaceuticals and Clean-rooms and Data Centers and Server Rooms)
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Spain
- Nordic Countries
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Egypt
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific generated 42.9% of 2025 revenue for the air purifier market and will climb at an 8.5% CAGR through 2031 on sustained urban PM2.5 levels, aggressive semiconductor investments, and government clean-air programs. China's environment ministry reported 38 non-attainment cities in 2024, underpinning stable household demand. Xiaomi's Wuhan factory adds 7 million units of annual output, reinforcing local cost advantages. Japan's updated childcare IAQ guidelines promote HEPA installations, creating steady replacement cycles.
North America, though smaller in unit volume, exhibits the fastest policy-driven acceleration as LEED v4.1, ASHRAE 62.1, and CHIPS Act funds converge. Semiconductor fabs under construction across Arizona, Texas, and Ohio mandate HEPA/ULPA infrastructure, pulling through significant B2B orders. Canada's 68% LEED adoption rate for new builds underscores continental alignment with IAQ standards.
Europe's forthcoming Energy Performance of Buildings Directive revision will formalize indoor-air metrics by 2027, driving uptake in Germany, France, and the Nordics. The Middle East leverages hospitality retrofits under Saudi and Emirati climate pledges, producing double-digit growth, albeit from a small base. South America trails as economic volatility and limited regulatory frameworks hamper widespread adoption, although pollution in Sao Paulo and Buenos Aires nudges incremental residential sales.
- Daikin Industries Ltd
- Sharp Corporation
- Dyson Ltd
- Koninklijke Philips N.V.
- LG Electronics Inc.
- Panasonic Corporation
- Whirlpool Corporation
- Resideo Technologies Inc.
- Samsung Electronics Co. Ltd
- Xiaomi Corp.
- Honeywell International Inc.
- IQAir AG
- Coway Co. Ltd
- Winix Inc.
- Blueair AB
- AllerAir Industries Inc.
- Airdog (IAQ Tech)
- Austin Air Systems Ltd
- Kent RO Systems Ltd
- TruSens (ACCO Brands)
- Medify Air LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Post-COVID Health-Centric Device Adoption in East Asian Metros
- 4.2.2 Stricter PM2.5 Commercial Real-Estate Standards in North America (LEED v4.1)
- 4.2.3 Semiconductor Clean-room Capacity Build-out in the US & South Korea
- 4.2.4 Smart-Home Integration Pull for Connected Purifiers in EU & US
- 4.2.5 ESG-Driven Hospitality Upgrades across GCC Countries
- 4.2.6 Indian NCAP Subsidies for HEPA Purifiers in Public Schools
- 4.3 Market Restraints
- 4.3.1 Ozone-Emission Restrictions on Ionizers in California & Japan
- 4.3.2 High Filter Replacement Cost Sensitivity in ASEAN Mass Market
- 4.3.3 Consumer Skepticism on CADR Claims-Lack of Unified Test Protocol
- 4.3.4 HVAC In-duct Filtration Diluting Stand-alone Unit Demand in Large Offices
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Filtration Technology
- 5.1.1 HEPA
- 5.1.2 Activated Carbon
- 5.1.3 Ionic/Electrostatic Precipitators
- 5.1.4 UV-Cand Photocatalytic Oxidation
- 5.1.5 Hybrid and Multi-stage Systems
- 5.2 By Type
- 5.2.1 Stand-alone/Portable
- 5.2.2 In-duct/Central HVAC
- 5.3 By Connectivity
- 5.3.1 Non-Smart (Manual/Analog)
- 5.3.2 Smart/IoT-Enabled (App and Voice Controlled)
- 5.4 By End User
- 5.4.1 Residential
- 5.4.2 Commercial (Hospitality and Leisure, Healthcare Facilities and Clinics, Educational Institutions and Corporate Offices and Retail)
- 5.4.3 Industrial (Manufacturing and Warehousing, Food and Beverage Processing, Pharmaceuticals and Clean-rooms and Data Centers and Server Rooms)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 United Kingdom
- 5.5.2.2 Germany
- 5.5.2.3 France
- 5.5.2.4 Spain
- 5.5.2.5 Nordic Countries
- 5.5.2.6 Russia
- 5.5.2.7 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 South Korea
- 5.5.3.5 ASEAN Countries
- 5.5.3.6 Australia
- 5.5.3.7 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Colombia
- 5.5.4.4 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 South Africa
- 5.5.5.4 Egypt
- 5.5.5.5 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Daikin Industries Ltd
- 6.4.2 Sharp Corporation
- 6.4.3 Dyson Ltd
- 6.4.4 Koninklijke Philips N.V.
- 6.4.5 LG Electronics Inc.
- 6.4.6 Panasonic Corporation
- 6.4.7 Whirlpool Corporation
- 6.4.8 Resideo Technologies Inc.
- 6.4.9 Samsung Electronics Co. Ltd
- 6.4.10 Xiaomi Corp.
- 6.4.11 Honeywell International Inc.
- 6.4.12 IQAir AG
- 6.4.13 Coway Co. Ltd
- 6.4.14 Winix Inc.
- 6.4.15 Blueair AB
- 6.4.16 AllerAir Industries Inc.
- 6.4.17 Airdog (IAQ Tech)
- 6.4.18 Austin Air Systems Ltd
- 6.4.19 Kent RO Systems Ltd
- 6.4.20 TruSens (ACCO Brands)
- 6.4.21 Medify Air LLC
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

 靜電空氣清淨機市場規模、佔有率和成長分析:按產品類型、應用、過濾技術、銷售管道和地區分類-2026-2033年產業預測
 空氣清淨機市場:全球預測,2026-2032年煙氣收集器和煙霧收集設備市場:2026-2032年全球市場預測(按產品類型、終端用戶產業、安裝配置、風量和濾材)
 空氣清淨機市場:按過濾技術和地區分類電子空氣清淨機和空氣清潔設備市場:依產品類型、技術、最終用戶和通路分類-2026-2032年全球市場預測空氣消毒淨化設備市場:依技術類型、產品類型、功能類型、最終用途和銷售管道分類-2026-2032年全球預測
 美國空氣清淨機市場:市場規模、佔有率和趨勢分析(按技術、銷售管道、類型、覆蓋範圍、應用和州分類),基於細分市場的預測(2026-2033 年)天花板式排煙系統市場:按過濾器類型、氣流、分配管道、應用和最終用戶產業分類,全球預測,2026-2032年
 光催化空氣清淨機市場分析及預測(至2035年):依類型、產品類型、技術、組件、應用、材質、設備、最終用戶及功能分類
 2026年全球空氣清淨機市場報告