


 |
市場調查報告書
商品編碼
2122261
網路流量分析:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Network Traffic Analysis - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
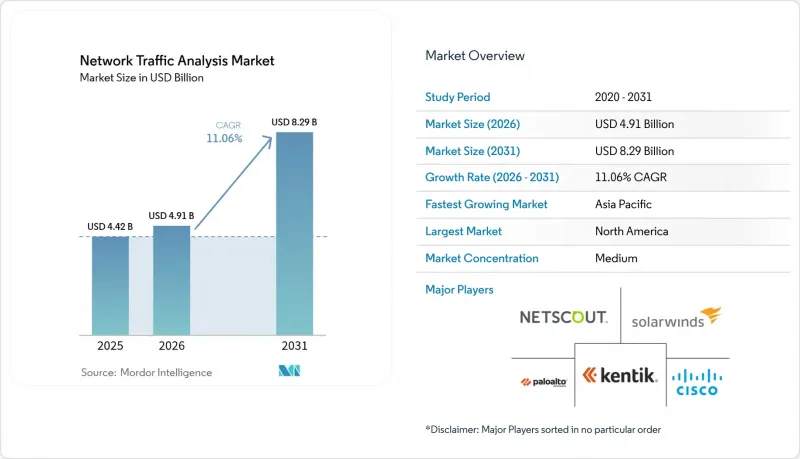
據 Mordor Intelligence 稱,網路流量分析市場預計到 2026 年價值 49.1 億美元,高於 2025 年的 44.2 億美元,預計到 2031 年將達到 82.9 億美元。
預計 2026 年至 2031 年的複合年成長率為 11.06%。
本報告按部署方式(本地部署、雲端部署、混合部署)、組件(解決方案和服務)、組織規模(大型企業和中小企業)、最終用戶行業(銀行、金融服務和保險 (BFSI)、IT 和電信、其他)以及地區進行細分。所有細分市場的規模和預測均以百萬美元為單位。
全球網路流量分析市場趨勢與洞察
NTA作為現代安全架構核心技術的崛起
70% 的進階持續性威脅 (APT) 依賴橫向機芯,而橫向移動主要可透過細粒度的流量分析來偵測。因此,安全團隊正在將網路流量分析 (NTA) 從「錦上添花」提升為「基礎控制機制」。透過將資料包分析與安全資訊和事件管理 (SIEM) 以及擴展資料偵測 (XDR) 緊密整合,與孤立工具相比,平均偵測時間最多可縮短 30%。此外,整合遙測功能可將關聯分析的工作量減少 40-50%,使少數分析師能夠專注於優先排序,而無需花費時間整理資料。提供開放 API 和雲端規模資料湖的供應商現在為許多零信任計劃提供支持,使 NTA 成為端點、身份驗證和雲端防禦的基礎架構。因此,「平台優先」的採購趨勢正在將預算從獨立探測器轉向整合的軟體即服務 (SaaS) 分析。
網路頻寬的擴展和 5G 的部署正在造成可視性差距。
向 5G 的過渡引入了超高密度小區、分散式用戶平面功能和多接取邊緣運算,這帶來了傳統分流器和鏡像連接埠無法應對的挑戰。光是在美國,預計到 2027 年,對私有 5G 網路的投資就將達到 37 億美元,但許多現有的監控協定堆疊無法處理容器化流量或在毫秒級偵測異常。服務供應商正與安全專家合作(T-Mobile 的 Prisma SASE 套餐就是一個顯著的例子),將網路切片和線上威脅偵測結合。物聯網的普及進一步加重了分析引擎的負擔,因為基於特徵碼的工具無法跟上各種設備的行為,這增加了對行為分析和基於機器學習 (ML) 模型的需求。
威脅的快速演變和加密技術的進步,超過了工具的演變速度。
TLS 1.3 加密了 95% 的網路流量並模糊了元資料,使得傳統的深層封包檢測(DPI) 技術失效。 「加密客戶端 Hello」和「0-RTT 恢復」等特性迫使廠商轉向基於時間、序列長度和流量形態的側通道推斷技術。諸如多實例加密流量變壓器之類的研究原型可以達到 99% 的分類準確率,但需要 GPU 層級的處理能力和大多數 IT 團隊所缺乏的資料科學專業知識。小規模廠商難以承受研發成本的重壓,可能導致其退出市場或被收購。
細分市場分析
預計到 2025 年,雲端部署將佔總營收的 50.76%,凸顯了企業對高彈性 SaaS 分析的偏好,這種分析方式可以將資本支出 (CapEx) 轉化為營運成本 (OpEx)。混合模式正在推動成長,隨著企業將傳統資料中心與 AWS、Azure 或 GCP 環境整合,預計到 2031 年,其年複合成長率(CAGR)將達到 13.53%。這種組合既能保持雲端敏捷性,又能確保符合資料居住法規。 Zscaler 的流量擷取服務展示了將原始流量從雲端平台匯出到分析管道的能力,而不會佔用過多本地擷取裝置資源。
採用混合架構的公司報告稱,由於集中式升級部署,硬體更新成本降低,新檢測功能的部署速度也更快。雖然本地探測器在空氣間隙環境和高度監管的行業中仍然使用,但隨著監管機構採用基於雲端的認證框架,它們在網路流量分析市場的佔有率正在穩步下降。因此,混合架構的採用正在推動網路流量分析市場的整體擴張,並吸引了以前缺乏企業級工具的新興中型企業加入。
到2025年,解決方案(包括設備、虛擬感測器和SaaS主機)將佔據網路流量分析市場規模的61.85%。然而,隨著企業將監控和事件回應外包,服務業正以14.32%的複合年成長率快速擴張。 OPSWAT收購InQuest表明,供應商正在將深度文件偵測和威脅情報與託管服務相結合,以滿足聯邦政府部門的需求。
採用託管服務是解決分析師短缺和產品複雜性的有效方案。服務提供者提供全天候支援、精選威脅情報和自動化隔離功能,從而推動了資源受限企業的採用。在超過 100 Gbps 的骨幹網路中,硬體感測器仍然發揮著至關重要的作用,基於 FPGA 的高速處理性能仍然優於虛擬設備。供應商正日益將這些感測器定位為“數據轉發器”,為雲端分析提供數據。
區域分析
受嚴格的隱私法、早期採用零信任架構以及高額網路安全預算的推動,北美預計將在2025年佔全球收入的33.62%。摩根大通的AI驅動型詐欺偵測系統清晰地展現了該地區對資料包驅動分析的需求,該技術可將威脅識別速度提升300倍,每年節省2億美元。各州政府也在積極擁抱可觀測性;印第安納州在其多重雲端基礎設施中實施流量分析後,顯著提升了公民服務水準。亞太地區是高速成長的驅動力,年複合成長率高達14.08%。中國、印度和韓國的大規模5G部署,以及對智慧城市的投資和日益猖獗的勒索軟體攻擊,都在推動網路流量分析(NTA)的普及。中國《網路安全法》和澳洲《關鍵基礎設施法》等地方法規強制要求進行流量日誌記錄和異常檢測。使用專用蜂巢式網路實現生產基地數位轉型的製造商需要精細化的監控,才能安全地實現營運技術(OT)和資訊技術(IT)的整合。
在歐洲,由於GDPR的資料外洩通知要求以及強制演算法透明度的AI相關新法規,市場需求仍然強勁。主權雲端計畫正在推動混合部署,將資料包限制在特定區域內,這使得能夠提供精細資料居住管理的供應商受益。拉丁美洲、中東和非洲仍在發展中,但潛力巨大。巴西的銀行、沙烏地阿拉伯的智慧城市計畫以及南非的電信業者正在試行AI驅動的NTA(網路終端分析),以應對日益嚴格的網路安全法規。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- NTA作為現代安全架構核心技術的崛起
- 網路頻寬的擴展和 5G 的部署正在造成可視性差距。
- 向雲端混合架構的轉變正在推動對雲端原生網路終端應用(NTA)的需求不斷成長。
- 對加密流量進行機器學習 (ML) 檢查的要求
- 零信任機制導致東西向通訊量激增。
- 透過 SOC 的整合促進 NTA 和 NDR 的整合。
- 市場限制因素
- 威脅的快速演變和加密技術的進步,超過了工具的演變速度。
- 熟練分析師短缺和解決方案高度複雜。
- 資料隱私法規限制了深層封包檢測
- 將預算重新分配給終端 XDR 工具
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 產業吸引力—五力分析
- 新進入者的威脅
- 買方的議價能力
- 供應商的議價能力
- 替代品的威脅
- 競爭公司之間的競爭
- 宏觀經濟因素對市場的影響
第5章 市場規模與成長預測
- 不同的發展
- 現場
- 基於雲端的
- 混合
- 按組件
- 解決方案
- 硬體設備
- 虛擬設備
- SaaS平台
- 服務
- 專業服務
- 託管服務
- 解決方案
- 按組織規模
- 大公司
- 中小企業
- 按最終用戶行業分類
- BFSI
- 資訊科技/通訊
- 政府/國防
- 能源與公共產業
- 零售與電子商務
- 醫療保健和生命科學
- 製造業
- 其他
- 透過使用
- 安全和威脅偵測
- 效能監控和最佳化
- 合規措施的實施
- 產能規劃與預測
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 智利
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 馬來西亞
- 新加坡
- 澳洲
- 其他亞太國家
- 中東和非洲
- 中東
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 其他非洲地區
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- NETSCOUT Systems Inc.
- Cisco Systems Inc.
- Palo Alto Networks Inc.
- SolarWinds Corporation
- Kentik Technologies Inc.
- Dynatrace LLC
- ExtraHop Networks Inc.
- Flowmon Networks AS(Progress)
- GreyCortex sro
- Genie Networks Ltd.
- ManageEngine(Zoho Corp.)
- Plixer LLC
- Nagios Enterprises LLC
- Gigamon Inc.
- Corelight Inc.
- Vectra AI Inc.
- Ixia(Keysight Technologies Inc.)
- Riverbed Technology LLC
- Nozomi Networks Inc.
- Nokia Corporation
第7章 市場機會與未來趨勢
- 評估閒置頻段和未滿足的需求
According to Mordor Intelligence, network traffic analysis market size in 2026 is estimated at USD 4.91 billion, growing from 2025 value of USD 4.42 billion with 2031 projections showing USD 8.29 billion, growing at 11.06% CAGR over 2026-2031.
This report is Segmented by Deployment (On-Premise, Cloud-Based, and Hybrid), Component (Solutions and Services), Organization Size (Large Enterprises and Small and Medium Enterprises), End-User Industry (BFSI, IT and Telecom, and More), and Geography. The Market Sizes and Forecasts are Provided in Value (in USD Million) for all the Above Segments.
Global Network Traffic Analysis Market Trends and Insights
Emergence of NTA as Cornerstone in Modern Security Stacks
Seventy percent of advanced persistent threats rely on lateral movement, detectable primarily through granular traffic analytics, prompting security teams to elevate NTA from a nice-to-have tool to a foundational control. Tightly coupling packet analytics with SIEM and XDR cuts mean time to detect by up to 30% relative to siloed tools. Unified telemetry also trims correlation workloads 40-50%, freeing scarce analysts to focus on triage rather than data wrangling. Vendors that deliver open APIs and cloud-scale data lakes now underpin many zero-trust programs, positioning NTA as the fabric that underlies endpoint, identity, and cloud defenses. As a result, platform-first buying behavior is shifting budget from stand-alone probes toward integrated SaaS analytics.
Expanding Network Bandwidth and 5G Rollouts Create Visibility Gaps
The jump to 5G introduces ultra-dense cells, distributed user-plane functions, and multi-access edge computing that overwhelm classic taps and span ports. Private 5G outlays in the United States alone are expected to hit USD 3.7 billion by 2027, yet most existing monitoring stacks cannot ingest containerized traffic or detect millisecond-scale anomalies. Service providers partner with security specialists-T-Mobile's Prisma SASE bundle is a notable example-to pair network slicing with inline threat detection. IoT proliferation further stresses analytics engines because signature-based tools falter against diverse device behaviors, fueling demand for behavior and ML-centric models.
Rapid Evolution of Threats and Encryption Outpacing Tooling
TLS 1.3 encrypts 95% of web traffic and conceals handshake metadata, thwarting legacy DPI. Features such as Encrypted ClientHello and 0-RTT resumption force vendors to pivot toward side-channel inference that relies on timing, sequence lengths, and traffic morphologies. Research prototypes like multi-instance encrypted traffic transformers hit 99% classification accuracy but demand GPU-class horsepower and data science talent that most IT teams lack. Smaller suppliers struggle with R&D costs, creating potential attrition or acquisition.
Other drivers and restraints analyzed in the detailed report include:
- Migration to Cloud and Hybrid Architectures Boosts Demand for Cloud-Native NTA
- Zero-Trust East-West Traffic Proliferation
- Shortage of Skilled Analysts and High Solution Complexity
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Cloud deployments controlled 50.76% of 2025 revenue, underscoring preference for elastic SaaS analytics that shift capex to opex. The hybrid model is the growth pacesetter, registering a 13.53% CAGR through 2031 as enterprises knit legacy data centers with AWS, Azure, or GCP estates. That blend ensures compliance with data-residency rules while sustaining cloud agility. Zscaler's Traffic Capture service showcases how cloud platforms can export raw traffic to analytics pipelines without saturating on-premises capture appliances.
Enterprises adopting hybrid architectures report lower hardware refresh spend and faster rollout of new inspection features because upgrades are deployed centrally. On-premises probes persist in air-gapped or highly regulated verticals, yet their share of the network traffic analysis market steadily recedes as regulations embrace cloud certification frameworks. Hybrid adoption consequently propels overall network traffic analysis market expansion into greenfield midsize companies that lacked enterprise-class tooling.
Solutions-appliances, virtual sensors, and SaaS consoles-represented 61.85% of the network traffic analysis market size in 2025. However, services are scaling at 14.32% CAGR as organizations offload monitoring and incident response. OPSWAT's buyout of InQuest illustrates how vendors bundle Deep File Inspection and threat intel with managed offerings to address federal-sector needs.
Managed service uptake is a pragmatic response to analyst scarcity and product complexity. Providers supply 24/7 coverage, curated threat feeds, and automated containment, boosting adoption among resource-constrained firms. Hardware sensors retain relevance in 100 Gbps-plus backbones where FPGA acceleration still outperforms virtual appliances. Even so, vendors increasingly position those sensors as data forwarders feeding cloud analytics.
Complete Report Scope:
- By Deployment
- On-premise
- Cloud-based
- Hybrid
- By Component
- Solutions
- Hardware Appliances
- Virtual Appliances
- SaaS Platform
- Services
- Professional Services
- Managed Services
- Solutions
- By Organization Size
- Large Enterprises
- Small and Medium Enterprises (SMEs)
- By End-user Industry
- BFSI
- IT and Telecom
- Government and Defense
- Energy and Utilities
- Retail and E-commerce
- Healthcare and Life Sciences
- Manufacturing
- Other End-user Industries
- By Application
- Security and Threat Detection
- Performance Monitoring and Optimization
- Compliance and Policy Enforcement
- Capacity Planning and Forecasting
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Malaysia
- Singapore
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America contributed 33.62% of 2025 revenue thanks to strict privacy statutes, early zero-trust adoption, and high cybersecurity budgets. JPMorgan's AI-infused fraud system illustrates regional appetite for packet-driven analytics that accelerate threat identification 300-fold and save USD 200 million annually. State governments likewise embrace observability; Indiana improved citizen services after deploying traffic analytics across multi-cloud infrastructure. Asia-Pacific is the high-growth engine with a 14.08% CAGR. Massive 5G rollouts in China, India, and South Korea, combined with smart-city investments and rising ransomware incidents, spur NTA adoption. Local regulations such as China's Cybersecurity Law and Australia's Critical Infrastructure Act compel traffic logging and anomaly detection. Manufacturers digitizing shop floors with private cellular networks need granular monitoring to secure OT and IT convergence.
Europe maintains robust demand owing to GDPR's breach notification requirements and emerging AI legislation that mandates algorithmic transparency. Sovereign-cloud initiatives push hybrid deployments so packets stay in-region, benefitting vendors that provide fine-grained data-residency controls. Latin America and the Middle East and Africa remain nascent but promising: Brazilian banks, Saudi smart-city projects, and South African telcos are piloting AI-fueled NTA in anticipation of stricter cyber mandates.
- NETSCOUT Systems Inc.
- Cisco Systems Inc.
- Palo Alto Networks Inc.
- SolarWinds Corporation
- Kentik Technologies Inc.
- Dynatrace LLC
- ExtraHop Networks Inc.
- Flowmon Networks A.S. (Progress)
- GreyCortex s.r.o.
- Genie Networks Ltd.
- ManageEngine (Zoho Corp.)
- Plixer LLC
- Nagios Enterprises LLC
- Gigamon Inc.
- Corelight Inc.
- Vectra AI Inc.
- Ixia (Keysight Technologies Inc.)
- Riverbed Technology LLC
- Nozomi Networks Inc.
- Nokia Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Emergence of NTA as cornerstone in modern security stacks
- 4.2.2 Expanding network bandwidth and 5G rollouts create visibility gaps
- 4.2.3 Migration to cloud and hybrid architectures boosts demand for cloud-native NTA
- 4.2.4 Encrypted traffic ML-based inspection requirements
- 4.2.5 Zero-trust east-west traffic proliferation
- 4.2.6 SOC consolidation pushing NTA/NDR convergence
- 4.3 Market Restraints
- 4.3.1 Rapid evolution of threats and encryption outpacing tooling
- 4.3.2 Shortage of skilled analysts and high solution complexity
- 4.3.3 Data-privacy regulations restricting deep packet inspection
- 4.3.4 Budget reallocation toward endpoint/XDR tools
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Industry Attractiveness - Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Deployment
- 5.1.1 On-premise
- 5.1.2 Cloud-based
- 5.1.3 Hybrid
- 5.2 By Component
- 5.2.1 Solutions
- 5.2.1.1 Hardware Appliances
- 5.2.1.2 Virtual Appliances
- 5.2.1.3 SaaS Platform
- 5.2.2 Services
- 5.2.2.1 Professional Services
- 5.2.2.2 Managed Services
- 5.2.1 Solutions
- 5.3 By Organization Size
- 5.3.1 Large Enterprises
- 5.3.2 Small and Medium Enterprises (SMEs)
- 5.4 By End-user Industry
- 5.4.1 BFSI
- 5.4.2 IT and Telecom
- 5.4.3 Government and Defense
- 5.4.4 Energy and Utilities
- 5.4.5 Retail and E-commerce
- 5.4.6 Healthcare and Life Sciences
- 5.4.7 Manufacturing
- 5.4.8 Other End-user Industries
- 5.5 By Application
- 5.5.1 Security and Threat Detection
- 5.5.2 Performance Monitoring and Optimization
- 5.5.3 Compliance and Policy Enforcement
- 5.5.4 Capacity Planning and Forecasting
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Chile
- 5.6.2.4 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Russia
- 5.6.3.7 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 India
- 5.6.4.3 Japan
- 5.6.4.4 South Korea
- 5.6.4.5 Malaysia
- 5.6.4.6 Singapore
- 5.6.4.7 Australia
- 5.6.4.8 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 United Arab Emirates
- 5.6.5.1.2 Saudi Arabia
- 5.6.5.1.3 Turkey
- 5.6.5.1.4 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Nigeria
- 5.6.5.2.3 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 NETSCOUT Systems Inc.
- 6.4.2 Cisco Systems Inc.
- 6.4.3 Palo Alto Networks Inc.
- 6.4.4 SolarWinds Corporation
- 6.4.5 Kentik Technologies Inc.
- 6.4.6 Dynatrace LLC
- 6.4.7 ExtraHop Networks Inc.
- 6.4.8 Flowmon Networks A.S. (Progress)
- 6.4.9 GreyCortex s.r.o.
- 6.4.10 Genie Networks Ltd.
- 6.4.11 ManageEngine (Zoho Corp.)
- 6.4.12 Plixer LLC
- 6.4.13 Nagios Enterprises LLC
- 6.4.14 Gigamon Inc.
- 6.4.15 Corelight Inc.
- 6.4.16 Vectra AI Inc.
- 6.4.17 Ixia (Keysight Technologies Inc.)
- 6.4.18 Riverbed Technology LLC
- 6.4.19 Nozomi Networks Inc.
- 6.4.20 Nokia Corporation
7 MARKET OPPORTUNITIES AND FUTURE TRENDS
- 7.1 White-Space and Unmet-Need Assessment

 2026年全球網路流量分析市場報告2026年全球網路流量分析解決方案市場報告
 2026-2030年全球組織網路分析工具市場
 網路流量分析解決方案市場分析及預測(至2035年):按類型、產品類型、服務、技術、組件、應用、流程、部署類型和最終用戶分類
 網路流量分析解決方案市場 - 全球產業規模、佔有率、趨勢、機會、預測:按部署類型、用戶類型、最終用戶、地區和競爭對手分類,2021-2031 年
 網路流量分析市場規模、佔有率和成長分析(按組件、部署類型、組織規模、最終用戶產業和地區分類)-2026-2033年產業預測網路流量分析市場 - 全球產業規模、佔有率、趨勢、機會和預測,按組件、部署模式、組織規模、最終用戶、地區和競爭格局細分,2020-2030 年預測
 網路流量分析市場規模、佔有率、趨勢分析報告:按組件、部署、組織規模、行業垂直、地區和細分市場進行預測,2025 年至 2030 年