


 |
市場調查報告書
商品編碼
2121916
熱塑性聚氨酯(TPU):市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Thermoplastic Polyurethane (TPU) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
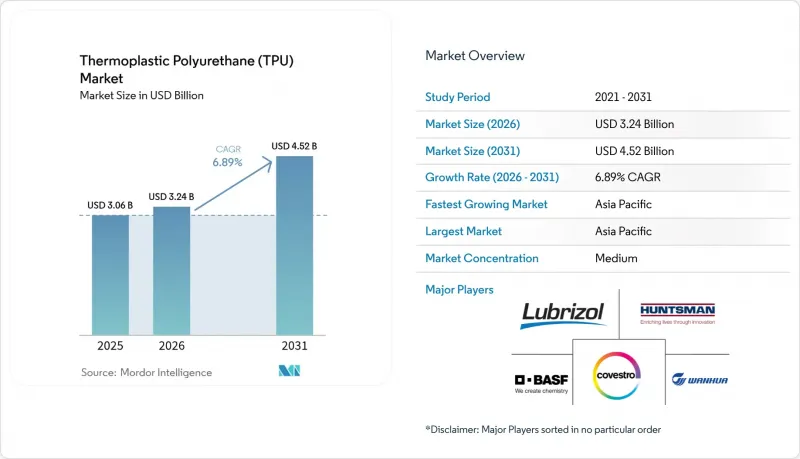
根據 Mordor Intelligence 預測,熱塑性聚氨酯 (TPU) 市場預計將從 2025 年的 30.6 億美元成長到 2026 年的 32.4 億美元,到 2031 年達到 45.2 億美元,2026 年至 2031 年的複合成長率預計為 6.89%。
本報告按產品類型(聚酯TPU、聚醚TPU、聚己內酯TPU)、應用領域(擠出產品、射出成型產品、黏合劑及其他)、終端用戶產業(鞋類、汽車及其他)和地區(亞太地區、北美地區、歐洲地區、南美地區、中東和非洲地區)對市場進行細分。市場預測以美元計價。
全球熱塑性聚氨酯(TPU)市場趨勢與洞察
穿戴式醫療設備正在推動對醫用級TPU的需求。
連續血糖監測儀和智慧型心臟貼片的市場規模已達400億美元。這些產品需要超過30兆帕的拉伸強度,並且需要完全檢驗ISO 10993標準。聚醚基TPU因其卓越的耐水解性而佔據市場主導地位。雅培的FreeStyle Libre 3採用了一種客製化的聚醚基TPU,其延伸率超過500%,足以承受反覆彎曲。設備製造商會在樹脂中添加2-5%的抗菌母粒,這會使樹脂成本增加約15%,但作為II類產品,可以實現高價銷售。小規模加工商難以資金籌措,市場佔有率主要集中在提供合約配製和法規文件服務的垂直整合型樹脂供應商手中。
3D列印耗材和粉末正在加速原型製作的普及。
到2025年,積層製造將消耗12,000噸TPU,包括長絲和粉末。汽車產業的一級供應商正在將原型前置作業時間從12週縮短至48小時,並採用晶格結構來調節碰撞過程中的能量吸收。BASF的Ultrasint TPU 88A透過引入疏水處理並將粉末保存期限延長至12個月,解決了與潮濕相關的問題。鞋類品牌正在利用3D列印技術製造中底,重量減輕約20%,回彈保持率超過55%。對潮濕的敏感度仍然是一個主要的技術挑戰;如果列印前長絲的含水量沒有乾燥到0.02%以下,就會形成蒸氣。
1,4-BDO 原料價格波動導致聚酯/醚基 TPU 價格上漲。
2024年至2025年間,亞洲現貨價格在每噸1,800美元至2,400美元之間波動,導致非垂直整合型生產商的毛利率下降4至6個百分點。BASF和萬華受益於其後向整合的BDO產能,使其合約價格免受現貨價格波動的影響。中小生產者正轉向聚己內酯基TPU配方,但必須接受拉伸強度下降的現實。產能集中在中國,佔全球名義BDO產能的68%,但電力發行可能導致工廠在未事先通知的情況下運作。
細分市場分析
預計到2025年,聚酯TPU將佔銷售額的40.65%,並有望維持穩定的成長勢頭,這主要得益於其機械強度和成本優勢的平衡。聚己內酯TPU的成長率為7.92%,儘管產量較低,但這主要是由於品牌商開始採用可堆肥包裝。醫用級聚醚TPU已通過ISO 10993認證,因此不受價格壓力的影響。含有再生材料的聚酯級產品,例如含有25%再生粉碎工業廢棄物的Desmopan 2590A,在滿足自願性永續性目標的同時,並未降低硬度。己二酸原料仍集中在中國,這造成了供應風險溢價,可能削弱通用聚酯的長期成本優勢。
基於聚己內酯 (PCA) 的熱塑性聚氨酯 (TPU) 由於依賴單體供應,其生產規模受到限制,全球產能不到 15 萬噸。然而,其生物分解性彌補了其在臨時性整形外科植入等應用中的表現不足。無溶劑水性 TPU 分散體在塗料領域備受關注。這些分散體的 VOC 含量低於 50 g/L,符合 CARB 1168 標準,使其在北美建築塗料市場具有廣泛的應用前景。
區域分析
預計到2025年,亞太地區將佔全球銷售額的58.72%,並將在2031年之前維持7.75%的複合年成長率。在中國,醫用級樹脂的在地化生產正在穩步推進,萬華、山東英諾和米拉克爾等公司在鞋類和汽車產業集群附近經營綜合性生產基地。印度的生產連結獎勵計畫計畫(PLI)為鞋類樹脂投資提供15%的資本補貼,但本地產能仍有限,迫使依賴進口,導致進口成本增加了18%。日本和韓國正專注於高階室內裝潢低VOC水性分散體,而東南亞國協提供勞力密集的鞋類組裝,但缺乏大規模的混煉設備。
北美市場佔有率得益於墨西哥一級汽車零件供應商在美墨加協定(USMCA)法規下的支持。預計2025年FDA核准14種TPU基醫療設備將持續推動聚醚的需求。在加拿大,TPU被用於低坡度屋頂的防水膜,以承受-40 度C以下的溫差循環。在歐洲,由於符合REACH法規中關於二異氰酸酯的訓練要求,BASF、科思創和亨斯邁的供應較為集中。在德國,生物基TPU被指定用於電動車內飾,而在北歐的體育場館中,半透明TPU膜被用於50米無柱跨度的防水工程。
在南美、中東和非洲,儘管巴西的鞋類出口不斷成長,但國內樹脂產量不足,因此必須從亞洲進口。在沙烏地阿拉伯,作為一項價值5000億美元的基礎設施建設計畫的一部分,體育場館的屋頂正在使用TPU膜材,這些體育場館的日間溫度超過50度C。BASF位於阿布達比的工廠(年產能2.5萬噸)將於2024年開始向該地區供貨,以滿足海灣合作理事會(GCC)國家建築和汽車行業的需求。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 穿戴式醫療設備正在推動對醫用級TPU的需求。
- 3D列印耗材和粉末正在加速原型製作的普及。
- 採用生物基材料製成的單一材料鞋類項目正在促進消費。
- 軟性太陽能電池和建築薄膜材料中PVC向TPU的過渡
- 無溶劑反應擠出等級材料,可用於電動車的套模內裝飾。
- 市場限制因素
- 1,4-BDO 原料價格的波動推高了聚酯/醚基 TPU 的價格。
- 加強異氰酸酯暴露監管
- 在汽車應用中,以高耐熱性TPEE和TPV取代有風險
- 價值鏈分析
- 波特五力模型
第5章 市場規模與成長預測
- 依產品類型
- 聚酯TPU
- 聚醚TPU
- 聚己內酯TPU
- 透過使用
- 擠壓產品
- 射出成型產品
- 黏合劑
- 其他
- 按最終用途行業分類
- 鞋類
- 車
- 醫療保健
- 電氣和電子設備
- 建造
- 重工業
- 其他
- 按地區
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 東南亞國協
- 其他亞太國家
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 北歐的
- 其他歐洲國家
- 南美洲
- 巴西
- 阿根廷
- 智利
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 南非
- 其他中東和非洲國家
- 亞太地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率和排名分析
- 公司簡介
- BASF
- Avient Corporation
- Coim Group
- Covestro AG
- Dongsung
- Epaflex Polyurethanes SpA
- Hexpol AB
- Huntsman International LLC
- Miracll Chemicals Co. Ltd
- Mitsui Chemicals Inc.
- Novotex Italiana SpA
- Sumei Chemical Co. Ltd
- Suzhou Austen New Mstar Technology Ltd
- Taiwan PU Corporation
- The Lubrizol Corporation
- Tosoh Corporation
- Trinseo
- Wanhua Chemical Group Co. Ltd
第7章 市場機會與未來展望
According to Mordor Intelligence, the thermoplastic polyurethane market size is expected to increase from USD 3.06 billion in 2025 to USD 3.24 billion in 2026 and reach USD 4.52 billion by 2031, growing at a CAGR of 6.89% over 2026-2031.
This report Segments the Industry by Product Type (Polyester TPU, Polyether TPU, and Polycaprolactone TPU), Application (Extruded Products, Injection Molded Products, Adhesives, and Others), End-User Industry (Footwear, Automotive, and More), and Geography (Asia-Pacific, North America, Europe, South America, and the Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Thermoplastic Polyurethane (TPU) Market Trends and Insights
Wearable Medical Devices Driving Medical-Grade TPU Demand
Continuous glucose monitors and smart cardiac patches have reached an installed base worth USD 40 billion. They require tensile strength above 30 MPa and full ISO 10993 validation. Polyether TPU dominates due to superior hydrolysis resistance. Abbott's FreeStyle Libre 3 adopted a custom polyether grade with elongation beyond 500% to withstand flex cycling. Device makers add antimicrobial masterbatches at 2-5%, raising resin cost by about 15% yet enabling premium pricing for Class II products. Smaller converters struggle to finance clean-room facilities, concentrating share with vertically integrated resin suppliers that provide toll compounding and regulatory dossiers.
3D-Printing Filaments and Powders Accelerating Prototyping Adoption
Additive manufacturing consumed 12,000 t of TPU in 2025, split between filament and powder. Automotive Tier-1s reduce prototype lead time from 12 weeks to 48 hours and apply lattice structures that tune crash energy absorption. BASF's Ultrasint TPU 88A introduced a hydrophobic treatment that extends powder shelf life to 12 months, solving moisture-uptake failures. Footwear brands print midsoles with weight savings near 20% and rebound retention above 55%. Moisture sensitivity remains the primary technical hurdle; filament must be dried to below 0.02% moisture prior to printing, or steam voids appear.
1,4-BDO Feedstock Volatility Inflating Polyester/Ether TPU Prices
Asian spot values fluctuated between USD 1,800 and USD 2,400 t in 2024-2025, taking 4-6 percentage points off gross margin for non-integrated producers. BASF and Wanhua benefit from backward-integrated BDO capacity that shields contracts from spot swings. Smaller players reformulate toward polycaprolactone TPU but accept lower tensile strength. Capacity is concentrated in China, which holds 68 % of the global BDO nameplate; power rationing can idle plants without notice.
Other drivers and restraints analyzed in the detailed report include:
- Bio-Based Mono-Material Footwear Programs Boosting Consumption
- PVC-to-TPU Shift in Flexible Solar and Architectural Membranes
- Tightening Isocyanate-Exposure Regulations
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Polyester TPU delivered 40.65% of 2025 revenue and will maintain a healthy trajectory given balanced mechanical strength and cost edge. Polycaprolactone TPU, while small in volume, is expanding at a 7.92% rate as brands adopt compostable packaging. Medical-grade polyether TPU secures ISO 10993 approvals, insulating it from price pressure. Recycled-content polyester grades, including Desmopan 2590A with 25 % post-industrial regrind, meet voluntary sustainability targets without impacting hardness. Adipic-acid feedstock remains concentrated in China, creating supply-risk premiums that could erode the long-run cost advantage of commodity polyester.
Polycaprolactone TPU relies on a monomer base below 150 kt global capacity, constraining scale. Yet in applications such as temporary orthopedic implants, its biodegradability offsets performance gaps. Waterborne TPU dispersions that eliminate solvents are gaining traction in coatings. These dispersions contain less than 50 g/L VOC and comply with CARB 1168, positioning them for architectural coatings across North America.
Complete Report Scope:
- By Product Type
- Polyester TPU
- Polyether TPU
- Polycaprolactone TPU
- By Application
- Extruded Products
- Injection Molded Products
- Adhesives
- Other Applications
- By End-Use Industry
- Footwear
- Automotive
- Medical
- Electrical & Electronics
- Construction
- Heavy Engineering
- Other End-user Industries
- By Geography
- Asia Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Nordics
- Rest of Europe
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Rest of Middle East and Africa
- Asia Pacific
Geography Analysis
Asia-Pacific represented 58.72 % of 2025 revenue and is projected to post a 7.75% CAGR to 2031. China localizes medical-grade resin, with Wanhua, Shandong INOV, and Miracll operating integrated complexes near footwear and automotive clusters. India's Production-Linked Incentive offers 15 % capital subsidy for footwear resin investments, yet local capacity remains thin, forcing imports that lift landed cost by 18 %. Japan and South Korea focus on low-VOC waterborne dispersions for premium interiors, while ASEAN countries supply labor-intensive footwear assembly but lack sizable compounding assets.
North America's market share is buoyed by USMCA rules boosting Mexican Tier-1 automotive suppliers. FDA clearances for 14 TPU-based medical devices in 2025 sustain polyether uptake. Canadian low-slope roofing membranes use TPU for thermal cycling below -40°C. In Europe, compliance with REACH diisocyanate training consolidates volumes among BASF, Covestro, and Huntsman. Germany specifies bio-based TPU for EV interiors, while Nordic arenas adopt translucent TPU membranes for 50-meter column-free spans.
In South America, and Middle East & Africa, Brazil's footwear exports grow, yet domestic resin output is inadequate, mandating Asian imports. Saudi Arabia's USD 500 billion infrastructure pipeline pulls TPU membranes for stadium roofs where daytime highs top 50°C. BASF's Abu Dhabi plant at 25 kt begins regional supply in 2024, serving Gulf Cooperation Council construction and automotive demand.
- BASF
- Avient Corporation
- Coim Group
- Covestro AG
- Dongsung
- Epaflex Polyurethanes SpA
- Hexpol AB
- Huntsman International LLC
- Miracll Chemicals Co. Ltd
- Mitsui Chemicals Inc.
- Novotex Italiana SpA
- Sumei Chemical Co. Ltd
- Suzhou Austen New Mstar Technology Ltd
- Taiwan PU Corporation
- The Lubrizol Corporation
- Tosoh Corporation
- Trinseo
- Wanhua Chemical Group Co. Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Wearable Medical Devices Driving Medical-Grade TPU Demand
- 4.2.2 3D-Printing Filaments & Powders Accelerating Prototyping Adoption
- 4.2.3 Bio-Based Mono-Material Footwear Programs Boosting Consumption
- 4.2.4 PVC-to-TPU Shift in Flexible Solar & Architectural Membranes
- 4.2.5 Solvent-Free Reactive Extrusion Grades Enabling In-Mold EV Interior Decoration
- 4.3 Market Restraints
- 4.3.1 1,4-BDO Feedstock Volatility Inflating Polyester/Ether TPU Prices
- 4.3.2 Tightening Isocyanate-Exposure Regulations
- 4.3.3 Displacement Risk from High-Heat TPEE & TPV in Automotive Applications
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Polyester TPU
- 5.1.2 Polyether TPU
- 5.1.3 Polycaprolactone TPU
- 5.2 By Application
- 5.2.1 Extruded Products
- 5.2.2 Injection Molded Products
- 5.2.3 Adhesives
- 5.2.4 Other Applications
- 5.3 By End-Use Industry
- 5.3.1 Footwear
- 5.3.2 Automotive
- 5.3.3 Medical
- 5.3.4 Electrical & Electronics
- 5.3.5 Construction
- 5.3.6 Heavy Engineering
- 5.3.7 Other End-user Industries
- 5.4 By Geography
- 5.4.1 Asia Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Nordics
- 5.4.3.7 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Chile
- 5.4.4.4 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 South Africa
- 5.4.5.4 Rest of Middle East and Africa
- 5.4.1 Asia Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global & Market Overview, Core Segments, Financials, Strategy, Products, Recent Developments)
- 6.4.1 BASF
- 6.4.2 Avient Corporation
- 6.4.3 Coim Group
- 6.4.4 Covestro AG
- 6.4.5 Dongsung
- 6.4.6 Epaflex Polyurethanes SpA
- 6.4.7 Hexpol AB
- 6.4.8 Huntsman International LLC
- 6.4.9 Miracll Chemicals Co. Ltd
- 6.4.10 Mitsui Chemicals Inc.
- 6.4.11 Novotex Italiana SpA
- 6.4.12 Sumei Chemical Co. Ltd
- 6.4.13 Suzhou Austen New Mstar Technology Ltd
- 6.4.14 Taiwan PU Corporation
- 6.4.15 The Lubrizol Corporation
- 6.4.16 Tosoh Corporation
- 6.4.17 Trinseo
- 6.4.18 Wanhua Chemical Group Co. Ltd
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment
- 7.2 Shifting Focus Toward the Development of Bio-based Products

 熱塑性聚氨酯市場:按類型、製造方法、加工方法、應用和分銷管道分類-2026-2032年全球市場預測
 熱塑性聚氨酯(TPU)市場預測至2034年-按原料、類型、加工方法、應用和地區分類的全球分析
 全球熱塑性聚氨酯市場
 熱塑性聚氨酯(TPU)市場規模、佔有率、趨勢和預測:按類型、原料、應用、最終用途行業和地區分類,2026-2034年
 熱塑性聚氨酯(TPU)市場規模、佔有率、成長率及全球產業分析:按類型、應用和地區分類,並預測至2026-2034年TPU軟管和管材市場材料類型、增強結構、壓力等級和最終用途行業分類,全球預測,2026-2032年TPU軟管市場按材料類型、應用和分銷管道分類,全球預測(2026-2032年)全球多潤滑熱塑性聚氨酯管材市場(按管流明數、產品類型、應用和最終用途產業分類)預測(2026-2032年)
 熱塑性聚氨酯(TPU)市場分析與預測(至2035年):類型、產品類型、應用、技術、形態、材料類型、最終用戶、功能、工藝
 熱塑性聚氨酯市場規模、佔有率和趨勢分析報告:按類型、應用、地區和細分市場預測(2026-2033 年)