


 |
市場調查報告書
商品編碼
2121845
印度汽車產業:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031)India Automobile Industry - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,印度汽車市場規模將從 2025 年的 1,370.6 億美元成長到 2026 年的 1,475.8 億美元,到 2031 年將達到 2,137.4 億美元,2026 年至 2031 年的複合年成長率為 7.69%。
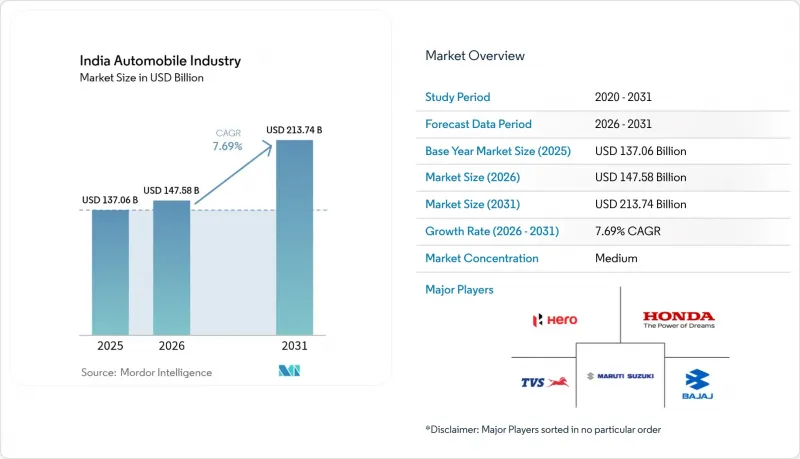
本報告按車輛類型(二輪車、三輪車及其他)、燃料類型(汽油、柴油、液化石油氣/壓縮天然氣及其他)、配銷通路(OEM授權經銷商和線上管道)、所有權類型(個人用途和商業用途)以及地區(印度北部、印度南部、印度東部和印度西部)進行細分。市場預測以美元計價。
印度汽車產業的趨勢和見解
可支配所得增加和快速都市化
收入成長正在擴大印度汽車市場的消費群。在二、三線城市,由於土地資源豐富且交通擁擠程度較低,汽車擁有量尤其可觀。 65%的人口年齡在35歲以下,而收入最高的時期恰好與首次購車的時期重疊。農村人口向城市遷移帶來了雙重需求:都市區購車者需要交通工具,而匯款則用於改善家鄉人民的生活水準。郊區就業中心的擴張降低了人們對公共運輸的依賴,並刺激了對摩托車和小型汽車的需求。訂閱模式透過避免高額首付,擴大了購車管道,進一步提高了市場滲透率。
政府對電動車和FAME-II的獎勵
印度於2019年啟動的FAME(快速採用和製造混合動力汽車及電動車)計畫第二階段,累計高達1,150億印度盧比(約13.1億美元),計畫實施五年。該計劃旨在擴大電動車的銷量,包括電動二輪車(e-2W)、電動三輪車(e-3W)和電動四輪車(e-4W)。由於泰米爾納德邦和古吉拉突邦採取了額外的邦級扶持措施,區域差異正在擴大;同時,FAME-III計劃的修訂旨在將扶持範圍擴大到更重型車輛領域。這些獎勵正在縮短投資回收期,並加速個人購車者和車隊營運商向零排放車型的轉型。
法規、安全標準和商品及服務稅 (GST) 的變化
隨著印度實施BS-VII排放標準,強制要求車輛配備安全設備,小規模組裝製造商正面臨動力傳動系統升級和認證成本高昂的困境,這擠壓了其車型的利潤空間。這些升級需要大量的研發投入和嚴格的檢驗才能符合合規標準。同時,零件商品和服務稅(GST)的調整造成了價格的不確定性,影響了製造商的整體成本結構。此外,各邦不同的道路稅制度也增加了合規難度,迫使製造商應對區域性稅收差異。這些因素可能導致消費者價格大幅上漲,從而導致消費者推遲購車計劃,並抑製印度汽車市場的短期需求。成本上漲也可能迫使製造商考慮其他策略,例如在地採購零件,以減輕其財務負擔。
細分市場分析
在印度汽車市場,二輪車佔據絕對主導地位,市佔率高達73.64%。其主導地位主要得益於價格實惠、燃油效率高以及在擁擠的都市區易於駕駛等因素,凸顯了印度消費者對二輪車的偏好。儘管乘用車的市佔率較小,但其複合年成長率(CAGR)最高,達到8.84%,這主要得益於SUV和跨界車的推出,這些車型迎合了中產階級的需求。踏板車銷量成長了21%,而二輪車銷量僅成長了10%,反映出消費者更傾向於自動變速箱以及在都市區使用便利性。
隨著電動二輪車進入主流價格區間,以及金融機構為首次購車者提供更長的融資期限,成長動能持續強勁。同時,商用車受制於基礎設施預算和工業生產週期,但正受益於持續的高速公路改善工程。三輪車在二線城市的「最後一公里」貨運和客運中仍然發揮著至關重要的作用。排放氣體法規促使投資集中於模組化平台,這有望提升印度現有汽車製造商的規模經濟效益。
2025年,汽油引擎在印度汽車市場仍將佔據59.27%的佔有率,這得益於煉油廠產能和低於柴油的採購價格。儘管銷量較低,但由於稅收優惠、FAME-II補貼以及鋰離子電池成本下降,電池式電動車正以10.02%的複合年成長率成長。混合動力汽車則在不依賴新能源基礎設施的情況下,解決了續航里程和燃油效率的難題。
旨在促進國內發電和提高燃油效率標準的政策預計將逐步推動汽車製造商的產品線轉向電動動力系統。為降低營運成本,液化石油氣/壓縮天然氣在商用車車隊的應用日益廣泛。同時,由於氫氣供應短缺,燃料電池技術仍處於示範階段。充電網路和電池更換試點計畫的部署將決定其普及速度,但各項指標已顯示,印度汽車市場各細分領域的消費者對電動動力系統的接受度正在加速提高。
其他好處
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 可支配所得增加和快速都市化
- 政府對電動車和FAME-II的獎勵
- 擴建國家高速公路與農村公路網
- 基於訂閱的所有權和租賃模式
- 區域半導體製造投資
- 企業車輛強制脫碳
- 市場限制因素
- 法規、安全標準和商品及服務稅的變化
- 全球半導體供應鏈的波動性
- 由於都市區交通堵塞而實施的使用限制
- 與車載資訊系統相關的保險費上漲
- 價值供應鏈分析
- 監理情勢
- 技術展望
- 波特五力模型
第5章 市場規模與成長預測
- 按車輛類型
- 摩托車
- 三輪車
- 搭乘用車
- 商用車輛
- 按燃料類型
- 汽油
- 柴油引擎
- LPG/CNG
- 電池式電動車
- 油電混合車
- 插電式混合動力電動車
- 燃料電池電動車
- 透過分銷管道
- 原廠授權經銷商
- 線上
- 依所有權類型
- 個人使用
- 商業用途
- 按地區
- 印度北部
- 南印度
- 東印度
- 西印度群島
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- TVS Motor Company
- Hero MotoCorp
- Honda Motorcycle
- Royal Enfield
- Bajaj Auto
- Suzuki Motorcycle India
- Maruti Suzuki India
- Tata Motors
- Hyundai Motor India
- Mahindra & Mahindra
- MG Motor India
- Volkswagen India
- Renault-Nissan Alliance
- Honda Cars India
- BYD India
- BMW Group India
- Mercedes-Benz India
- Kia India
- Ashok Leyland
- Eicher Motors(VE Commercial)
- Atul Auto
- Piaggio Vehicles
- Kinetic Green
第7章 市場機會與未來展望
According to Mordor Intelligence, the India automobile market size is expected to grow from USD 137.06 billion in 2025 to USD 147.58 billion in 2026 and is forecast to reach USD 213.74 billion by 2031 at 7.69% CAGR over 2026-2031.
This report is Segmented by Vehicle Type (Two-Wheelers, Three-Wheelers and More), Fuel Type (Petrol/Gasoline, Diesel, LPG/CNG, and More), Sales Channel (OEM-Authorized Dealers and Online), Ownership Type (Personal Use and Commercial Use), and by Region (North India, South India, East India, West India). The Market Forecasts are Provided in Terms of Value (USD).
India Automobile Industry Trends and Insights
Rising Disposable Incomes and Rapid Urbanization
Income growth is enlarging the consumer base for the Indian automobile market, especially in Tier-2 and Tier-3 cities, where land availability and lower congestion make vehicle ownership attractive. Sixty-five percent of the population is under 35, aligning prime earning years with first-time purchases. Migration from rural districts stimulates dual demand, urban buyers seek mobility, while remittances finance upgrades back home. The spread of suburban employment hubs reduces dependence on mass transit and supports two-wheelers and compact cars. Subscription programs extend access by sidestepping hefty down payments, further deepening penetration.
Government EV and FAME-II Incentives
India's FAME (Faster Adoption and Manufacturing of Hybrid & Electric Vehicles) Scheme Phase-II, launched in 2019, comes with a hefty budget of INR 11,500 crore (USD 1.31 billion), set to span five years. This initiative aims to boost the sales of electric vehicles, covering e-2Ws, e-3Ws, and e-4Ws. . State add-ons in Tamil Nadu and Gujarat enhance regional differentials, while the planned FAME-III revision aims to broaden support into heavier segments. These incentives shorten payback periods, encouraging personal buyers and fleet operators to pivot toward zero-emission models.
Regulatory Changes, Safety Standards and GST Shifts
As India implements BS-VII norms and mandates safety gear, small assemblers grapple with costly powertrain upgrades and validations, squeezing their model margins. These upgrades require significant research and development investments and rigorous testing to meet compliance standards. Meanwhile, GST realignments on components introduce pricing uncertainties, impacting the overall cost structure for manufacturers. Adding to the challenge, varying state road-tax regimes complicate compliance, as manufacturers must navigate differing tax policies across regions. These factors lead to noticeable price hikes for consumers, potentially delaying their purchases and dampening immediate demand in the Indian automobile market. Additionally, the increased costs may push manufacturers to explore alternative strategies, such as the localization of components, to mitigate the financial burden.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of National Highway and Rural Road Network
- Subscription-Based Ownership and Leasing Models
- Global Semiconductor Supply-Chain Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In the Indian auto market, two-wheelers reign supreme, commanding a significant 73.64% share. This dominance highlights the preference for two-wheelers among Indian consumers, driven by factors such as affordability, fuel efficiency, and ease of navigation in congested urban areas. Although smaller, passenger cars are posting the swiftest 8.84% CAGR on the back of SUV and crossover launches tuned to aspirational middle-class tastes. Scooter sales climbed 21% versus the motorcycle segment's 10% gain, highlighting urban preference for automatic transmissions and ease of use.
Growth momentum continues as electric two-wheelers enter mainstream price points and as financiers extend longer tenures to first-time buyers. Conversely, commercial vehicles hinge on infrastructure budgets and industrial output cycles but benefit from ongoing highway upgrades. Three-wheelers retain relevance for last-mile goods and passenger movement in Tier-2 centers. Regulatory emission upgrades funnel investments toward modular platforms, potentially elevating scale efficiencies for incumbents in the Indian automobile market.
Petrol engines retained 59.27% of the India automobile market share in 2025, buoyed by refinery capacity and lower purchase prices relative to diesel. Battery electric vehicles, though smaller in volume, are advancing at a 10.02% CAGR thanks to tax rebates, FAME-II subsidies and falling lithium-ion cell costs. Hybrids bridge range-anxiety gaps, offering efficiency gains without new-energy infrastructure dependence.
Policy commitments to domestic power generation and stricter fuel-economy norms will gradually shift OEM portfolios toward electrified drivetrains. LPG/CNG use expands in commercial fleets seeking operating-cost relief. Meanwhile, fuel-cell technology remains exploratory due to hydrogen supply gaps. Charging-network rollouts and battery-swapping pilots dictate adoption pace but indicators already point to accelerating consumer acceptance across segments in the India automobile market.
Complete Report Scope:
- By Vehicle Type
- Two-wheelers
- Three-wheelers
- Passenger Cars
- Commercial Vehicles
- By Fuel Type
- Petrol / Gasoline
- Diesel
- LPG / CNG
- Battery Electric Vehicles
- Hybrid Electric Vehicles
- Plug-in Hybrid Electric Vehicles
- Fuel-Cell Electric Vehicles
- By Sales Channel
- OEM-Authorised Dealers
- Online
- By Ownership Type
- Personal Use
- Commercial Use
- By Region
- North India
- South India
- East India
- West India
List of Companies Covered in this Report:
- TVS Motor Company
- Hero MotoCorp
- Honda Motorcycle
- Royal Enfield
- Bajaj Auto
- Suzuki Motorcycle India
- Maruti Suzuki India
- Tata Motors
- Hyundai Motor India
- Mahindra & Mahindra
- MG Motor India
- Volkswagen India
- Renault-Nissan Alliance
- Honda Cars India
- BYD India
- BMW Group India
- Mercedes-Benz India
- Kia India
- Ashok Leyland
- Eicher Motors (VE Commercial)
- Atul Auto
- Piaggio Vehicles
- Kinetic Green
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Disposable Incomes and Rapid Urbanization
- 4.2.2 Government EV and FAME-II Incentives
- 4.2.3 Expansion of National Highway and Rural Road Network
- 4.2.4 Subscription-Based Ownership and Leasing Models
- 4.2.5 Local Semiconductor Fabrication Investments
- 4.2.6 Corporate Fleet-Decarbonization Mandates
- 4.3 Market Restraints
- 4.3.1 Regulatory Changes, Safety Standards and GST Shifts
- 4.3.2 Global Semiconductor Supply-Chain Volatility
- 4.3.3 Urban Congestion-Driven Usage Restrictions
- 4.3.4 Rising Telematics-Linked Insurance Premiums
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD billion)
- 5.1 By Vehicle Type
- 5.1.1 Two-wheelers
- 5.1.2 Three-wheelers
- 5.1.3 Passenger Cars
- 5.1.4 Commercial Vehicles
- 5.2 By Fuel Type
- 5.2.1 Petrol / Gasoline
- 5.2.2 Diesel
- 5.2.3 LPG / CNG
- 5.2.4 Battery Electric Vehicles
- 5.2.5 Hybrid Electric Vehicles
- 5.2.6 Plug-in Hybrid Electric Vehicles
- 5.2.7 Fuel-Cell Electric Vehicles
- 5.3 By Sales Channel
- 5.3.1 OEM-Authorised Dealers
- 5.3.2 Online
- 5.4 By Ownership Type
- 5.4.1 Personal Use
- 5.4.2 Commercial Use
- 5.5 By Region
- 5.5.1 North India
- 5.5.2 South India
- 5.5.3 East India
- 5.5.4 West India
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 TVS Motor Company
- 6.4.2 Hero MotoCorp
- 6.4.3 Honda Motorcycle
- 6.4.4 Royal Enfield
- 6.4.5 Bajaj Auto
- 6.4.6 Suzuki Motorcycle India
- 6.4.7 Maruti Suzuki India
- 6.4.8 Tata Motors
- 6.4.9 Hyundai Motor India
- 6.4.10 Mahindra & Mahindra
- 6.4.11 MG Motor India
- 6.4.12 Volkswagen India
- 6.4.13 Renault-Nissan Alliance
- 6.4.14 Honda Cars India
- 6.4.15 BYD India
- 6.4.16 BMW Group India
- 6.4.17 Mercedes-Benz India
- 6.4.18 Kia India
- 6.4.19 Ashok Leyland
- 6.4.20 Eicher Motors (VE Commercial)
- 6.4.21 Atul Auto
- 6.4.22 Piaggio Vehicles
- 6.4.23 Kinetic Green
7 Market Opportunities & Future Outlook

 汽車市場規模、佔有率和成長分析:按車輛類型、驅動方式、燃料類型、銷售管道、最終用戶和地區分類-2026-2033年產業預測
 汽車原始設備製造商和電池價值鏈:全球和區域環境、社會和治理 (ESG) 要求:應對措施和策略(至 2040 年)
 2026年全球汽車和重型機械市場報告
 汽車數位行銷管理平台市場:按組件、應用、部署模式、最終用戶和組織規模分類,全球預測(2026-2032年)汽車磷酸鹽市場按產品類型、物理形態、磷化技術、應用和最終用途分類,全球預測(2026-2032)重型設備管理軟體市場:2026-2032年全球預測(按組件、部署類型、應用和組織規模分類)