


 |
市場調查報告書
商品編碼
2121834
耐熱塗料:市場佔有率分析、產業趨勢與統計資料、成長預測(2026-2031 年)Heat-Resistant Coatings - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
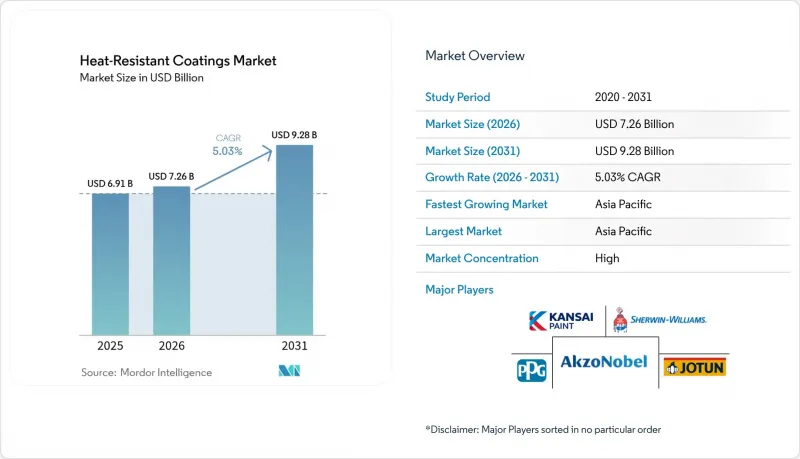
根據 Mordor Intelligence 預測,耐熱塗料市場規模將從 2025 年的 69.1 億美元成長到 2026 年的 72.6 億美元,然後在 2031 年達到 92.8 億美元,2026 年至 2031 年的複合年成長率為 5.03%。
本報告按樹脂類型(矽酮、環氧樹脂、丙烯酸樹脂和其他樹脂)、技術(溶劑型、水性、粉末型和 UV/EB 固化)、終端用戶行業(建築和施工、石油和天然氣、電力、交通運輸、木工和家具、消費品和其他終端用戶行業)以及地區(亞太地區、北美、歐洲、運輸以及中東和非洲)進行分類。
全球耐熱塗料市場趨勢及洞察
全球基礎設施投資正在激增。
世界各國政府正投入創紀錄的資金用於基礎建設,旨在增強應對氣候變遷的能力並促進城市發展。美國《基礎建設投資與就業法案》撥款2.25億美元用於修訂影響塗料規格的能源標準。亞太地區的新興經濟體也正在加速這一趨勢,印尼、印度和中國正在加速推進機場、橋樑和智慧城市項目,這些項目均採用耐高溫阻隔膜。交通隧道和區域供熱管網領域的官民合作關係進一步擴大了對持久耐用、耐熱塗料的需求。
全球更嚴格的消防安全法規
消防安全標準的修訂提高了對耐燃性、煙霧毒性和使用過程中表面溫度的最低性能要求。 2024 年國際消防安全標準引入了更新的火焰蔓延標準,這將直接影響塗料配方。加州消防安全標準第 24 章強制要求在處理耐熱產品的噴漆房內安裝自動滅火系統和專用通風系統。歐盟指令持續降低允許的溶劑含量,引導建築商使用低 VOC 的矽丙烯酸混合塗料。高層建築外觀和交通樞紐的維修推動了需求的激增,因為業主需要使其資產符合相關法規。獲得新基準值認證的製造商將在規格選擇方面享有優先權,從而減少代價高昂的返工。
矽膠和環氧樹脂價格波動
美國國際貿易委員會的裁決顯示,某些環氧樹脂進口產品的售價低於公允價值,導致國內供應緊張,成本上升。同時,亞洲多家大型矽膠生產廠的停產進一步加劇了價格波動。沒有長期合約的中小型化合物生產商面臨兩位數的成本成長,利潤空間受到擠壓,被迫調整價格。生產商正試圖透過多元化前驅來源和擴大內部單體產能來規避風險,但由於資本投資,即時改善緩慢。儘管原物料價格波動具有週期性,但短期內會對現金流量造成壓力,並阻礙研發投入。
細分市場分析
到2025年,矽膠樹脂將佔據耐熱塗料市場37.45%的佔有率,這反映了該化學物質能夠在超過600 度C的高溫下保持黏合強度。到2031年,矽樹脂的複合年成長率將達到8.78%,成為該細分市場中最高的成長率,進一步鞏固了其主導地位,使其成為耐熱塗料市場的關鍵成長引擎。矽樹脂的需求範圍涵蓋排氣煙囪、火炬塔、烘箱和航太零件等對失效零容忍的領域。環氧樹脂在中溫塗料領域仍佔據重要地位,但面臨成本上漲和雙酚A衍生物受到嚴格的監管。丙烯酸樹脂則滿足了消費品產業中對價格敏感且表面尖峰溫度相對較低的應用需求。
區域分析
預計亞太地區將引領成長,到2025年將佔全球銷售額的47.12%,並以7.35%的複合年成長率快速成長,這主要得益於交通運輸、住宅和能源領域的大型企劃。在中國「一帶一路」沿線,橋樑和隧道等易受野火和化學品洩漏風險影響的設施對耐熱底漆的需求量很大。在「印度製造」計劃下,印度正在擴大國內生產,生產需要耐熱薄膜的爐灶、鍋爐和工業烤箱。
北美仍是創新中心。美國和加拿大的主要航太公司指定使用符合軍用標準的金屬和陶瓷阻隔塗層。聯邦政府的基礎設施投資正在推動老舊橋樑的更換和電網的升級改造,每個項目都要求使用低揮發性有機化合物(VOC)和耐熱的表面塗層材料。
永續性是歐洲關注的重點。歐盟的揮發性有機化合物(VOC)排放限制逐年收緊,並鼓勵建築商採用水性矽酮和粉末塗料。德國、法國和義大利的汽車平台採用輕質金屬零件,並塗覆奈米結構陶瓷薄膜以實現熱調節。南美洲、中東和非洲市場雖然規模較小,但正受益於技術轉移和國際安全標準的採用,從而擴大了耐熱塗料的整體潛在市場。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 全球基礎設施投資正在激增。
- 全球範圍內加強消防安全法規
- 航太業需求不斷成長
- 提高對消防安全設備的認知
- 可重複使用的太空船和太空旅遊的太空船
- 市場限制因素
- 矽膠和環氧樹脂的價格波動很大。
- 溶劑型塗料的VOC監管限值
- 多層系統施工工程師短缺
- 價值鏈分析
- 波特五力模型
第5章 市場規模與成長預測
- 依樹脂類型
- 矽酮
- 環氧樹脂
- 丙烯酸纖維
- 其他樹脂(聚氨酯、醇酸樹脂等)
- 透過技術
- 溶劑型
- 水溶液
- 粉末
- UV/EB固化型
- 按最終用戶行業分類
- 建築/施工
- 石油和天然氣
- 電力業
- 運輸
- 木工和家具
- 消費品
- 其他終端用戶產業(例如,工業加工設備)
- 按地區
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 其他亞太國家
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 其他歐洲國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 南非
- 其他中東和非洲國家
- 亞太地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率和排名分析
- 公司簡介
- 3M
- Advanced Industrial Coatings
- AkzoNobel NV
- Aremco
- Arkema
- Axalta Coating Systems LLC
- BASF
- Belzona International Ltd.
- Hempel A/S
- Jotun
- Kansai Paint Co. Ltd.
- KCC Corporation
- Momentive
- PPG Industries Inc.
- Teknos Group
- The Sherwin-Williams Company
- Wacker Chemie AG
第7章 市場機會與未來展望
According to Mordor Intelligence, the heat-Resistant coatings market size is expected to grow from USD 6.91 billion in 2025 to USD 7.26 billion in 2026 and is forecast to reach USD 9.28 billion by 2031 at 5.03% CAGR over 2026-2031.
This report is Segmented by Resin (Silicone, Epoxy, Acrylic, Other Resins), Technology (Solvent-Borne, Water-Borne, Powder, UV/EB-curable), End-User Industry (Building and Construction, Oil and Gas, Power Sector, Transportation, Woodworking and Furniture, Consumer Goods, and Other End-User Industries), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa).
Global Heat-Resistant Coatings Market Trends and Insights
Surge in Global Infrastructure Spending
Governments are funding record levels of infrastructure aimed at climate resilience and urban growth. The United States Infrastructure Investment and Jobs Act earmarked USD 225 million for updated energy codes that influence coating specifications. Emerging Asia-Pacific economies add momentum as Indonesia, India, and China accelerate airport, bridge, and smart-city projects that specify high-temperature barrier films. Public-private partnerships in transport tunnels and district-heating lines further widen demand for long-cycle thermal coatings.
Stricter Global Fire-Safety Regulations
Fire-code revisions raise minimum performance thresholds for ignition resistance, smoke toxicity, and end-use surface temperature. The International Fire Code 2024 introduces updated flame-spread benchmarks that immediately affect coating formulations. California's Fire Code Chapter 24 mandates automatic extinguishing systems and specialized ventilation for coating booths handling heat-resistant products. EU directives continue to shrink allowed solvent content, pushing builders toward low-VOC silicone-acrylic hybrids. Retrofits of high-rise facades and transportation hubs create demand spikes as owners bring assets into compliance. Manufacturers that certify products above the new baseline win specification priority and reduce the need for costly rework.
Volatile Silicone and Epoxy Prices
A United States International Trade Commission ruling found certain epoxy imports were sold below fair value, tightening domestic supply and raising costs. Simultaneous outages in key Asian silicone plants amplified volatility. Smaller formulators lacking long-term contracts faced double-digit cost spikes that eroded margins and triggered product repricing. Producers hedge by dual-sourcing precursors and expanding in-house monomer capacity, but capital outlays delay immediate relief. Although raw-material swings are cyclical, they compress cash flow and hinder research and development spending in the short term.
Other drivers and restraints analyzed in the detailed report include:
- Growing Demand from the Aerospace Industry
- Rising Awareness Toward Fire Protection Equipment
- VOC Limits on Solvent-Borne Systems
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Silicone resins accounted for 37.45% of the 2025 heat-resistant coatings market share, reflecting the chemistry's ability to tolerate temperatures above 600 °C without losing adhesion. That leadership is matched by the fastest segment CAGR of 8.78% through 2031, making silicone the pivotal growth engine of the heat-resistant coatings market. Demand spans exhaust stacks, flare stacks, bake ovens, and aerospace parts where failure is unacceptable. Epoxies retain relevance in mid-temperature zones but face cost headwinds and regulatory scrutiny on bisphenol-A derivatives. Acrylics fill price-sensitive applications in consumer goods where surface temperature peaks are lower.
Complete Report Scope:
- By Resin
- Silicone
- Epoxy
- Acrylic
- Other Resins (Polyurethane, Alkyd, etc.)
- By Technology
- Solvent-borne
- Water-borne
- Powder
- UV/EB-curable
- By End-user Industry
- Building and Construction
- Oil and Gas
- Power Sector
- Transportation
- Woodworking and Furniture
- Consumer Goods
- Other End-user Industries (Industrial Processing Equipment, etc.)
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific led with 47.12% of 2025 revenue and advances at 7.35% CAGR, powered by megaprojects in transport, housing, and energy. China's Belt and Road corridors require heat-resistant primers for bridges and tunnels exposed to wildfire and chemical spill risks. India, under its Make in India vision, expands domestic manufacturing of cookstoves, boilers, and industrial ovens that all specify heat-stable films.
North America remains an innovation center. Aerospace primes in the United States and Canada specify metallic and ceramic barrier coats qualified to MIL standards. Federal infrastructure outlays replace aging bridges and improve energy grids, each project mandating low-VOC, high-temperature finishes.
Europe emphasizes sustainability. EU VOC ceilings tighten yearly, pushing builders to waterborne silicones and powder options. Automotive platforms in Germany, France, and Italy integrate lightweight metal components coated with nano-structured ceramic films for thermal regulation. Markets in South America, the Middle East and Africa grow from a smaller base yet benefit from technology transfer and the adoption of international safety codes, widening the total addressable heat-resistant coatings market.
- 3M
- Advanced Industrial Coatings
- AkzoNobel N.V.
- Aremco
- Arkema
- Axalta Coating Systems LLC
- BASF
- Belzona International Ltd.
- Hempel A/S
- Jotun
- Kansai Paint Co. Ltd.
- KCC Corporation
- Momentive
- PPG Industries Inc.
- Teknos Group
- The Sherwin-Williams Company
- Wacker Chemie AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in Global Infrastructure Spending
- 4.2.2 Stricter Global Fire-safety Regulations
- 4.2.3 Growing Demand from the Aerospace Industry
- 4.2.4 Rising Awareness Toward Fire Protection Equipment
- 4.2.5 Re-usable Spacecraft and Space-tourism Vehicles
- 4.3 Market Restraints
- 4.3.1 Volatile Silicone and Epoxy Prices
- 4.3.2 VOC Limits on Solvent-borne Systems
- 4.3.3 Applicator Skill Shortage for Multi-layer Systems
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Resin
- 5.1.1 Silicone
- 5.1.2 Epoxy
- 5.1.3 Acrylic
- 5.1.4 Other Resins (Polyurethane, Alkyd, etc.)
- 5.2 By Technology
- 5.2.1 Solvent-borne
- 5.2.2 Water-borne
- 5.2.3 Powder
- 5.2.4 UV/EB-curable
- 5.3 By End-user Industry
- 5.3.1 Building and Construction
- 5.3.2 Oil and Gas
- 5.3.3 Power Sector
- 5.3.4 Transportation
- 5.3.5 Woodworking and Furniture
- 5.3.6 Consumer Goods
- 5.3.7 Other End-user Industries (Industrial Processing Equipment, etc.)
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 3M
- 6.4.2 Advanced Industrial Coatings
- 6.4.3 AkzoNobel N.V.
- 6.4.4 Aremco
- 6.4.5 Arkema
- 6.4.6 Axalta Coating Systems LLC
- 6.4.7 BASF
- 6.4.8 Belzona International Ltd.
- 6.4.9 Hempel A/S
- 6.4.10 Jotun
- 6.4.11 Kansai Paint Co. Ltd.
- 6.4.12 KCC Corporation
- 6.4.13 Momentive
- 6.4.14 PPG Industries Inc.
- 6.4.15 Teknos Group
- 6.4.16 The Sherwin-Williams Company
- 6.4.17 Wacker Chemie AG
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

