


 |
市場調查報告書
商品編碼
2121796
資料中心自動化:市場佔有率分析、產業趨勢與統計及成長預測(2026-2031 年)Data Center Automation - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 估計,資料中心自動化市場到 2026 年的價值將達到 123.2 億美元,從 2025 年的 104.8 億美元成長到 2031 年的 276.4 億美元。
預計 2026 年至 2031 年的複合年成長率為 17.54%。
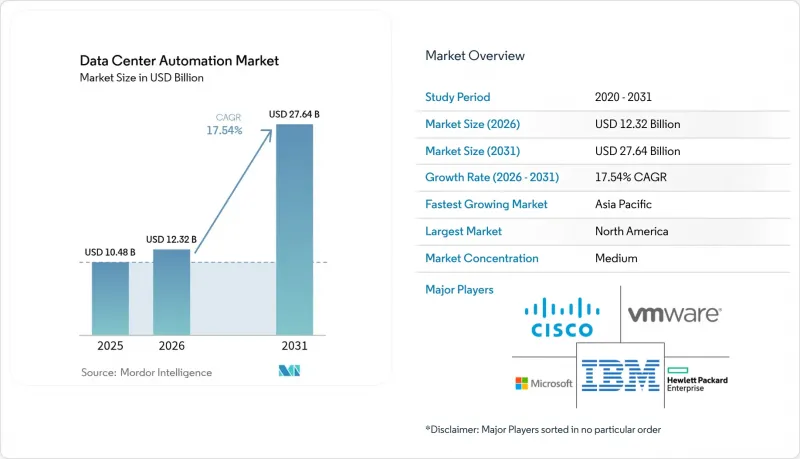
本報告按解決方案(伺服器自動化、網路自動化等)、資料中心層級(Tier 1 和 Tier 2、Tier 3、Tier 4)、部署類型(本地部署、雲端部署)、資料中心類型(超大規模資料中心業者/雲端服務供應商、主機服務供應商等)和地區進行細分。市場預測以美元(USD)計價。
全球資料中心自動化市場趨勢與洞察
雲端和超大規模設施的激增
預計到2025年,超大規模園區投資將超過2,500億美元,因此,容量規劃、溫度控管和即時工作負載遷移等的自動化需求日益凸顯。營運商正在圍繞人工智慧驅動的控制器設計設施,這些控制器能夠在幾秒鐘內分配運算、電力和冷卻資源,同時滿足服務等級要求並最大限度地減少人工干預。資本密集的擴建項目擴大採用有線且經過測試的模組化模組,這需要編配軟體來即時檢測每個模組、建立基準值並進行整合。全球供應商正在透過基於意圖的平台來應對這項挑戰,這些平台可以跨越數千個資產強制執行策略,從而將擴建速度轉化為競爭優勢。
對節能和永續營運的需求
目前,資料中心的電力消耗量的1%至3%,但隨著人工智慧的加速普及,到2030年,這一比例可能上升至5%。諸如歐洲氣候中和資料中心協議等嚴格舉措,將新建資料中心的PUE(電源使用效率)上限設定為1.3,迫使營運商實施自動化技術,持續調節氣流、風扇轉速和工作負載分佈。在初步部署中,人工智慧控制系統已將冷卻能耗降低了高達40%,而那些能夠證明碳排放量減少檢驗的營運商,正在吸引那些必須達到ESG(環境、社會和治理)目標的超大規模租戶。自動化的永續發展報告進一步減輕了合規負擔,並提高了監管機構的透明度。
舊有系統互通性的障礙
許多營運商仍然使用專有硬體,其API有限,這迫使他們在部署現代編配之前,必須先實施成本高昂的客製化連接器。由於擔心腳本配置錯誤會導致服務中斷,網路團隊往往對自動化處理關鍵業務流量的核心交換器猶豫不決。此外,傳統環境缺乏設計標準化也進一步加劇了部署的複雜性,因為為一個站點創建的模板很少能直接應用於其他站點。儘管供應商提供了豐富的插件市場和基於人工智慧的發現工具來逆向工程設備配置,但對於技術債務沉重的組織而言,遷移週期仍然漫長。
細分市場分析
網路自動化是成長最快的細分市場,預計到 2031 年將以 18.82% 的複合年成長率成長,而伺服器自動化在 2025 年將維持資料中心自動化市場 51.40% 的佔有率。以網路為中心的平台的成長反映了微服務、容器叢集和東西向流量模式的普及,這些趨勢的發展已經使得手動命令列變更不再足夠。企業正在轉向使用能夠將業務意圖轉化為設備配置並透過閉合迴路遙測檢驗結果的控制器。這種轉變可程式設計品質 (QoS)、微隔離和自動回滾功能成為可能,從而減少停機時間的發生。
從中長期來看,編配套件正在將以往各自獨立的功能——配置管理、效能分析和合規性檢查——整合到一個由基於角色的存取控制管理的統一工具鏈中。人工智慧驅動的診斷功能透過識別延遲的根本原因並提案糾正措施,縮短了平均故障修復時間 (MTTR)。因此,高階主管現在不再僅僅將網路自動化視為成本中心,而是將其視為策略性投資。到 2026 年,30% 的公司計劃實現至少一半網路活動的自動化,隨著意圖式網路廣泛應用的基礎正在奠定,預計這一勢頭將持續下去。
到2025年,Tier 3資料中心將佔資料中心自動化市場的44.95%,但由於99.995%的嚴格正常運轉率要求,Tier 4資料中心的採用率預計將以18.02%的複合年成長率成長。 Tier 4資料中心的營運商依賴編配的容錯移轉流程、即時健康評分和自癒式網狀架構。自動化診斷功能每分鐘檢查冗餘路徑和環境感測器數千次,觸發主動組件更換和負載傳輸。
同時,由於預算限制,一級和二級站點正尋求選擇性自動化,重點放在備份調度和修補程式管理。然而,軟體成本的下降和模組化控制器設計的普及降低了進入門檻。災害復原編配正成為一項普遍優先事項。自動化運作手冊現在可以實現每月容錯移轉序列測試,無需人工干預,既能保障收入,又能滿足審計要求。這些功能正在逐步縮小不同層級站點之間的營運差距,並提升行業標準。
區域分析
2025年,北美在資料中心自動化市場將維持46.05%的佔有率,主要得益於雲端運算的廣泛應用和充足的資金來源。維吉尼亞北部等關鍵區域的電力供應緊張,促使人們更加關注併網自動化,以最大限度地利用現有兆瓦電力。一項聯邦政府研究表明,到2028年資料中心電力需求可能加倍,這進一步提升了人們對能夠最大限度減少閒置能耗並透過需量反應計畫實現柔軟性的平台的興趣。企業永續發展措施也在推動人工智慧驅動的冷卻和容量規劃工具的積極應用。
亞太地區是成長最快的地區,預計2026年至2031年複合年成長率將達到19.05%。中國、日本和印度的國家主導措施正在推動本地雲端區域和邊緣基礎設施的擴張,這加劇了對自動化的需求,以彌補人手不足。包括泰國和印尼數十億美元投資在內的大型項目,結合了液冷和再生能源來源,需要編配層。
在歐洲,成熟的資料中心樞紐加上嚴格的環境法規,使其成為先進永續自動化領域的標竿。 2030年實現氣候中和設施的承諾,迫使營運商將PUE值維持在1.3以下,並實施持續最佳化引擎來檢驗可再生能源的使用情況。需量反應參與和熱能再利用計劃的獎勵進一步強化了這一商業模式。中東和非洲地區活性化的景像也反映了這一發展勢頭。沙烏地阿拉伯、阿拉伯聯合大公國和南非的旗艦專案需要證明其淨零排放和自主運作能力,以克服遠端人員配備的限制,而自動化也成為資金籌措和吸引租戶的先決條件。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 雲端和超大規模環境的快速擴展
- 對節能和永續商業營運的需求
- 對人工智慧/機器學習工作負載自動化日益成長的需求
- 混合雲和多重雲端架構的複雜性
- 資料中心併網獎勵計劃
- 新興市場的邊緣定位
- 市場限制因素
- 與舊有系統互通性相關的挑戰
- 日益加劇的網路安全和合規風險
- 網路維運/自動化領域人才短缺
- 主要地區出現電力和供水短缺
- 供應鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 市場宏觀經濟趨勢的評估
- 致力於永續發展和碳中和
- 供給能力和電力需求分析
第5章 市場規模與成長預測
- 透過解決方案
- 伺服器自動化
- 網路自動化
- 儲存/資料庫自動化
- 編配與設定管理
- 績效與合規管理
- 資料中心層級類型
- 一級和二級
- 三級
- 第四級
- 部署模式
- 現場
- 雲
- 依資料中心類型
- 超大規模資料中心業者/雲端伺服器供應商
- 託管服務提供者
- 企業和邊緣運算
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 英國
- 德國
- 法國
- 義大利
- 西班牙
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 新加坡
- 澳洲
- 馬來西亞
- 其他亞太國家
- 南美洲
- 巴西
- 智利
- 阿根廷
- 其他南美國家
- 中東
- 阿拉伯聯合大公國
- 沙烏地阿拉伯
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 其他非洲國家
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Cisco Systems Inc.
- VMware Inc.
- Microsoft Corporation
- IBM Corporation
- Hewlett Packard Enterprise(HPE)
- Dell Technologies Inc.
- BMC Software Inc.
- ServiceNow Inc.
- Oracle Corporation
- Fujitsu Ltd.
- Juniper Networks Inc.
- ABB Ltd.
- Citrix Systems Inc.
- Chef Software Inc.(Progress Software)
- Brocade Communications Systems
- HashiCorp Inc.
- Puppet Labs LLC
- Micro Focus Intl. plc
- Huawei Technologies Co. Ltd.
- Schneider Electric SE
- NetApp Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the data center automation market size in 2026 is estimated at USD 12.32 billion, growing from 2025 value of USD 10.48 billion with 2031 projections showing USD 27.64 billion, growing at 17.54% CAGR over 2026-2031.
This report is Segmented by Solution (Server Automation, Network Automation, and More), by Data Center Tier Type (Tier 1 and 2, Tier 3, and Tier 4), by Deployment Mode (On-Premise, Cloud), by Data Center Type (Hyperscalers/Cloud Service Providers, Colocation Providers, and More), and by Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Data Center Automation Market Trends and Insights
Surge in cloud and hyperscale build-outs
Hyperscale campuses scheduled for 2025 investment exceed USD 250 billion, creating an automation imperative that spans capacity planning, thermal management, and live migration of workloads. Operators are designing facilities around AI-driven controllers able to allocate compute, power, and cooling resources in seconds, matching service-level demands while shaving operator intervention to a minimum. Capital-intensive expansions are now coupled with modular blocks that ship pre-wired and pre-tested, so orchestration software must instantly discover, baseline, and integrate each block. Global vendors are responding with intent-based platforms that enforce policies across thousands of assets, turning build-out velocity into a competitive weapon.
Demand for energy-efficient and sustainable operations
Datacenters currently use 1-3% of global electricity, and projections suggest the share could rise to 5% by 2030 if AI uptake accelerates. Strict initiatives such as the Climate Neutral Data Centre Pact in Europe set a PUE ceiling of 1.3 for new builds, prompting operators to adopt automation that continually tunes airflows, fan speeds, and workload placements. AI-enhanced controls have already trimmed cooling power by up to 40% in early deployments, and operators showcasing verifiable carbon reductions are attracting hyperscale tenants that must hit their own ESG targets. Automated sustainability reporting is further lowering compliance overheads and improving transparency with regulators.
Legacy system interoperability hurdles
Many operators still run proprietary hardware with limited APIs, forcing costly custom connectors before modern orchestration can take hold. Network teams often hesitate to automate core switches that handle mission-critical traffic, fearing outages from mis-configured scripts. Lack of design standardization across legacy estates further complicates rollouts because templates built for one site rarely port cleanly to another. Vendors are responding with extensive plugin marketplaces and AI-based discovery tools that reverse-engineer device configurations, yet migration timelines remain protracted for organizations with deep technical debt
Other drivers and restraints analyzed in the detailed report include:
- Rising AI/ML workload automation needs
- Complexity of hybrid and multi-cloud architectures
- Heightened cyber-security and compliance risks
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Network Automation is the fastest-growing segment with a 18.82% CAGR projected through 2031, although Server Automation retained 51.40% of the data center automation market share in 2025. Growth in network-focused platforms mirrors the proliferation of micro-services, container clusters, and east-west traffic patterns that overwhelm manual command-line changes. Enterprises are shifting to controllers that translate business intent into device configurations, then verify outcomes through closed-loop telemetry. This shift unlocks programmable QoS, micro-segmentation, and automatic rollback capabilities that reduce downtime incidents.
In the medium term, orchestration suites are converging previously separate functions- configuration management, performance analytics, and compliance checks- into unified toolchains governed by role-based access. AI-powered diagnostics pinpoint latency roots and suggest remediations, shortening mean time to resolution. As a result, senior leadership now views network automation as a strategic investment rather than a cost center. Momentum is expected to continue as 30% of enterprises aim to automate at least half of their network activities by 2026, setting the foundation for widespread intent-based networking adoption.
Tier 3 facilities commanded 44.95% of the data center automation market size in 2025, but Tier 4 deployments are on track for an 18.02% CAGR thanks to stringent 99.995% uptime expectations. Operators of Tier 4 campuses rely on orchestrated failover processes, real-time health scoring, and self-healing mesh architectures. Automated diagnostics inspect redundant paths and environmental sensors thousands of times per minute, triggering pre-emptive part swaps or load transfers.
Conversely, Tier 1 and Tier 2 sites pursue selective automation, often focusing on backup scheduling and patch management, due to budget limits. Yet falling software costs and modular controller designs are lowering entry barriers. Disaster-recovery orchestration is becoming a universal priority: Automated runbooks now test failover sequences monthly without human intervention, fulfilling audit requirements while safeguarding revenue. These capabilities gradually narrow the operational disparities between tier levels and raise baseline expectations across the industry.
Complete Report Scope:
- By Solution
- Server Automation
- Network Automation
- Storage/Database Automation
- Orchestration and Configuration Mgmt.
- Performance and Compliance Mgmt.
- By Data Center Tier Type
- Tier 1 and 2
- Tier 3
- Tier 4
- By Deployment Mode
- On-premise
- Cloud
- By Data Center Type
- Hyperscalers/Cloud Server Providers
- Colocation Providers
- Enterprise and Edge
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Singapore
- Australia
- Malaysia
- Rest of Asia-Pacific
- South America
- Brazil
- Chile
- Argentina
- Rest of South America
- Middle East
- United Arab Emirate
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America retained 46.05% of the data center automation market share in 2025, benefiting from deep cloud adoption and access to large capital pools. Power constraints in core corridors such as Northern Virginia sharpen the focus on grid-interactive automation that maximizes every available megawatt. Federal research indicating that data-center electricity demand may double by 2028 magnifies interest in platforms that minimize idle consumption and monetize flexibility through demand-response programs. Corporate sustainability narratives further encourage aggressive deployment of AI-guided cooling and capacity-planning tools.
Asia-Pacific is the fastest-growing territory with a 19.05% CAGR expected between 2026-2031. National initiatives in China, Japan, and India incentivize local cloud zones and edge build-outs, magnifying the need for automation that can compensate for labor shortages. Large-scale projects, including multi-billion-dollar investments in Thailand and Indonesia, bundle liquid-cooling and renewable power sources, demanding orchestration layers able to harmonize disparate technologies from day one.
Europe combines mature colocation hubs with tight environmental regulation, creating a crucible for advanced sustainability automation. Commitments to achieve climate-neutral facilities by 2030 push operators to deploy continuous-optimization engines that maintain sub-1.3 PUE targets and verify renewable-energy usage. Incentives for demand-response participation and heat-re-use schemes reinforce the business case. Growing activity in the Middle East and Africa mirrors this momentum: flagship projects in Saudi Arabia, the United Arab Emirates, and South Africa require net-zero proof points and autonomous operation to overcome remote-site staffing limitations, positioning automation as a prerequisite for securing financing and tenants.
- Cisco Systems Inc.
- VMware Inc.
- Microsoft Corporation
- IBM Corporation
- Hewlett Packard Enterprise (HPE)
- Dell Technologies Inc.
- BMC Software Inc.
- ServiceNow Inc.
- Oracle Corporation
- Fujitsu Ltd.
- Juniper Networks Inc.
- ABB Ltd.
- Citrix Systems Inc.
- Chef Software Inc. (Progress Software)
- Brocade Communications Systems
- HashiCorp Inc.
- Puppet Labs LLC
- Micro Focus Intl. plc
- Huawei Technologies Co. Ltd.
- Schneider Electric SE
- NetApp Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in cloud and hyperscale build-outs
- 4.2.2 Demand for energy-efficient and sustainable operations
- 4.2.3 Rising AI/ML workload automation needs
- 4.2.4 Complexity of hybrid and multi-cloud architectures
- 4.2.5 Grid-interactive incentive programs for data centers
- 4.2.6 Edge localization in emerging economies
- 4.3 Market Restraints
- 4.3.1 Legacy system interoperability hurdles
- 4.3.2 Heightened cyber-security and compliance risks
- 4.3.3 NetOps/automation talent shortage
- 4.3.4 Power and water scarcity in major hubs
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Assessment of Macro-economic Trends on the Market
- 4.9 Sustainability and Carbon-Neutral Initiatives
- 4.10 Capacity and Power-Demand Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Solution
- 5.1.1 Server Automation
- 5.1.2 Network Automation
- 5.1.3 Storage/Database Automation
- 5.1.4 Orchestration and Configuration Mgmt.
- 5.1.5 Performance and Compliance Mgmt.
- 5.2 By Data Center Tier Type
- 5.2.1 Tier 1 and 2
- 5.2.2 Tier 3
- 5.2.3 Tier 4
- 5.3 By Deployment Mode
- 5.3.1 On-premise
- 5.3.2 Cloud
- 5.4 By Data Center Type
- 5.4.1 Hyperscalers/Cloud Server Providers
- 5.4.2 Colocation Providers
- 5.4.3 Enterprise and Edge
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 United Kingdom
- 5.5.2.2 Germany
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Singapore
- 5.5.3.5 Australia
- 5.5.3.6 Malaysia
- 5.5.3.7 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Chile
- 5.5.4.3 Argentina
- 5.5.4.4 Rest of South America
- 5.5.5 Middle East
- 5.5.5.1 United Arab Emirate
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 Turkey
- 5.5.5.4 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Nigeria
- 5.5.6.3 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Cisco Systems Inc.
- 6.4.2 VMware Inc.
- 6.4.3 Microsoft Corporation
- 6.4.4 IBM Corporation
- 6.4.5 Hewlett Packard Enterprise (HPE)
- 6.4.6 Dell Technologies Inc.
- 6.4.7 BMC Software Inc.
- 6.4.8 ServiceNow Inc.
- 6.4.9 Oracle Corporation
- 6.4.10 Fujitsu Ltd.
- 6.4.11 Juniper Networks Inc.
- 6.4.12 ABB Ltd.
- 6.4.13 Citrix Systems Inc.
- 6.4.14 Chef Software Inc. (Progress Software)
- 6.4.15 Brocade Communications Systems
- 6.4.16 HashiCorp Inc.
- 6.4.17 Puppet Labs LLC
- 6.4.18 Micro Focus Intl. plc
- 6.4.19 Huawei Technologies Co. Ltd.
- 6.4.20 Schneider Electric SE
- 6.4.21 NetApp Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

 2026年全球資料中心編配市場報告
 資料中心自動化市場規模、佔有率、成長及全球產業分析:按類型、應用和地區分類的洞察,2026-2034 年預測
 資料中心自動化市場:按元件、產業、部署類型和組織規模分類 - 2026-2032 年全球預測2026年全球資料中心自動化市場報告全球資料中心自動化市場規模、佔有率、趨勢和成長分析報告(2026-2034)
 全球資料中心自動化軟體市場預測(至2034年):按組件、部署類型、資料中心類型、應用程式、最終用戶和地區分類
 資料中心自動化市場規模、佔有率和成長分析(按組件、部署類型、最終用戶和地區分類)-2026-2033年產業預測
 資料中心自動化的全球市場的評估:各零件,各部署方式,不同企業規模,各最終用途產業,各地區,機會,預測(2018年~2032年)
 全球資料中心數位雙胞胎維系統市場:規模、製造商、供應鏈、銷售管道與客戶(2025-2031 年)
 資訊中心AM:3D列印的市場機會