


 |
市場調查報告書
商品編碼
2121768
苯乙烯:市佔率分析、產業趨勢與統計、成長預測(2026-2031)Styrene - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
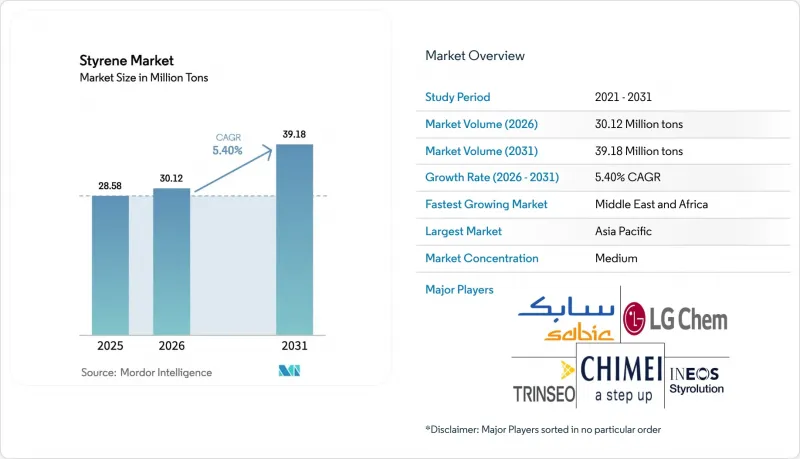
根據 Mordor Intelligence 預測,苯乙烯市場預計將從 2025 年的 2,858 萬噸成長到 2026 年的 3,012 萬噸,到 2031 年達到 3,918 萬噸,2026 年至 2031 年的複合年成長率為 5.40%。
本報告按產品類型(聚苯乙烯、丙烯腈-丁二烯-苯乙烯共聚物及其他產品類型)、終端用戶產業(包裝、建築、消費品、汽車及運輸、電氣電子及其他終端用戶產業)和地區(亞太地區、北美、歐洲、南美以及中東和非洲)進行細分。市場預測以數量(噸)為單位。
全球苯乙烯市場趨勢與洞察
對輕量、堅固包裝材料的需求日益成長
由硬質聚苯乙烯製成的翻蓋式容器具有同等厚度的聚乙烯或聚丙烯替代品難以企及的透明度和剛性。歐盟的《包裝和包裝廢棄物法規 (2025/40)》規定,到 2030 年,包裝材料中回收成分必須達到 35%,到 2040 年達到 65%,鼓勵加工商在非食品應用領域使用機械回收的聚苯乙烯,在食品接觸領域使用化學回收的單體。英力士苯領 (INEOS Styrolution) 已獲得美國 FDA 食品接觸通知 2245,該通知適用於熱解衍生的苯乙烯,這為優格杯和烘焙托盤在不影響其抗跌落衝擊性能的前提下實現品牌目標鋪平了道路。 Agilyx 旗下的 TruStyrenyx 工廠已完成日處理量 100 噸的解聚生產線的設計,但最終投資取決於收購協議的完成情況。雖然熱解可使單體純度達到 90% 以上,但原料收集仍是一個瓶頸,大多數地區的運轉率低於預期。
家用電器機殼需求快速成長
預計到2025年,全球人工智慧PC的出貨量將達到1.14億台,每台機型在其內部結構中將使用150-200克阻燃ABS材料。超大規模資料中心業者指定使用紫外線穩定的丙烯腈-苯乙烯-丙烯酸酯共聚物(ABS)製造5G基地台機殼,這種材料能夠經受10年的戶外曝曬而不出現粉化現象。三星Galaxy S24系列於2024年1月發布,其支架部分繼續使用原生ABS材料,以滿足±0.05毫米或更小的尺寸公差要求。由於LG化學和奇美電子的耐熱ABS供應緊張,電子產品OEM廠商不得不向中國採購兩種材料,儘管熔體流動速率規格有差異。
一次性PS和EPS材料在超過130個國家被禁用。
歐盟的《包裝和包裝廢棄物法規》將於2029年1月起禁止在店內用餐時使用一次性EPS食品容器,並於2030年1月起禁止在外帶使用,這將導致區域需求減少18萬噸。紐約州和加州的法規將使美國的需求進一步減少3.5萬至4萬噸,而加拿大則於2024年實施了全國範圍的禁令。快餐店正在轉向使用模塑紙漿和聚丙烯,這將使成本增加10%至15%,但可以減少海洋垃圾。缺乏設備升級資金的中小型擠出製造商正在將資產出售給大型加工商,加速了產業整合。
細分市場分析
預計到2025年,聚苯乙烯的產量將佔總產量的46.38%,但由於食品服務業禁止使用聚苯乙烯,其成長率預計將低於苯乙烯市場的整體複合年成長率。轉向化學回收至關重要。 Trinseo和Recycling Technologies目前每年將3萬噸廢棄材料轉化為符合歐盟法規10/2011和FDA FCN 2245標準的全新等效單體。丙烯腈-丁二烯-苯乙烯共聚物(ABS)引領市場擴張,複合年成長率達6.18%,主要得益於電動車電池托盤和5G設備機殼對UL 94 V-0標準的要求。BASF和沙烏地基礎工業公司(SABIC)的特殊ABS產品與金屬替代品相比,可減輕零件重量25-30%。由於中國將於 2023 年至 2024 年開始運作每年 145 萬噸的新產能,因此通用聚苯乙烯的利潤率正面臨壓力。
儘管英力士苯領公司於2025年9月對再生單體的檢驗證明了循環經濟的可行性,但每噸150至200美元的回收和分類成本仍然對營業利潤率構成壓力。苯乙烯-丙烯腈共聚物的市場正隨著整體需求的成長而擴張,尤其是在透明度至關重要的透明外殼領域。隨著米其林將再生苯乙烯添加到輪胎胎面中,並力爭2030年達到40%的永續材料含量,苯乙烯-丁二烯橡膠(SBR)的需求也不斷增加。
區域分析
預計亞太地區將繼續保持主導地位,到2025年將佔全球產量的49.27%。但由於產能擴張速度超過需求成長,中國正轉型為結構性出口國。印度的年產量成長主要由消費品製造業驅動,但仍有40%依賴進口,這為海灣國家的出口商帶來了機會。在韓國和台灣,耐熱ABS供應緊張,迫使電子品牌接受從中國進口的較長交貨期。日本正在試驗Agilyx的化學回收技術,這顯示日本正在向循環經濟轉型。
北美地區的成長落後於亞太地區。這是因為,儘管亞太地區在乙烷成本方面具有優勢,但英力士關閉了位於薩尼亞的工廠,而利安德巴塞爾則優先考慮循環經濟項目而非擴大新的產能。墨西哥則憑藉汽車零件出口實現了成長,這與美墨加協定(USMCA)相符。
由於能源成本飆升和監管日益嚴格,歐洲經濟成長放緩。隨著Versalis公司關閉位於Priuro的裂解裝置,加工商必須確保使用化學回收或生物基原料,以滿足回收成分的要求。根據歐盟指令,德國對1979年以前住宅存量維修,這推動了對EPS(聚苯乙烯泡沫塑膠)的需求,儘管這些翻新工程都要求低碳排放。
中東和非洲地區以5.91%的複合年成長率成為各地區中成長最快的地區,這主要得益於沙烏地阿拉伯在其「2030願景」框架下擴大下游產業一體化,以及南非以本地生產的EPS隔熱材料取代進口產品。一項碳捕獲試點計畫旨在抵消歐盟在2030年後可能徵收的碳邊境調節稅。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 對輕量、堅固包裝材料的需求日益成長
- 住宅對家用電器的需求迅速成長。
- 推廣基於淨零建築標準的隔熱措施
- 車輛輕量化以延長電動車的續航里程
- 化學回收能力的突破性擴展
- 市場限制因素
- 超過 130 個國家禁止使用一次性 PS 和 EPS。
- 原料(苯/乙烯)價格波動
- 歐盟對高耗能聚合物徵收碳邊境調節稅
- 價值鏈分析
- 波特五力模型
第5章 市場規模與成長預測
- 依產品類型
- 聚苯乙烯
- 丙烯腈丁二烯苯乙烯
- 苯乙烯-丁二烯橡膠
- 其他產品種類(苯乙烯-丙烯腈)
- 按最終用戶行業分類
- 包裝
- 建造
- 消費品
- 汽車和運輸業
- 電氣和電子設備
- 其他終端用戶產業(紡織品)
- 按地區
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 東南亞國協
- 其他亞太國家
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 北歐國家
- 其他歐洲國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 南非
- 其他中東和非洲國家
- 亞太地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率和排名分析
- 公司簡介
- Americas Styrenics LLC(AmSty).
- Asahi Kasei Corporation
- BASF
- Chevron Phillips Chemical Company
- CHIMEI
- Covestro AG
- Dow
- Formosa Chemicals & Fibre Corp.
- Hanwha Group
- INEOS Styrolution
- Kumho Petrochemical
- LG Chem
- LyondellBasell Industries Holdings BV
- PetroChina Co. Ltd
- Reliance Industries Ltd
- SABIC
- SIBUR
- Synthos
- TotalEnergies
- Trinseo
- Versalis SpA
- Wanhua Petrochemical(Yantai)Co., Ltd.
- Westlake Corporation
第7章 市場機會與未來展望
According to Mordor Intelligence, the styrene market size is expected to increase from 28.58 million tons in 2025 to 30.12 million tons in 2026 and reach 39.18 million tons by 2031, growing at a CAGR of 5.40% over 2026-2031.
This report is Segmented by Product Type (Polystyrene, Acrylonitrile Butadiene Styrene, and Other Product Types), End-User Industry (Packaging, Construction, Consumer Goods, Automotive and Transportation, Electrical and Electronics, and Other End-User Industries), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa). The Market Forecasts are Provided in Terms of Volume (Tons).
Global Styrene Market Trends and Insights
Rising Demand for Lightweight, Rigid Packaging
Rigid polystyrene clamshells deliver clarity and stiffness that polyethylene and polypropylene alternatives struggle to match at comparable thickness. The EU Packaging and Packaging Waste Regulation 2025/40 sets 35% recycled content by 2030 and 65% by 2040, pushing converters toward mechanically recycled polystyrene for non-food uses and chemically recycled monomer for food-contact items. INEOS Styrolution obtained U.S. FDA Food Contact Notification 2245 for pyrolysis-derived styrene, clearing the way for yogurt cups and bakery trays to meet brand targets without compromising drop-impact resistance . Agilyx's TruStyrenyx facility completed engineering for a 100 ton-per-day depolymerization line, although final investment hinges on offtake agreements. While pyrolysis achieves more than 90% monomer purity, feedstock collection remains the bottleneck, keeping recyclers' operating rates below nameplate in most regions.
Booming Consumer-Electronics Housing Demand
Global AI-capable PC shipments are projected at 114 million units in 2025, each incorporating 150-200 grams of flame-retardant ABS for internal structures. Hyperscale operators specify UV-stabilized acrylonitrile-styrene-acrylate copolymers for 5G base-station enclosures that must endure 10-year outdoor exposure without chalking. Samsung's Galaxy S24 family, launched January 2024, continues to rely on virgin ABS for brackets where dimensional tolerances below +-0.05 millimeters are mandatory. Supply of high-heat ABS from LG Chem and CHIMEI is tight, compelling electronics OEMs to dual-source from China despite variability in melt-flow index specifications.
Single-Use PS and EPS Bans in More Than 130 Nations
The EU Packaging and Packaging Waste Regulation bans single-use EPS foodware from January 2029 for dine-in and January 2030 for takeaway, eliminating 180,000 tons of regional demand. New York and California restrictions remove another 35,000-40,000 tons in the United States, while Canada's nationwide ban came into force in 2024. Quick-service restaurants migrate to molded-fiber pulp or polypropylene, raising costs 10-15% yet reducing marine-litter exposure. Small extruders lacking capital to retool are selling assets to larger converters, accelerating consolidation.
Other drivers and restraints analyzed in the detailed report include:
- Insulation Push from Net-Zero Construction Codes
- Automotive Lightweighting for EV Range Extension
- Feedstock (Benzene/Ethylene) Price Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Polystyrene commanded 46.38% of 2025 volume, though its growth is projected below the overall styrene market CAGR due to food-service bans. The chemical-recycling pivot is critical; Trinseo and Recycling Technologies now convert 30,000 tons per year of post-consumer material into virgin-equivalent monomer that qualifies under EU Regulation 10/2011 and FDA FCN 2245. Acrylonitrile-butadiene-styrene heads the expansion table at a 6.18% CAGR, supported by electric-vehicle battery trays and 5G equipment housings that require UL 94 V-0 compliance. Specialty ABS grades from BASF and SABIC achieve 25-30% part-weight savings versus metal substitutes. Commodity general-purpose polystyrene faces margin compression from 1.45 million tons per year of new Chinese capacity commissioned in 2023-2024.
Recycled monomer validation by INEOS Styrolution in September 2025 demonstrates circular viability, yet collection and sorting costs of USD 150-200 per ton continue to suppress operating margins. Styrene-acrylonitrile copolymers grow in line with overall demand, primarily in transparent housings where clarity is valued. Styrene-butadiene rubber gains traction as Michelin integrates recycled styrene into tire treads, targeting 40% sustainable-material content by 2030.
Complete Report Scope:
- By Product Type
- Polystyrene
- Acrylonitrile Butadiene Styrene
- Styrene Butadiene Rubber
- Other Product Types (Styrene-Acrylonitrile)
- By End-user Industry
- Packaging
- Construction
- Consumer Goods
- Automotive and Transportation
- Electrical and Electronics
- Other End-User Industries (Textile)
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific controlled 49.27% of 2025 volume and will retain leadership, yet capacity expansions outpace demand growth, turning China into a structural exporter. India's annual increase rides consumer-goods manufacturing and remains 40% import-dependent, presenting opportunity for Gulf exporters. South Korea and Taiwan confront tight high-heat ABS supply, prompting electronics brands to accept longer lead times from China. Japan pilots Agilyx chemical recycling, signaling a pivot toward circularity.
North America's growth trails Asia-Pacific as INEOS closed the Sarnia plant and LyondellBasell emphasizes circular projects over new capacity, despite the region's ethane cost advantage. Mexico advances under USMCA-aligned auto-parts exports.
Europe lags due to energy costs and stringent bans. Versalis shuttered its Priolo cracker, and converters must secure chemically recycled or bio-attributed feedstock to meet recycled-content mandates. Renovation of Germany's pre-1979 housing stock under EU directives does lift EPS demand, albeit conditioned on low-carbon footprints.
The Middle East and Africa delivers the highest regional CAGR at 5.91% as Saudi Arabia extends downstream integration under Vision 2030 and South Africa substitutes imports with local EPS insulation. Carbon-capture pilots seek to neutralize potential EU carbon-border levies post-2030.
- Americas Styrenics LLC (AmSty).
- Asahi Kasei Corporation
- BASF
- Chevron Phillips Chemical Company
- CHIMEI
- Covestro AG
- Dow
- Formosa Chemicals & Fibre Corp.
- Hanwha Group
- INEOS Styrolution
- Kumho Petrochemical
- LG Chem
- LyondellBasell Industries Holdings BV
- PetroChina Co. Ltd
- Reliance Industries Ltd
- SABIC
- SIBUR
- Synthos
- TotalEnergies
- Trinseo
- Versalis SpA
- Wanhua Petrochemical (Yantai) Co., Ltd.
- Westlake Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Demand for Lightweight, Rigid Packaging
- 4.2.2 Booming Consumer-Electronics Housing Demand
- 4.2.3 Insulation Push from Net-Zero Construction Codes
- 4.2.4 Automotive Lightweighting for EV Range Extension
- 4.2.5 Breakthrough Chemical-Recycling Capacity Build-Out
- 4.3 Market Restraints
- 4.3.1 Single-Use PS And EPS Bans In more than 130 Nations
- 4.3.2 Feed-Stock (Benzene/Ethylene) Price Volatility
- 4.3.3 EU Carbon-Border Tariffs on High-Energy Polymers
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Product Type
- 5.1.1 Polystyrene
- 5.1.2 Acrylonitrile Butadiene Styrene
- 5.1.3 Styrene Butadiene Rubber
- 5.1.4 Other Product Types (Styrene-Acrylonitrile)
- 5.2 By End-user Industry
- 5.2.1 Packaging
- 5.2.2 Construction
- 5.2.3 Consumer Goods
- 5.2.4 Automotive and Transportation
- 5.2.5 Electrical and Electronics
- 5.2.6 Other End-User Industries (Textile)
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 ASEAN Countries
- 5.3.1.6 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 NORDIC Countries
- 5.3.3.6 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle-East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, Recent Developments)
- 6.4.1 Americas Styrenics LLC (AmSty).
- 6.4.2 Asahi Kasei Corporation
- 6.4.3 BASF
- 6.4.4 Chevron Phillips Chemical Company
- 6.4.5 CHIMEI
- 6.4.6 Covestro AG
- 6.4.7 Dow
- 6.4.8 Formosa Chemicals & Fibre Corp.
- 6.4.9 Hanwha Group
- 6.4.10 INEOS Styrolution
- 6.4.11 Kumho Petrochemical
- 6.4.12 LG Chem
- 6.4.13 LyondellBasell Industries Holdings BV
- 6.4.14 PetroChina Co. Ltd
- 6.4.15 Reliance Industries Ltd
- 6.4.16 SABIC
- 6.4.17 SIBUR
- 6.4.18 Synthos
- 6.4.19 TotalEnergies
- 6.4.20 Trinseo
- 6.4.21 Versalis SpA
- 6.4.22 Wanhua Petrochemical (Yantai) Co., Ltd.
- 6.4.23 Westlake Corporation
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment


