


 |
市場調查報告書
商品編碼
2121652
鋁箔包裝:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Aluminum Foil Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
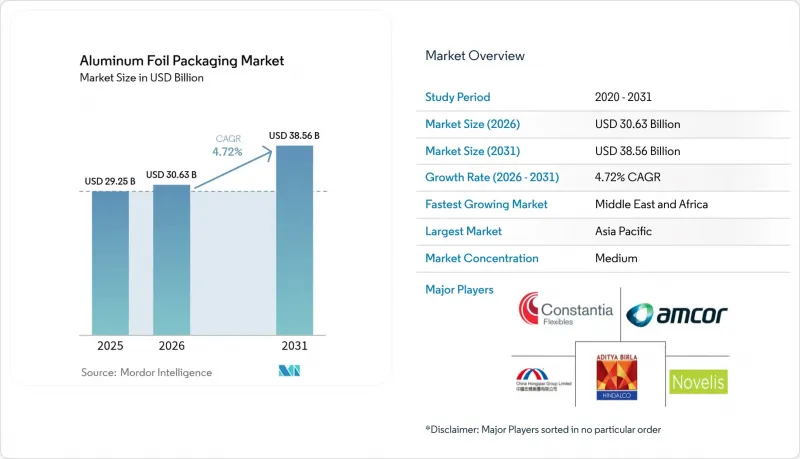
據 Mordor Intelligence 稱,鋁箔包裝市場預計到 2026 年價值 306.3 億美元,高於 2025 年的 292.5 億美元,預計到 2031 年將達到 385.6 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 4.72%。
本報告按類型(軋延箔、背襯箔、壓花/塗漆箔等)、應用(加工箔、容器箔、家用箔等)、包裝形式(包裝膜、小袋/包裝袋等)、最終用戶(食品、飲料、醫藥、化妝品/個人護理等)和地區進行細分。市場預測以美元計價。
全球鋁箔包裝市場趨勢及洞察
即食食品和簡便食品的需求不斷成長
人們追求便利的生活方式推動了即食食品、烘焙點心和熟食產品消費量的成長。鋁箔的導熱性使其能夠均勻加熱至200 度C,從而提升了食品服務托盤、蓋子和殺菌袋的價值。在沙烏地阿拉伯,預計到2028年,包裝食品的零售額將達到342億美元,比2024年成長38%。銷售量的成長直接轉化為托盤和鋁箔蓋用量的增加。北美和亞太地區的主要加工商正在其冷藏和冷凍食品生產線中採用鋁箔托盤,從而加強批量採購契約,並穩定加工商的訂單積壓。
藥品泡殼包裝的需求不斷成長
厚度為20-25微米的冷成型鋁箔具有卓越的防潮和抗氧阻隔性,即使在嚴苛的氣候條件下也能維持藥品的療效。美國FDA對穩定性數據的重視推動了更深、更深拉製泡殼包裝的普及,而這種包裝需要延展性好、耐刮的鋁箔。印度和印尼等新興學名藥市場正在運作新的泡殼包裝生產線,導致塗層和複合鋁箔捲材的需求增加。該領域的高價位使加工商能夠降低金屬價格波動帶來的風險。
替代生物基軟性材料
瞄準環保意識消費者的品牌正在探索紙箔混合材料和可堆肥阻隔薄膜。在零食和糖果甜點,部分替代是可行的,因為適度的氧氣阻隔性能就足夠了。雖然生物膜目前的阻隔性能不如鋁箔,但強調可再生的行銷訊息正在加速歐洲和北美試點計畫的發展。隨著回收法規透過稅收和標籤激勵措施鼓勵使用可再生原料,這種威脅將會加劇。
細分市場分析
捲材鋁箔在2025年將佔鋁箔總銷售額的52.05%,作為印刷、複合和模塑生產線的原料,它構成了鋁箔包裝市場的基礎。捲材鋁箔的生產範圍很廣,從6微米的家用薄片到200微米的工業級薄片,供應商可以根據最終應用調整厚度。加工商的強勁需求使得中國、印度和德國的冶煉廠產運轉率接近90%。受背襯鋁箔的推動,鋁箔包裝市場預計將以4.98%的複合年成長率成長,製藥業對冷成型和高階咖啡膠囊的需求推動了複合設計的發展。
壓花和塗漆產品適用於裝飾糖果甜點包裝和防篡改蓋,從而在細分市場中獲得溢價。季節性設計,例如雷諾茲消費品公司於2024年11月推出的節日主題鋁箔,展示了表面紋理和顏色如何提升展示吸引力。 “其他類型”,例如穿孔透氣鋁箔和冷凝器鋁箔,規模較小,但對技術要求非常嚴格,這促使供應商進行專業化分工。
預計到2025年,加工鋁箔將佔總銷售額的41.01%,鞏固其在鋁箔包裝市場的核心地位。貼合機和印刷商將母卷加工成捲材,用於生產包裝袋、小袋和紙盒,推動了穩定的噸位供應。無溶劑黏合劑和電子束固化技術的日益普及,在不犧牲加工能力的前提下,提高了功能層的成型效率。主要用於托盤和半硬質餐具的鋁箔,隨著速食食品逐漸滲透到新興中等收入都市區,預計將以5.71%的複合年成長率成長。
家用鋁箔仍然是家庭廚房的必備品,雷諾茲消費品公司的內部數據顯示,95%的美國家庭廚房都使用鋁箔。雖然成熟市場的銷售量保持平穩,但非洲和南亞市場正在擴張,家用鋁箔捲的新買家數量持續成長。工業和隔熱鋁箔的需求與建築節能標準密切相關,這些標準要求在冷暖氣空調空調(HVAC)系統和屋頂材料中使用反射屏障,這構成了建築週期中一個雖小眾但需求強勁的市場。
區域分析
預計到2025年,亞太地區將佔全球鋁箔市場規模的39.88%。這主要得益於中國叢集綜合冶煉廠和軋延的蓬勃發展,以及印度鋁業公司(Hindalco)在印度投資100億美元擴建電池鋁箔生產線。儘管電力價格偶爾上漲,但較低的運費和接近性礬土的地理優勢正在增強該地區的出口競爭力。受加工食品需求成長和疫苗生產本地化的推動,該地區的鋁箔包裝市場預計將以中等個位數的速度成長。
北美仍是技術主導,運作先進的廢棄物分類廠,廢棄鋁箔回收率超過35%。美國冷藏食品和液態營養補充品的訂閱服務,以及採用感應性密封罐包裝的配送服務,推動了鋁箔消費的成長。加拿大楓糖產品產業也正在從玻璃容器轉向鋁箔複合包裝袋,以減輕運輸重量。
歐洲受《包裝及包裝廢棄物法規》的嚴格監管。強制性的最低再生材料含量目標推動了對連續熱解和脫漆設備的投資,以回收用於重熔的潔淨鋁。合規成本給中小加工商帶來了沉重負擔,而跨國公司則利用閉合迴路項目,例如奧地利的咖啡膠囊回收試點項目,該項目在三個月內收集了500萬個膠囊。中東和非洲地區正以6.78%的複合年成長率快速成長,這主要得益於食品加工產業的外國直接投資(FDI)以及沙烏地阿拉伯和埃及快速發展的製藥產業叢集。這些地區需要適用於炎熱氣候物流的阻隔性包裝。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 即食食品和簡便食品的需求不斷成長
- 藥品泡殼包裝的需求不斷成長
- 優異的阻隔性和更長的保存期限
- 用於電子商務中液體產品的感應加熱密封襯裡。
- 電動車電池中軟包鋁箔的應用
- 垂直農業對反光箔的需求
- 市場限制因素
- 替代生物基軟性材料
- 鋁錠價格波動
- 歐盟收緊鋁箔廢料回收目標。
- 與高耗能冶煉相關的ESG風險
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 波特五力分析
- 宏觀經濟因素對市場的影響
第5章 市場規模與成長預測
- 按類型
- 錫箔卷
- 鋁箔背襯
- 壓花和漆箔
- 其他類型
- 透過使用
- 轉換器用箔
- 容器鋁箔
- 家用鋁箔
- 工業/熱箔
- 按包裝類型
- 裹
- 小袋和小袋
- 水泡和蓋子
- 托盤和容器
- 其他包裝形式
- 最終用戶
- 食物
- 飲料
- 製藥
- 化妝品和個人護理
- 菸草
- 其他最終用戶
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 智利
- 其他南美國家
- 歐洲
- 英國
- 德國
- 法國
- 西班牙
- 義大利
- 其他歐洲國家
- 亞太地區
- 中國
- 印度
- 日本
- 澳洲
- 韓國
- 越南
- 其他亞太國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 埃及
- 其他非洲國家
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Amcor plc
- Constantia Flexibles Group GmbH
- Novelis Inc.
- Hindalco Industries Limited
- Alcoa Corporation
- Reynolds Consumer Products Inc.
- UACJ Corporation
- Hydro Aluminium AS
- United Company RUSAL Plc
- China Hongqiao Group Limited
- Laminazione Sottile SpA
- Toyo Aluminium KK
- Carcano Antonio SpA
- Hulamin Ltd.
- Henan Zhongfu Industrial Co., Ltd.
- Coppice Alupack Ltd.
- Ess Dee Aluminium Ltd.
- Penny Plate LLC
- Eurofoil SA
- Alufoil Products Pvt. Ltd.
- Zhangjiagang Goldshine Aluminium Foil Co., Ltd.
- Ningbo Times Aluminium Foil Tech Co., Ltd.
- Haomei Aluminium Co., Ltd.
- RCA Converters
第7章 市場機會與未來展望
According to Mordor Intelligence, the aluminum foil packaging market size in 2026 is estimated at USD 30.63 billion, growing from 2025 value of USD 29.25 billion with 2031 projections showing USD 38.56 billion, growing at 4.72% CAGR over 2026-2031.
This report is Segmented by Type (Rolled Foil, Backed Foil, Embossed and Lacquered, and More), Application (Converter Foils, Container Foils, Household Foils, and More), Packaging Format (Wraps, Pouches and Sachets, and More), End User (Food, Beverage, Pharmaceutical, Cosmetics and Personal Care, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Aluminum Foil Packaging Market Trends and Insights
Rising Demand for Ready-to-Eat and Convenience Foods
Convenience-oriented lifestyles elevate consumption of heat-and-eat meals, baked goods, and deli products. Aluminum foil's thermal conductivity enables uniform reheating up to 200 °C, adding value for foodservice trays, lidding films, and retort pouches. In Saudi Arabia, packaged food retail sales are projected to reach USD 34.2 billion by 2028, 38% above 2024 levels. Volume upticks translate directly into higher foil tonnage for trays and lidding. Major processors in North America and Asia-Pacific embed foil trays into chilled and frozen meal lines, reinforcing bulk procurement contracts that stabilize converter order books.
Growth in Pharmaceutical Blister Demand
Cold-form aluminum foil of 20-25 microns thickness offers unrivaled moisture and oxygen barriers, preserving drug potency across harsh climates. The U.S. FDA's emphasis on stability data propels the adoption of deeper-draw blister formats that require ductile, scratch-free foil grades. Emerging generics hubs in India and Indonesia commission new blister lines, raising call-off volumes for coated and laminated foil reels. Premium pricing in this segment cushions converters against metal price volatility.
Alternative Bio-Based Flexible Materials
Brands targeting eco-conscious consumers explore paper-foil hybrids and compostable barrier films. In snacks and confectionery, moderate oxygen protection suffices, allowing partial substitution. While bio-films cannot yet equal foil's full barrier profile, marketing narratives around renewability accelerate trials in Europe and North America. The threat intensifies once recycling legislation rewards renewable inputs through tax incentives or labeling advantages.
Other drivers and restraints analyzed in the detailed report include:
- Superior Barrier Properties and Shelf-Life Extension
- Induction Heat-Seal Liners for E-Commerce Liquids
- Raw Aluminum Price Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Rolled Foil captured 52.05% of 2025 revenue, anchoring the aluminum foil packaging market through its role as feedstock for printing, laminating, and forming lines. The output spectrum spans 6-micron household sheets to 200-micron industrial grades, letting suppliers tailor gauge to end-use. Strong converter demand keeps mills in China, India, and Germany running near 90% capacity utilization. The aluminum foil packaging market size attributed to Backed Foil is projected to widen at a 4.98% CAGR as pharmaceutical cold-form and premium coffee capsule demand reward laminate designs.
Embossed and Lacquered variants address decorative confectionery wraps and tamper-evident lidding, generating niche price premiums. Seasonal patterns, such as holiday-pattern foil launched by Reynolds Consumer Products in November 2024, illustrate how surface texture and color enhance shelf appeal. Other Types, including perforated ventilation foils and capacitor foils, remain small but technically stringent, reinforcing supplier specialization.
Converter Foils generated 41.01% of 2025 sales, confirming their place at the center of the aluminum foil packaging market. Laminators and printers transform master coils into rollstock for pouches, sachets, and cartons, driving consistent tonnage flow. Rising adoption of solvent-free adhesives and electron-beam curing elevates functional layering without sacrificing throughput. Container Foils, mainly for trays and semi-rigid dishes, are forecast at a 5.71% CAGR as ready-to-eat meals penetrate emerging middle-income urban zones.
Household Foil remains a legacy staple, held in 95% of U.S. kitchens per Reynolds Consumer Products' internal data. Volume is flat in mature markets but expands in Africa and South Asia, where consumer foil rolls still gain first-time buyers. Industrial and Insulation Foils link demand to building energy codes that specify reflective barriers in HVAC and roofing, a niche yet resilient outlet during construction cycles.
Complete Report Scope:
- By Type
- Rolled Foil
- Backed Foil
- Embossed and Lacquered Foil
- Other Types
- By Application
- Converter Foils
- Container Foils
- Household Foils
- Industrial/Insulation Foils
- By Packaging Format
- Wraps
- Pouches and Sachets
- Blisters and Lids
- Trays and Containers
- Other Packaging Fomrats
- By End User
- Food
- Beverage
- Pharmaceutical
- Cosmetics and Personal Care
- Tobacco
- Other End Users
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Vietnam
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific contributed 39.88% of the 2025 value, driven by China's integrated smelter-converter clusters and India's USD 10 billion Hindalco capacity expansion aimed at battery foil lines. Lower freight costs and proximity to bauxite mines reinforce export competitiveness despite occasional power-price spikes. The aluminum foil packaging market size attached to the region is set for mid-single-digit growth, underpinned by processed food uptake and vaccine production localization.
North America remains technology-led, hosting advanced scrap-sorting plants that lift post-consumer foil recovery yields above 35%. U.S. consumption benefits from chilled-meal subscriptions and nutraceutical liquids shipped in induction-sealed jars. Canada's maple-products sector likewise shifts from glass to foil laminate pouches to trim freight weights.
Europe faces the tightest regulatory lens under the Packaging and Packaging Waste Regulation. Mandatory minimum recycled content targets spur investments in continuous pyrolysis and de-lacquering units that reclaim clean aluminum for remelt. While compliance costs strain small converters, multinational groups use closed-loop programs such as Austria's coffee-capsule recycling pilot that collected 5 million units in three months. The Middle East and Africa, expanding at 6.78% CAGR, leverages food-processing FDI and burgeoning pharmaceutical clusters in Saudi Arabia and Egypt that require high-barrier packs to suit hot-climate logistics.
- Amcor plc
- Constantia Flexibles Group GmbH
- Novelis Inc.
- Hindalco Industries Limited
- Alcoa Corporation
- Reynolds Consumer Products Inc.
- UACJ Corporation
- Hydro Aluminium AS
- United Company RUSAL Plc
- China Hongqiao Group Limited
- Laminazione Sottile S.p.A.
- Toyo Aluminium K.K.
- Carcano Antonio S.p.A.
- Hulamin Ltd.
- Henan Zhongfu Industrial Co., Ltd.
- Coppice Alupack Ltd.
- Ess Dee Aluminium Ltd.
- Penny Plate LLC
- Eurofoil S.A.
- Alufoil Products Pvt. Ltd.
- Zhangjiagang Goldshine Aluminium Foil Co., Ltd.
- Ningbo Times Aluminium Foil Tech Co., Ltd.
- Haomei Aluminium Co., Ltd.
- RCA Converters
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising demand for ready-to-eat and convenience foods
- 4.2.2 Growth in pharmaceutical blister demand
- 4.2.3 Superior barrier properties and shelf-life extension
- 4.2.4 Induction heat-seal liners for e-commerce liquids
- 4.2.5 EV battery pouch-foil adoption
- 4.2.6 Vertical-farming reflective foil demand
- 4.3 Market Restraints
- 4.3.1 Alternative bio-based flexible materials
- 4.3.2 Raw aluminum price volatility
- 4.3.3 Stricter EU recycling targets on foil scrap
- 4.3.4 ESG risks from energy-intensive smelting
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 The Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 Rolled Foil
- 5.1.2 Backed Foil
- 5.1.3 Embossed and Lacquered Foil
- 5.1.4 Other Types
- 5.2 By Application
- 5.2.1 Converter Foils
- 5.2.2 Container Foils
- 5.2.3 Household Foils
- 5.2.4 Industrial/Insulation Foils
- 5.3 By Packaging Format
- 5.3.1 Wraps
- 5.3.2 Pouches and Sachets
- 5.3.3 Blisters and Lids
- 5.3.4 Trays and Containers
- 5.3.5 Other Packaging Fomrats
- 5.4 By End User
- 5.4.1 Food
- 5.4.2 Beverage
- 5.4.3 Pharmaceutical
- 5.4.4 Cosmetics and Personal Care
- 5.4.5 Tobacco
- 5.4.6 Other End Users
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Chile
- 5.5.2.4 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Spain
- 5.5.3.5 Italy
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 Australia
- 5.5.4.5 South Korea
- 5.5.4.6 Vietnam
- 5.5.4.7 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Egypt
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, Recent Developments)
- 6.4.1 Amcor plc
- 6.4.2 Constantia Flexibles Group GmbH
- 6.4.3 Novelis Inc.
- 6.4.4 Hindalco Industries Limited
- 6.4.5 Alcoa Corporation
- 6.4.6 Reynolds Consumer Products Inc.
- 6.4.7 UACJ Corporation
- 6.4.8 Hydro Aluminium AS
- 6.4.9 United Company RUSAL Plc
- 6.4.10 China Hongqiao Group Limited
- 6.4.11 Laminazione Sottile S.p.A.
- 6.4.12 Toyo Aluminium K.K.
- 6.4.13 Carcano Antonio S.p.A.
- 6.4.14 Hulamin Ltd.
- 6.4.15 Henan Zhongfu Industrial Co., Ltd.
- 6.4.16 Coppice Alupack Ltd.
- 6.4.17 Ess Dee Aluminium Ltd.
- 6.4.18 Penny Plate LLC
- 6.4.19 Eurofoil S.A.
- 6.4.20 Alufoil Products Pvt. Ltd.
- 6.4.21 Zhangjiagang Goldshine Aluminium Foil Co., Ltd.
- 6.4.22 Ningbo Times Aluminium Foil Tech Co., Ltd.
- 6.4.23 Haomei Aluminium Co., Ltd.
- 6.4.24 RCA Converters
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

 寵物濕食用鋁箔容器市場:全球市場預測,2026-2032年
 FIBC鋁箔內襯袋市場報告:趨勢、預測及競爭分析(至2035年)熱食鋁箔包裝市場報告:趨勢、預測及競爭分析(至2035年)
 鋁製食品包裝市場規模、佔有率、成長和行業分析:按產品類型、厚度、應用、地區分類,並預測至2034年鋁箔包裝市場規模、佔有率、成長和行業分析:按包裝類型、產品類型、厚度、最終用途、地區分類,並預測至2034年鋁箔包裝市場規模、佔有率、成長和行業分析:按產品類型、最終用途和地區分類,並預測至2034年
 2026年全球鋁瓶飲料市場報告鋁箔包裝市場:2026-2032年全球市場預測(依產品類型、形狀、厚度、應用及最終用途產業分類)
 鋁箔包裝市場報告:按產品類型、包裝形式、箔材類型、厚度、最終用途行業和地區分類(2026-2034 年)依結構、層壓技術、厚度、形狀和應用分類的鋁塑複合薄膜市場—2026-2032年全球預測