


 |
市場調查報告書
商品編碼
2121567
矽膠:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Silicone - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
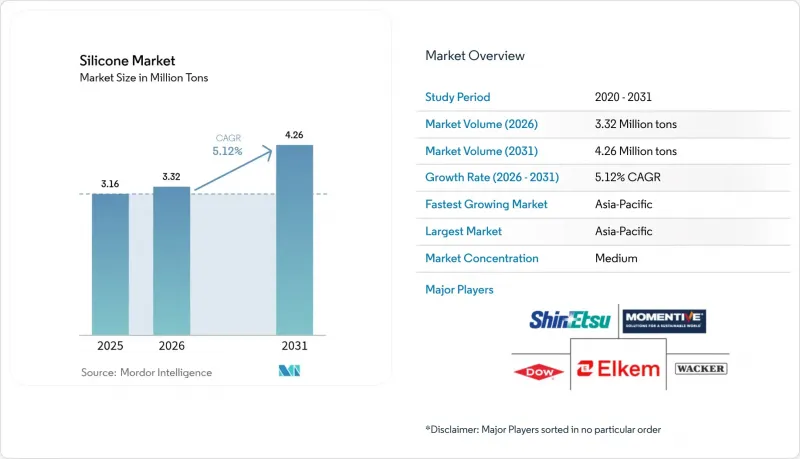
據 Mordor Intelligence 稱,2026 年矽膠市場規模估計為 332 萬噸,高於 2025 年的 316 萬噸,預計到 2031 年將達到 426 萬噸。
預計從 2026 年到 2031 年,其複合年成長率將達到 5.12%。
本報告按形態(流體、彈性體、樹脂及其他)、應用領域(交通運輸、建築材料、電子、醫療保健、工業流程、個人護理和消費品及其他應用)和地區(亞太地區、北美、歐洲、南美以及中東和非洲)進行細分。市場預測以噸為單位。
全球矽膠市場趨勢與洞察
在汽車和電動車領域的應用不斷擴展
電動車的普及擴大了與傳統彈性體的性能差距,導致矽膠用量急劇增加。光是特斯拉Model Y的電池組密封件、隔熱墊和高壓電纜絕緣層就使用了約15公斤矽膠,大約是內燃機轎車用量的三倍。歐洲汽車製造商現在傾向於使用液態矽橡膠(LSR)來製造引擎室內必須承受150 度C高溫下新型無乙二醇冷卻液的零件。中國電動車製造商開始同時採購高黏度橡膠和加成型LSR,以緩解金屬矽膠價格波動的影響,這也有助於供應商之間簽訂長期合約。隨著嚴格的零排放目標逐步實施,所有主要汽車製造商都在重新設計墊片、灌封材料和介面材料,為整個矽膠產業創造了對更高品質產品的持續需求。
在醫療保健和醫療設備領域不斷擴大應用
醫用級矽膠必須通過美國藥典 (USP) VI 級和 ISO 10993 測試。此測試方案可將新產品的藍圖延長至多 24 個月,從而保護現有供應商免受短期價格波動帶來的壓力。穿戴式血糖監測儀、心臟導線和神經調節植入均依賴液態矽膠 (LSR) 的低致敏性和在體溫下穩定的彈性模量。在醫院,與伽馬射線、蒸氣和電子束滅菌方法的兼容性至關重要,這有助於微創器材的精益重複使用策略。醫療保健的數位化,特別是遠端監測的普及,正在推動原始設備製造商 (OEM) 對半透明、光學透明矽膠薄膜的需求,這些薄膜可以整合光學感測器,且不會影響其彎曲壽命。這些因素共同鞏固了醫療保健產業作為提升矽膠產業獲利能力的關鍵支柱的地位。
矽金屬價格波動與供應瓶頸
2024年,能源價格波動和貿易措施導致矽金屬現貨價格在每噸1800美元至3200美元之間波動,對一體化生產商和公司公司附屬生產商的利潤率帶來壓力。由於中國供應全球約68%的矽產量,各省的電力發行限制會立即波及下游矽的生產和價格。雖然長期採購合約提供了一定的保障,但許多合約每年續約,使買家容易受到能源成本上行風險。半導體屑的回收試驗僅能滿足不到5%的化學級矽需求,緩解作用有限。在多元化的低碳冶煉規模擴大之前,原物料價格的波動將繼續為矽產業的短期前景蒙上陰影。
細分市場分析
預計到2025年,彈性體將佔矽膠市場佔有率的49.35%,並預計在2031年之前以5.33%的複合年成長率成長。其中,用於電動車連接器和醫用導管的液態矽橡膠(LSR)佔據了噸位成長的大部分,而高黏度橡膠則在工業墊片領域獲得了持續的訂單。液態矽橡膠(LSR)的鉑金硫化化學反應縮短了生產週期,並允許使用多腔模具,從而可以高效地擴大生產規模,用於大量生產零件。同時,室溫硫化(RTV)產品正在鞏固建築和維修行業密封劑業務的基礎,並創造了不受宏觀週期波動影響的穩定需求。綜上所述,這些特性使彈性體成為矽膠產業的關鍵創新中心。
流體產品在產量中佔比第二大,這主要得益於它們在製程添加劑、潤滑劑和個人護理潤膚劑等領域的廣泛應用。儘管即將訂定的矽氧烷法規對通用產品的周期性波動構成挑戰,但低揮發性線性流體正日益受到關注,並有助於彌補損失。樹脂作為電力電子和太陽能板的保護性封裝材料,其熱穩定性優於環氧樹脂產品,因此在特定領域持續成長。凝膠、泡沫和粉末等特殊產品形態豐富了產品組合,為先進纖維、3D列印樹脂和積層製造黏合劑等領域提供了解決方案。儘管這些領域之間的界限日漸模糊,但這些累積的發展仍然對整個矽酮市場規模保持著均衡的貢獻。
區域分析
在一體化供應鏈和活躍的下游製造業的推動下,預計到 2025 年,亞太地區將佔全球矽膠市場佔有率的 65.10%。特別是中國,擁有完全後向整合企業,結合了本地金屬矽爐和彈性體精加工廠,因此具備了成本競爭力和快速規模化生產的能力。
北美在技術領域始終處於領先地位,航太、先進汽車和生物醫學設備製造商對材料規格有嚴格的要求。 《晶片和半導體產品安全法案》(CHIPS Act)促進了國內半導體生產,並刺激了對超低離子污染矽酮封裝材料的新訂單。中西部地區的風力發電機改造和西南部地區的食品藥物管理局發電廠擴建推動了對高耐久性密封劑的需求,而美國食品藥物管理局(FDA)對液態矽橡膠(LSR,軟性矽酮)組件的核准流程的可預測性也促進了醫療領域的需求。這些趨勢,加上對生物基矽氧烷前驅物的積極研究,鞏固了該地區作為矽酮產業創新驅動力的地位。
歐洲憑藉在專業應用和法規領域的領先地位,正不斷鞏固自身地位。製造商正投資於閉合迴路解聚系統,將廢棄彈性體轉化為環狀單體,這與歐盟的循環經濟願景相符。汽車電氣化推動了對耐高溫、低滲漏導熱墊的需求,而北海離岸風力發電建設的擴張則催生了對用於機艙封裝的高強度樹脂的需求。雖然遵守REACH法規會增加合規成本,但也為直接競爭設定了壁壘,有助於維持整個歐洲矽膠產業的附加價值。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 在汽車和電動車領域不斷拓展應用。
- 在醫療保健和醫療設備領域不斷擴大應用
- 來自輸配電網路的需求
- 用於5G基地台的導熱材料
- LSR在穿戴式醫療感測器的應用
- 市場限制因素
- 矽金屬價格波動與供應瓶頸
- 嚴格的矽氧烷排放法規
- 來自含氟聚合物和熱塑性塑膠的競爭
- 價值鏈分析
- 波特五力模型
第5章 市場規模與成長預測
- 按形式
- 體液
- 彈性體
- 樹脂
- 其他
- 透過使用
- 運輸
- 建築材料
- 電子設備
- 衛生保健
- 工業流程
- 個人護理和消費品
- 其他用途
- 地區
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 泰國
- 馬來西亞
- 印尼
- 越南
- 其他亞太國家
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 土耳其
- 北歐的
- 其他歐洲國家
- 南美洲
- 巴西
- 阿根廷
- 哥倫比亞
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 南非
- 奈及利亞
- 埃及
- 卡達
- 阿拉伯聯合大公國
- 其他中東和非洲國家
- 亞太地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率和排名分析
- 公司簡介
- BRB International(PETRONAS)
- CHT Germany GmbH
- DIC Corporation
- Dongyue Group
- Dow
- DyStar Singapore Pte Ltd
- Elkem ASA
- Evonik Industries AG
- Hoshine Silicon Industry Co., Ltd
- KANEKA Corporation
- KCC SILICONE CORPORATION
- Momentive
- Shin-Etsu Chemical Co. Ltd
- Siltech Corporation
- Wacker Chemie AG
- Wynca Tinyo Silicone Co., Ltd.
- Zhejiang Hengyecheng Organic Silicone Co., Ltd.
第7章 市場機會與未來展望
According to Mordor Intelligence, silicone market size in 2026 is estimated at 3.32 million tons, growing from 2025 value of 3.16 million tons with 2031 projections showing 4.26 million tons, growing at 5.12% CAGR over 2026-2031.
This report is Segmented by Form (Fluids, Elastomers, Resins, and Others), Application (Transportation, Construction Materials, Electronics, Healthcare, Industrial Processes, Personal Care and Consumer Products, and Other Applications), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Volume (Tons).
Global Silicone Market Trends and Insights
Rising Applications in Automotive and E-mobility
Electric-vehicle (EV) adoption is multiplying the use of silicone by widening the performance gap versus traditional elastomers. Battery-pack sealing, thermal gap-pads, and high-voltage cable insulation collectively add close to 15 kg of silicone per Tesla Model Y, roughly triple that of an internal-combustion sedan. European OEMs now favor liquid-silicone rubber (LSR) for under-hood parts that must withstand new glycol-free coolants at 150 °C. Chinese EV makers have begun dual-sourcing high-consistency rubber and addition-cure LSR to buffer silicon-metal price swings, encouraging integrated suppliers to lock in long-term contracts. As stringent zero-emission targets phase in, every major automaker is redesigning gasketing, potting, and interface materials, creating an enduring pull for advanced grades across the silicone industry.
Increasing Usage in Healthcare and Medical Devices
Medical-grade silicones must clear USP Class VI and ISO 10993 testing, a protocol that can extend new-product roadmaps by up to 24 months, thereby shielding incumbent suppliers from short-cycle pricing pressure. Wearable glucose monitors, cardiac leads, and neuromodulation implants all hinge on LSR's hypoallergenic profile and stable modulus at body temperature. Hospitals value the polymer's sterilization compatibility with gamma, steam, and e-beam methods, which supports lean re-use strategies in minimally invasive tools. Digitization of care-particularly remote monitoring-has sparked OEM demand for translucent, optically clear silicone films that integrate optical sensors without compromising flex-life. Collectively, these factors cement healthcare as a margin-accretive pillar of the silicone industry.
Volatile Silicon-metal Prices and Supply Bottlenecks
Spot silicon-metal swung between USD 1,800-3,200/ton in 2024 on energy-price gyrations and trade measures, squeezing margin profiles across integrated and merchant producers alike. China supplies nearly 68% of global output, so provincial power rationing immediately reverberates through downstream silicone volumes and pricing. While long-term offtake contracts provide partial insulation, most renew annually, leaving buyers exposed to structural energy-cost inflation. Pilot recycling of semiconductor kerf scrap yields less than 5% of chemical-grade demand, offering only modest relief. Until diversified, low-carbon smelting gains scale, raw-material turbulence will shadow short-term forecasts for the silicone industry.
Other drivers and restraints analyzed in the detailed report include:
- Demand from Power Transmission and Distribution Grids
- 5G Base-station Thermal Interface Materials
- Stringent Siloxane Emission Regulations
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Elastomers controlled 49.35% of the silicone market share in 2025 and are forecast to grow at a 5.33% CAGR through 2031. Within this group, liquid-silicone rubber for EV connectors and medical catheters captures the lion's share of incremental tonnage, while high-consistency rubber secures repeat orders in industrial gasketing. LSR's platinum-cure chemistry shortens cycle times, allowing multi-cavity molds that scale efficiently for high-volume parts. Meanwhile, room-temperature-vulcanizing (RTV) grades strength-en sealant franchises in construction rehabilitation, feeding consistent demand regardless of macro-cycles. Collectively, these attributes make elastomers the pivotal innovation hub in the silicone industry.
Fluids rank second in volume, anchored by their role as process aids, lubricants, and personal-care emollients. Although impending siloxane limits challenge commodity cyclics, linear-chain fluids with lower volatility are gaining traction and help offset losses. Resins continue to deliver niche growth as protective encapsulants in power electronics and solar panels, where their thermal stability outperforms epoxy analogs. Specialty formats-gels, foams, and powders-round out the portfolio, supplying advanced textiles, 3-D printing resins, and additive-manufacturing binders. Even as boundaries blur, the cumulative developments sustain a balanced contribution to the silicone market size.
Complete Report Scope:
- By Form
- Fluids
- Elastomers
- Resins
- Others
- By Application
- Transportation
- Construction Materials
- Electronics
- Healthcare
- Industrial Processes
- Personal Care and Consumer Products
- Other Applications
- Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Thailand
- Malaysia
- Indonesia
- Vietnam
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Turkey
- Nordics
- Rest of Europe
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Nigeria
- Egypt
- Qatar
- United Arab Emirates
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific wielded 65.10% of the global silicone market share in 2025, propelled by integrated supply chains and prolific downstream manufacturing. China features fully backward-integrated players that couple local silicon-metal furnaces to elastomer finishing plants, enabling cost competitiveness and rapid scale-up.
North America remains a technology vanguard, where aerospace, advanced automotive, and biomedical device makers impose stringent material specifications. The CHIPS Act catalyzes domestic semiconductor production, triggering new orders for ultra-low-ionic contamination silicone encapsulants. Wind-turbine repowering in the Midwest and solar-farm expansions in the Southwest anchor demand for high-durability sealants, while the U.S. Food and Drug Administration's predictable pathway for LSR components bolsters healthcare volumes. These trends, paired with active research into bio-based siloxane precursors, position the region as an innovation driver in the silicone industry.
Europe secures its role through specialty applications and regulatory leadership. Producers invest in closed-loop depolymerization units that convert spent elastomer scrap into cyclic monomers, aligning with the bloc's circular-economy vision. Automotive electrification mandates energize demand for high-temperature, low-bleed thermal pads, while offshore-wind build-outs in the North Sea necessitate robust resins for nacelle encapsulation. Although REACH obligations elevate compliance costs, they also create barriers that temper direct price competition, sustaining value density across the European silicone industry.
- BRB International (PETRONAS)
- CHT Germany GmbH
- DIC Corporation
- Dongyue Group
- Dow
- DyStar Singapore Pte Ltd
- Elkem ASA
- Evonik Industries AG
- Hoshine Silicon Industry Co., Ltd
- KANEKA Corporation
- KCC SILICONE CORPORATION
- Momentive
- Shin-Etsu Chemical Co. Ltd
- Siltech Corporation
- Wacker Chemie AG
- Wynca Tinyo Silicone Co., Ltd.
- Zhejiang Hengyecheng Organic Silicone Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising applications in automotive and e-mobility
- 4.2.2 Increasing usage in healthcare and medical devices
- 4.2.3 Demand from power transmission and distribution grids
- 4.2.4 5G base-station thermal interface materials
- 4.2.5 LSR adoption in wearable medical sensors
- 4.3 Market Restraints
- 4.3.1 Volatile silicon-metal prices and supply bottlenecks
- 4.3.2 Stringent siloxane emission regulations
- 4.3.3 Competition from fluoropolymers and thermoplastics
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Form
- 5.1.1 Fluids
- 5.1.2 Elastomers
- 5.1.3 Resins
- 5.1.4 Others
- 5.2 By Application
- 5.2.1 Transportation
- 5.2.2 Construction Materials
- 5.2.3 Electronics
- 5.2.4 Healthcare
- 5.2.5 Industrial Processes
- 5.2.6 Personal Care and Consumer Products
- 5.2.7 Other Applications
- 5.3 Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 Thailand
- 5.3.1.6 Malaysia
- 5.3.1.7 Indonesia
- 5.3.1.8 Vietnam
- 5.3.1.9 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Spain
- 5.3.3.6 Russia
- 5.3.3.7 Turkey
- 5.3.3.8 Nordics
- 5.3.3.9 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Colombia
- 5.3.4.4 Rest of South America
- 5.3.5 Middle-East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Nigeria
- 5.3.5.4 Egypt
- 5.3.5.5 Qatar
- 5.3.5.6 United Arab Emirates
- 5.3.5.7 Rest of Middle-East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 BRB International (PETRONAS)
- 6.4.2 CHT Germany GmbH
- 6.4.3 DIC Corporation
- 6.4.4 Dongyue Group
- 6.4.5 Dow
- 6.4.6 DyStar Singapore Pte Ltd
- 6.4.7 Elkem ASA
- 6.4.8 Evonik Industries AG
- 6.4.9 Hoshine Silicon Industry Co., Ltd
- 6.4.10 KANEKA Corporation
- 6.4.11 KCC SILICONE CORPORATION
- 6.4.12 Momentive
- 6.4.13 Shin-Etsu Chemical Co. Ltd
- 6.4.14 Siltech Corporation
- 6.4.15 Wacker Chemie AG
- 6.4.16 Wynca Tinyo Silicone Co., Ltd.
- 6.4.17 Zhejiang Hengyecheng Organic Silicone Co., Ltd.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet Need Assessment

 全球矽膠市場:按類型、終端應用產業及地區分類-預測至2031年
 二甲基環矽氧烷市場:全球市場預測,2026-2032年矽膠市場:2026-2032年全球市場預測(依產品類型、形態、固化機制、黏度範圍、終端應用產業及應用領域分類)
 矽膠市場報告:按產品類型、應用和地區分類(2026-2034 年)
 2026年全球矽穿孔電極(TSV)銅電鍍解決方案市場研究報告
 多晶矽市場:按應用、終端用戶產業、製造技術、純度和地區分類重型設備市場中的矽酮:按產品類型、應用和地區分類(2026-2034 年)
 矽膠隔熱墊市場規模、佔有率和成長分析:按產品類型、材料品質、最終用戶、分銷管道和地區分類-2026-2033年產業預測
 全球矽膠市場規模、佔有率、趨勢和成長分析報告(2026-2034年)矽酮聚合物市場:按類型、終端應用產業及地區分類