


 |
市場調查報告書
商品編碼
2121555
奈米纖維:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Nanofiber - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
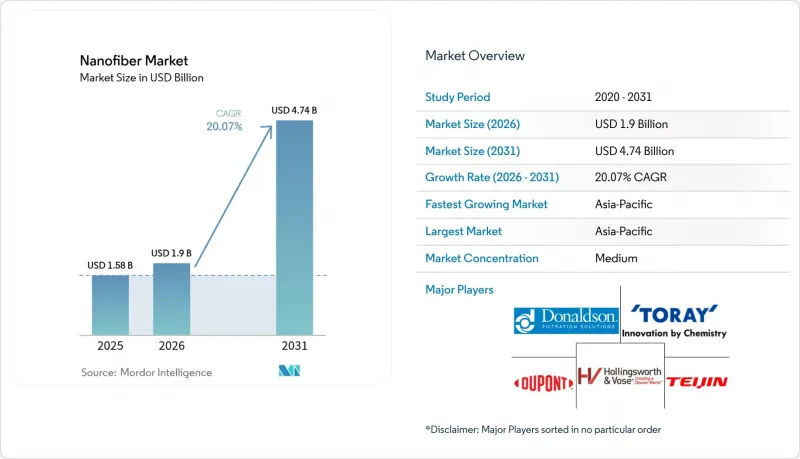
據 Mordor Intelligence 稱,2025 年奈米纖維市值為 15.8 億美元,預計到 2031 年將達到 47.4 億美元,而 2026 年為 19 億美元,預測期(2026-2031 年)的複合年成長率為 20.07%。
本報告按產品類型(聚合物奈米纖維、碳奈米纖維等)、應用領域(水和空氣過濾、醫療等)、製造技術(靜電紡絲(針式)、無針靜電紡絲等)以及地區(亞太地區、北美地區、歐洲地區、南美地區、中東和非洲地區)進行細分。市場預測以美元計價。
全球奈米纖維市場趨勢及洞察
來自醫療和製藥行業的需求不斷成長
以奈米纖維為基礎的藥物傳遞平台目前可實現超過85%的載藥率和長達96小時的持續釋放,顯著提高治療依從性並降低全身毒性。其類似細胞外基質的結構支持卓越的細胞黏附,從而能夠建立新一代組織支架,縮短癒合時間並最大限度地減少疤痕。採用先進傷口敷料的醫院由於患者周轉率的提高而降低了護理成本,這推動了採購需求。整形外科領域奈米纖維支架的監管路徑正在不斷改進,降低了開發商的上市風險。這些醫療保健領域的突破性進展,加上保險報銷前景的改善,正在增強高價值醫療保健管道的持續需求。
電動車超級工廠對高表面積電池隔膜的需求
採用靜電紡絲技術生產的奈米纖維隔膜如今能夠承受高達 150 度C的溫度波動而不發生尺寸變化,滿足電動車的關鍵安全標準。其離子電導率的提升可使充電速度提高高達 40%,同時保持循環壽命,這一優勢推動了亞洲和美國超級工廠的需求。自動化卷對卷生產線已實現年產量超過 300 萬平方米,縮小了與傳統聚烯薄膜的成本差距。主要電池製造商的資本投資確保了多年供應契約,為奈米纖維供應商提供了可預測的產量資訊。中國和美國清潔旅遊支援措施正在進一步推動隔膜在新電池化學系統中的應用。
PAN原料價格波動
聚丙烯腈(PAN)約佔奈米纖維前驅物的90%,其現貨價格每年波動高達20%,嚴重影響下游供應商的獲利能力。丙烯腈原料短缺導致的供應中斷加劇了庫存風險,生產商正在探索採用石油瀝青和木質素等替代原料,以增強其永續性能力,同時將原料成本控制在每公斤9美元以下。由於雜質控制和機械性能的差異性,這項轉型仍需時日,延長了PAN價格波動風險的暴露時間。買家正透過指數掛鉤合約進行避險,但長期價格前景仍不明朗,限制了產能的正面擴張。
細分市場分析
聚合物事業部擁有成熟的靜電紡絲生產線,產品在包裝、過濾和醫療設備等領域具有廣泛的化學通用性,預計2025年將佔總銷售額的41.20%。碳水化合物衍生級聚合物雖然產量較小,但由於終端用戶尋求符合全球循環經濟理念的可生物分解和生物基替代品,其正以26.2%的複合年成長率快速成長。纖維素奈米纖維具有與芳香聚醯胺相當的拉伸強度,且在室溫下可生物分解,因此正被包裝供應商用於一次性包裝應用。幾丁質奈米纖維因其獨特的抗菌性能而備受創傷護理產品製造商的關注,推動了對貝類廢棄物有效利用的投資。碳奈米纖維廣泛應用於特種能源和電子領域,但目前生產規模和成本的挑戰限制了其成長。
品牌商為減少化石基塑膠的使用所做的努力,進一步增強了複合材料產品的發展動能。歐盟多個成員國對一次性合成纖維的法律禁令也推動了這項需求。複合奈米纖維是聚合物和陶瓷相的混合物,在高溫過濾這一細分市場中發揮重要作用。金屬和金屬氧化物級奈米纖維用於催化劑和感測器應用,這些應用對高導電性和光催化活性要求極高。陶瓷奈米纖維作為航太領域的隔熱材料和爐襯材料,需求仍然強勁。隨著原料研發轉向林業和農業廢棄物,成本曲線預計將趨於收斂,這將促進奈米纖維市場的整體擴張。
區域分析
預計到2025年,亞太地區將佔全球銷售額的37.60%,其中中國、日本和韓國受益於強大的電子元件供應鏈和政府主導的奈米技術計畫。中國強大的電動車生產基地正在推動本地對奈米纖維隔膜的需求,而嚴格的環境法規正在加速其在空氣過濾系統維修的應用。分配給永續材料的區域經濟刺激資金進一步降低了木質素衍生奈米纖維製造廠的投資風險。這項生態系統支撐了該地區21.4%的複合年成長率,確保亞太地區繼續引領全球生產成長。
北美在產生收入中扮演著至關重要的角色,這主要得益於美國的推動。美國擁有22億美元的2025會計年度國家舉措計畫預算,該計畫向醫療保健、國防和能源領域提供津貼。高價值的醫療保健計畫佔據了很大一部分需求,其中基於奈米纖維的再生醫學植入的臨床試驗獲得了美國食品藥物管理局(FDA)的快速通道簡審類,加速了商業化進程。國防機構正在支持過濾技術和防護衣的研發,從而加強國內供應鏈。加拿大的潔淨科技激勵政策以及與汽車產業的接近性,促進了電池材料領域的跨國合作。在德國和法國嚴格的永續性框架的推動下,歐洲引領著可生物分解奈米纖維包裝和暖通空調解決方案的市場。來自「地平線歐洲」計畫的津貼正在培育產學研叢集,加速規模化生產和標準化進程,而REACH法規的合規指南則提供了監管確定性。儘管歐盟的成長速度落後於亞太地區,但歐盟禁止使用某些一次性塑膠的指令正在食品服務和個人保健產品產業催生對替代品的需求。在南美洲、中東和非洲,旨在緩解飲用水短缺和提高農業效率的項目正在蓬勃發展,海水淡化和緩釋肥料中奈米纖維膜的早期應用推動了利潤成長。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 來自醫療和製藥行業的需求增加
- 電動車超級工廠對高比表面積電池隔膜的需求
- 高效率過濾介質的需求
- 汽車產業的成長
- 紡織業的擴張
- 市場限制因素
- PAN原料價格波動
- 碳奈米纖維尺寸微小、結構複雜,難以從實驗室規模過渡到工廠規模。
- 健康與安全問題
- 價值鏈分析
- 波特五力分析
- 技術概述
- 專利分析
第5章 市場規模與成長預測
- 依產品類型
- 聚合物奈米纖維
- 碳奈米纖維
- 複合奈米纖維
- 金屬和金屬氧化物奈米纖維
- 陶瓷奈米纖維
- 碳水化合物基奈米纖維
- 透過使用
- 水和空氣的過濾
- 醫學領域
- 儲能
- 汽車和運輸業
- 電子設備
- 紡織品
- 其他用途
- 透過製造技術
- 靜電紡絲(針式)
- 無針靜電紡絲
- 溶液吹紡法
- 強制紡絲/旋轉噴射紡絲
- 熔噴法
- 按地區
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 其他亞太國家
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 其他歐洲國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 南非
- 其他中東和非洲國家
- 亞太地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Applied Sciences Inc.
- Argonide Corporation
- Asahi Kasei Corporation
- Chuetsu Pulp & Paper Co. Ltd.
- Donaldson Company Inc.
- DuPont
- Esfil Tehno AS
- eSpin Technologies Inc.
- FibeRio Technology Corp.
- Hollingsworth & Vose
- IREMA-Filter GmbH
- Japan Vilene Company Ltd.
- NanoLayr Ltd
- Nanoval GmbH & Co. KG
- NIPPON PAPER INDUSTRIES CO., LTD.
- Pardam SRO
- Rengo Co., Ltd.
- Sappi Ltd.
- SNC Fiber
- Spur AS
- Teijin Limited
- Toray Industries Inc.
- US Global Nanospace Inc.
第7章 市場機會與未來展望
According to Mordor Intelligence, the nanofiber market size was valued at USD 1.58 billion in 2025 and estimated to grow from USD 1.9 billion in 2026 to reach USD 4.74 billion by 2031, at a CAGR of 20.07% during the forecast period (2026-2031).
This report is Segmented by Product Type (Polymeric Nanofiber, Carbon Nanofiber, and More), Application (Water and Air Filtration, Medical, and More), Manufacturing Technology (Electrospinning (Needle-Based), Needle-Less Electrospinning, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Nanofiber Market Trends and Insights
Increasing Demand from Medical and Pharmaceutical Industries
Nanofiber-based drug delivery platforms now achieve 85%-plus drug loading and sustained release for up to 96 hours, sharply improving therapeutic adherence and lowering systemic toxicity. Their extracellular-matrix-like architecture supports superior cell attachment, enabling next-generation tissue scaffolds that cut healing time and minimize scarring. Hospitals adopting advanced wound dressings cite patient-turnover gains that translate to reduced care costs, strengthening procurement appetite. Regulatory pathways for nanofiber scaffolds in orthopedics continue to clarify, lowering time-to-market risk for developers. Collectively, these medical breakthroughs elevate reimbursement prospects and reinforce recurring demand across high-value healthcare channels.
Demand for High-Surface-Area Battery Separators in EV Gigafactories
Electrospun nanofiber separators now withstand 150 °C thermal excursions without dimensional loss, addressing critical EV safety standards. Enhancements in ion conductivity are extending fast-charge capability by up to 40% while preserving cycle life, a gain attracting procurement from Asian and US gigafactories. Automated roll-to-roll lines scale output beyond 3 million m2 annually, narrowing cost gaps with conventional polyolefin films. Capital deployment by major cell producers is locking in multiyear supply contracts, providing predictable volume visibility for nanofiber vendors. National clean-mobility incentives in China and the United States further amplify separator adoption in new cell chemistries.
Volatile PAN Feedstock Prices
PAN constitutes about 90% of carbon nanofiber precursors, and its spot price fluctuates by up to 20% annually, eroding margin stability for downstream suppliers. Supply disruptions linked to acrylonitrile feed shortages intensify inventory risk, prompting producers to pursue petroleum-asphaltene or lignin alternatives that can cut raw-material cost below USD 9 per kg while raising sustainability credentials. Transition timeframes remain lengthy due to impurity management and variable mechanical performance, prolonging exposure to PAN volatility. Buyers hedge through index-linked contracts, but long-term pricing visibility is still limited, dampening aggressive capacity expansion.
Other drivers and restraints analyzed in the detailed report include:
- Demand for High-Efficiency Filtration Materials
- Growth in the Automotive Industry
- Difficulty in Shifting Carbon Nanofibers from Lab to Plant Scale
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The polymeric category anchors 41.20% of 2025 revenue, driven by well-established electrospinning lines and broad chemical versatility across packaging, filtration and biomedical devices. Carbohydrate-based grades, while smaller in volume, accelerate at a 26.2% CAGR as end-users pursue biodegradable, bio-sourced alternatives aligned with global circular-economy mandates. Cellulose nanofibers rival aramid tensile strength yet biodegrade under ambient conditions, compelling packaging suppliers to adopt them in single-use applications. Chitin nanofibers attract wound-care producers due to inherent antimicrobial traits, spurring investment in shellfish-waste valorization. Carbon nanofibers find significant use in specialty energy and electronics applications; however, production scale and cost challenges are restraining immediate growth.
Momentum for carbohydrate-based products is amplified by brand-owner commitments to cut fossil plastic use. Legislative bans on single-use synthetic fibers in several EU states compound this pull. Composite nanofibers, which blend polymer and ceramic phases, play a significant role in high-temperature filtration niches. Metal and metal-oxide grades serve catalytic and sensing applications where elevated conductivity or photocatalytic activity is critical. Ceramic nanofibers retain demand for thermal insulation in aerospace and furnace linings. As raw-material R&D migrates toward forestry and agricultural waste streams, cost curves are expected to converge, bolstering the broader nanofiber market.
Complete Report Scope:
- By Product Type
- Polymeric Nanofiber
- Carbon Nanofiber
- Composite Nanofiber
- Metal and Metal Oxide Nanofiber
- Ceramic Nanofiber
- Carbohydrate-based Nanofiber
- By Application
- Water and Air Filtration
- Medical
- Energy Storage
- Automotive and Transportation
- Electronics
- Textiles
- Other Applications
- By Manufacturing Technology
- Electrospinning (Needle-Based)
- Needle-less Electrospinning
- Solution Blow Spinning
- ForceSpinning/Rotary Jet Spinning
- Melt Blowing
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific commands 37.60% of 2025 revenue, with China, Japan and South Korea benefitting from deep electronic supply chains and government-backed nanotech initiatives. Robust EV production bases in China elevate local demand for nanofiber separators, while strict environmental guidelines accelerate uptake in air-filtration retrofits. Regional stimulus funds earmarked for sustainable materials further de-risk investment in lignin-derived nanofiber plants. This ecosystem underpins a 21.4% regional CAGR, ensuring Asia-Pacific continues to anchor global volume growth.
North America, driven by the U.S. with its USD 2.2 billion FY-25 National Nanotechnology Initiative budget, which allocates grants to medical, defense, and energy sectors, plays a significant role in global revenue generation. High-value healthcare projects dominate demand; clinical trials for nanofiber-based regenerative implants secure FDA fast-track status, accelerating commercialization. Defense agencies sponsor filtration and protective-wear R&D, fortifying domestic supply chains. Canada's clean-technology incentives and proximity to automotive hubs kindle cross-border collaboration in battery materials. Europe, driven by Germany and France's stringent sustainability frameworks, leads in the market for biodegradable nanofiber packaging and HVAC solutions. Horizon Europe grants foster university-industry clusters that fast-track scale-up and standardization, while REACH compliance guidelines supply regulatory certainty. Although growth rates trail Asia-Pacific, EU directives banning select single-use plastics are opening replacement opportunities in food-service and personal-care products. In South America, the Middle East, and Africa, where programs addressing potable-water scarcity and enhancing agricultural efficiency are gaining traction, revenue is driven by the early adoption of nanofiber membranes in desalination and controlled-release fertilizers.
- Applied Sciences Inc.
- Argonide Corporation
- Asahi Kasei Corporation
- Chuetsu Pulp & Paper Co. Ltd.
- Donaldson Company Inc.
- DuPont
- Esfil Tehno AS
- eSpin Technologies Inc.
- FibeRio Technology Corp.
- Hollingsworth & Vose
- IREMA-Filter GmbH
- Japan Vilene Company Ltd.
- NanoLayr Ltd
- Nanoval GmbH & Co. KG
- NIPPON PAPER INDUSTRIES CO., LTD.
- Pardam SRO
- Rengo Co., Ltd.
- Sappi Ltd.
- SNC Fiber
- Spur AS
- Teijin Limited
- Toray Industries Inc.
- US Global Nanospace Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Demand from the Medical and Pharmaceutical Industries
- 4.2.2 Demand for High-Surface-Area Battery Separators in EV Gigafactories
- 4.2.3 Demand for High-Efficiency Filtration Materials
- 4.2.4 Growth in the Automotive Industry
- 4.2.5 Expansion in the Textile Industry
- 4.3 Market Restraints
- 4.3.1 Volatile PAN Feedstock Prices
- 4.3.2 Difficulty in Shift of Carbon Nanofibers from Lab Scale to Plant Scale due to Small Size and Complexity
- 4.3.3 Health and Safety Concerns
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
- 4.6 Technology Snapshot
- 4.7 Patent Analysis
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Polymeric Nanofiber
- 5.1.2 Carbon Nanofiber
- 5.1.3 Composite Nanofiber
- 5.1.4 Metal and Metal Oxide Nanofiber
- 5.1.5 Ceramic Nanofiber
- 5.1.6 Carbohydrate-based Nanofiber
- 5.2 By Application
- 5.2.1 Water and Air Filtration
- 5.2.2 Medical
- 5.2.3 Energy Storage
- 5.2.4 Automotive and Transportation
- 5.2.5 Electronics
- 5.2.6 Textiles
- 5.2.7 Other Applications
- 5.3 By Manufacturing Technology
- 5.3.1 Electrospinning (Needle-Based)
- 5.3.2 Needle-less Electrospinning
- 5.3.3 Solution Blow Spinning
- 5.3.4 ForceSpinning/Rotary Jet Spinning
- 5.3.5 Melt Blowing
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-Level Overview, Market-Level Overview, Core Segments, Financials, Strategic Info, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Applied Sciences Inc.
- 6.4.2 Argonide Corporation
- 6.4.3 Asahi Kasei Corporation
- 6.4.4 Chuetsu Pulp & Paper Co. Ltd.
- 6.4.5 Donaldson Company Inc.
- 6.4.6 DuPont
- 6.4.7 Esfil Tehno AS
- 6.4.8 eSpin Technologies Inc.
- 6.4.9 FibeRio Technology Corp.
- 6.4.10 Hollingsworth & Vose
- 6.4.11 IREMA-Filter GmbH
- 6.4.12 Japan Vilene Company Ltd.
- 6.4.13 NanoLayr Ltd
- 6.4.14 Nanoval GmbH & Co. KG
- 6.4.15 NIPPON PAPER INDUSTRIES CO., LTD.
- 6.4.16 Pardam SRO
- 6.4.17 Rengo Co., Ltd.
- 6.4.18 Sappi Ltd.
- 6.4.19 SNC Fiber
- 6.4.20 Spur AS
- 6.4.21 Teijin Limited
- 6.4.22 Toray Industries Inc.
- 6.4.23 US Global Nanospace Inc.
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment
- 7.2 Increasing R&D and High-potential Market for Cellulosic Nanofibers

 奈米纖維市場:2026-2032年全球市場預測(依產品類型、技術、直徑範圍、應用及最終用途產業分類)
 奈米纖維市場:按產品類型、應用和地區分類
 2026年全球奈米纖維市場報告
 奈米纖維市場規模、佔有率、趨勢和預測:按產品、技術、應用和地區分類,2026-2034年2026年全球醫用奈米纖維材料市場報告2026年全球奈米科技服飾市場報告
 奈米纖維傷口敷料市場預測至2032年:按材料類型、傷口類型、功能特性、最終用戶和地區分類的全球分析
 聚合物奈米纖維:全球市場佔有率和排名、總收入和需求預測(2025-2031 年)
 奈米纖維市場-全球產業規模、佔有率、趨勢、機會和預測(按產品、技術、應用、地區和競爭細分,2020-2030 年)纖維素奈米纖維標籤市場預測(至 2032 年):按產品類型、來源、應用、最終用戶和地區進行的全球分析