


 |
市場調查報告書
商品編碼
2121535
木質素產品:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Lignin Products - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 預測,木質素產品市場將從 2025 年的 7.2942 億美元成長到 2026 年的 7.6064 億美元,然後在 2031 年達到 9.3799 億美元,2026 年至 2031 年的複合成長率為 4.28%。
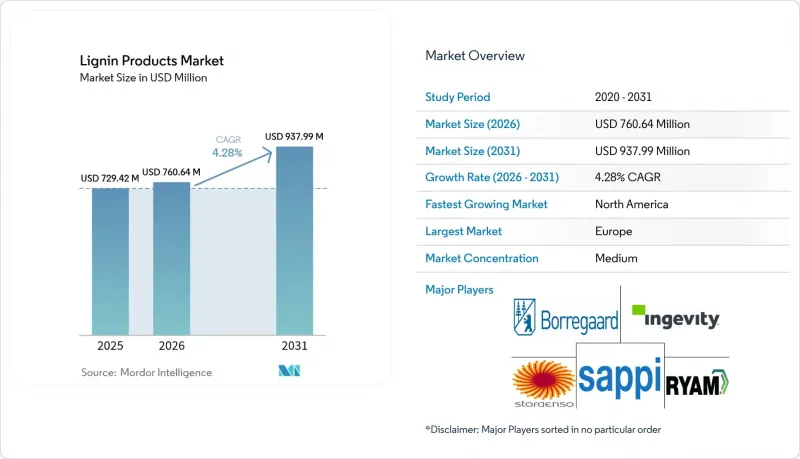
本報告按原料(亞硫酸鹽製漿法、纖維素乙醇法、牛皮紙漿製漿法、蘇打製漿法)、產品類型(磺酸鹽、硫酸鹽木質素及其他產品類型)、應用領域(分散劑、混凝土添加劑及其他應用領域)和地區(亞太地區、北美地區、歐洲地區、南美地區以及中東和非洲地區)進行細分。市場預測以美元計價。
全球木質素產品市場趨勢及分析
對高性能混凝土外加劑的需求日益成長
隨著亞太地區和拉丁美洲基礎設施的擴張,對高性能減水劑的需求日益成長,這些減水劑既能提高混凝土流動性,又能減少水泥用量。木質素基外加劑可降低水灰比,提高抗壓強度15-20%,減少水泥用量8-12%。致力於獲得LEED認證的建設公司青睞這些生物基解決方案,因為它們可以減少高層建築和交通基礎設施項目中的碳排放。中國和印度的綠色建築標準現已推薦使用天然來源的外加劑,為加速其商業化提供了監管支持。製造商正在擴大產能,以滿足大規模都會區和高速公路項目對高性能混凝土的強制性要求。隨著智慧城市投資的穩定成長,預計中期內對木質素基超塑性立管的需求將持續旺盛。
木質素基飼料粘合劑在動物營養領域的廣泛應用。
歐洲限制使用抗生素類生長促進劑的法規正促使飼料生產商轉向磺酸鹽粘合劑。研究表明,與糖蜜基系統相比,木質素磺酸鹽黏合劑可使顆粒飼料的耐久性提高25-30%,從而減少飼料粉塵和運輸損失。某些木質素組分具有益生元特性,能夠活化反芻動物的腸道微生物群,使飼料生產商能夠以溢價出售。丹麥和荷蘭的生產商報告稱,透過從當地紙漿廠採購本地生產的木質素衍生物,物流成本降低了12-15%。隨著大型整合公司致力於打造無抗生素價值鏈,北美生產商也採取類似的策略。由於亞太地區的畜牧養殖戶轉向高附加價值蛋白質並尋求提高飼料轉換率,長期前景仍然強勁。
萃取過程導致品質差異
硫酸鹽木質素、亞硫酸鹽木質素和鹼木質素在硫含量和分子量上的差異,使得對規格要求統一的用戶採購變得複雜。亞硫酸鹽木質素的硫含量比其他木質素高出20-30%,這會影響樹脂的固化速率,並需要單獨的加工過程。下游企業需要維護平行的庫存管理和雙重認證程序,這會使供應鏈支出增加8-12%。小規模造紙廠很少有分析實驗室來對每批產品進行認證,這限制了它們進入低利潤通路。在通用測試標準建立和基於雲端的追溯平台成熟之前,短期內仍存在不確定性。因此,品質標準化對於在專業領域實現更廣泛的應用至關重要。
細分市場分析
預計到2025年,與亞硫酸鹽紙漿生產相關的木質素產品市場將佔全球市場價值的76.62%,佔據市場主導地位,這主要得益於其充足的供應和作為分散劑的成熟性能。雖然纖維素乙醇工廠的供應量遠小於亞硫酸鹽紙漿,但其利潤率較高,年複合成長率達4.95%,預計到2031年將成為最具活力的供應來源。基於美國可再生燃料標準(RFS)和歐盟可再生能源指令II(RED-II)的生產獎勵正推動生物精煉採用木質素分離設備,從而產生相當於乙醇銷售額12-15%的收入。主要在歐洲和中國運營的亞硫酸鹽紙漿生產商透過最佳化回收率和推出用於混凝土和飼料的客製化等級產品來維持其市場地位。蘇打紙漿工藝在印度和東南亞仍保持著重要的市場地位,該工藝利用農業廢棄物生產低灰分木質素,用於當地的紡織化學品。
與硫酸鹽紙漿衍生的木質素相比,纖維素牛皮紙漿衍生的木質素通常具有更低的灰分含量和更窄的分子量分佈,從而為特種聚合物領域帶來更高的附加價值。汽車複合材料的試點用戶高度重視其可預測的流變性能,有助於連續纖維紡絲。隨著乙醇生產商擴大產能,這種高品質木質素的供應量將會增加,從而加強生質燃料和特用化學品價值鏈之間的連結。雖然亞硫酸鹽的產量遠超過其他來源,但如今的競爭格局不再僅僅取決於產量,而是取決於每噸價值,尤其是在碳相關收入來源影響盈利的情況下。
區域分析
到2025年,歐洲將佔全球市場價值的33.55%。這得歸功於其一體化的林業產業和嚴格的氣候政策,這些政策正在加速木質素的早期應用。芬蘭和瑞典的紙漿廠正在維修提取生產線以確保新的收入來源,而德國的混凝土和汽車產業預計將保持穩定的需求。 REACH化學品法規鼓勵複合材料生產商轉向生物基原料,從而改善了需求前景。來自「地平線歐洲」計畫的研究津貼正在加速香草醛和碳纖維領域的試點項目,鞏固了該地區在創新領域的領先地位。
預計北美將維持最高的成長率,到2031年複合年成長率將達到5.08%。這主要歸功於聯邦政府強制使用纖維素燃料擴大了木質素的供應,以及汽車行業為減輕車身重量而做出的努力提高了對永續複合材料的要求。在美國,用作混凝土外加劑的木質素產品市場規模正在擴大,這要歸功於旨在實現橋樑和交通基礎設施現代化的「兩黨基礎設施法」。在各省碳定價機制的支持下(該機制鼓勵使用低排放材料),加拿大林業公司正利用其豐富的北方森林資源,實現業務多元化,不再局限於紙漿生產,而是轉向特種木質素領域。此外,墨西哥的建築熱潮也創造了對混凝土外加劑進口的需求,從而補充了整個北美大陸的整體需求。
亞太地區尚處於應用初期,但成長潛力巨大。中國快速的都市化推動了混凝土消耗的成長,而基於木質素的高性能減水劑也開始被納入國家標準。在印度,利用農業廢棄物進行鹼法製漿的工藝正在大規模推廣,生產出具有成本競爭力的木質素,可用於當地飼料和染料分散劑。日本正在利用木質素的芳香骨架生產電子設備樹脂,而韓國已將木質素衍生化學品納入綠色採購清單。東協正在進行的基礎設施建設和不斷擴大的肉類生產正在創造多元化的需求,但標準的統一性對於跨境貿易至關重要。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 市場分析與定義的前提條件
- 分析範圍
第2章 分析方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 對高性能混凝土外加劑的需求日益成長
- 動物營養領域中木質素基飼料粘合劑的應用現狀
- 針對紙漿廠產品進行循環收入估值
- 從木質素到香草醛的突破性生物轉化途徑。
- 汽車產業正在推廣木質素衍生的生物碳纖維。
- 市場限制因素
- 萃取工藝之間的品質差異
- 與醣類衍生的生物芳香化合物的競爭
- 木質素產品缺乏國際標準
- 價值鏈分析
- 波特五力分析
第5章:預測市場規模與成長率
- 按原料
- 亞硫酸鹽紙漿工藝
- 纖維素基乙醇
- 牛皮紙漿工藝
- 蘇打漿工藝
- 依產品類型
- 磺酸鹽
- 硫酸鹽木質素
- 高純度木質素
- 蘇打木質素
- 其他產品類型
- 透過使用
- 分散劑
- 混凝土外加劑
- 動物飼料
- 樹脂
- 其他用途
- 按地區
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- 東南亞國協
- 其他亞太國家
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 俄羅斯
- 北歐國家
- 其他歐洲國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 南非
- 其他中東和非洲國家
- 亞太地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率和排名分析
- 公司簡介
- Borregaard AS
- Burgo Group SpA
- Domsjo Fabriker AB
- Ingevity
- Lignin Industries AB
- MetGen
- Metsa Group
- NIPPON PAPER INDUSTRIES CO., LTD.
- RYAM
- Sappi Ltd
- Stora Enso
- Suzano S/A
- UPM Biochemicals
- Valmet
第7章 市場機會與未來展望
According to Mordor Intelligence, the lignin products market size is expected to grow from USD 729.42 million in 2025 to USD 760.64 million in 2026 and is forecast to reach USD 937.99 million by 2031 at 4.28% CAGR over 2026-2031.
This report is Segmented by Source (Sulfite Pulping, Cellulosic Ethanol, Kraft Pulping, and Soda Pulping), Product Type (Lignosulfonate, Kraft Lignin, and Other Product Types), Application (Dispersant, Concrete Additive, and Other Applications), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Lignin Products Market Trends and Insights
Rising Demand for High-Performance Concrete Admixtures
Infrastructure expansion across Asia-Pacific and Latin America raises the need for superplasticizers that improve flow while lowering cement consumption. Lignin-based admixtures reduce water-cement ratios, boosting compressive strength by 15-20% and cutting cement use by 8-12%. Construction firms pursuing LEED certification favor these bio-based solutions because they lower embodied carbon in high-rise and transportation projects. Green-building codes in China and India now endorse natural admixtures, providing a regulatory pull that accelerates commercialization. Producers scale up capacity to keep pace with large metro and highway contracts that specify performance concrete. Steady gains in smart-city investments anticipate durable demand for lignin superplasticizers through the medium term.
Uptake of Lignin-Based Feed Binders in Animal Nutrition
European regulations that restrict antibiotic growth promoters have moved feed formulators toward lignosulfonate binders. Studies show 25-30% better pellet durability versus molasses systems, translating into lower feed dust and reduced transport losses. Specific lignin fractions exhibit prebiotic activity that enhances ruminant gut microbiota, allowing feed companies to price at a premium. Danish and Dutch manufacturers report 12-15% logistics cost savings after sourcing local lignin derivatives from regional pulp mills. North American producers adopt similar strategies as large integrators target antibiotic-free supply chains. The long-term outlook remains strong as Asia-Pacific livestock operators shift toward higher-value protein and require efficiency gains in compound feed.
Quality Variability Across Extraction Processes
Differences in sulfur content and molecular weight between kraft, sulfite, and soda lignin complicate procurement for users that require consistent specifications. Sulfite variants carry 20-30% higher sulfur, impacting resin cure kinetics and demanding tailored processing protocols. Downstream firms maintain parallel inventories and dual qualification programs, inflating supply-chain spending by 8-12%. Smaller mills rarely possess analytical labs to certify each batch, restricting market access to low-margin outlets. Near-term uncertainty remains until shared testing standards emerge and cloud-based traceability platforms mature. Quality harmonization is therefore pivotal for broader adoption in specialty segments.
Other drivers and restraints analyzed in the detailed report include:
- Valorisation of Pulp-Mill Side-Streams for Circular Revenue
- Breakthrough Lignin-to-Vanillin Bioconversion Routes
- Competition from Sugar-Derived Bio-Aromatics
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The lignin products market size linked to sulfite pulping totaled the bulk of global value, securing 76.62% in 2025 on the back of abundant volumes and well-known performance in dispersants. Cellulosic ethanol plants offer much smaller but higher-margin flows, and their 4.95% CAGR makes them the most dynamic source category to 2031. Production incentives under the U.S. Renewable Fuel Standard and EU RED-II encourage biorefineries to integrate lignin separation units, adding revenue equal to 12-15% of ethanol sales. Sulfite operators, chiefly in Europe and China, defend position by optimizing recovery yields and launching tailor-made grades for concrete and feed. Soda pulping keeps niche importance in India and Southeast Asia, processing agricultural residues into low-ash lignin for regional textile chemicals.
Cellulosic ethanol lignin typically displays lower ash and narrower molecular-weight distribution than kraft material, granting it a premium in specialty polymers. Pilot users in automotive composites value the predictable rheology that aids continuous fiber spinning. As ethanol producers scale capacity, supply of this high-quality lignin grows, tightening integration between biofuel and specialty chemical chains. Although sulfite volumes dwarf other sources, competitive dynamics hinge on value per ton rather than tonnage alone, especially as carbon revenue streams influence profitability.
Complete Report Scope:
- By Source
- Sulfite Pulping
- Cellulosic Ethanol
- Kraft Pulping
- Soda Pulping
- By Product Type
- Lignosulfonate
- Kraft Lignin
- High-Purity Lignin
- Soda Lignin
- Other Product Types
- By Application
- Dispersant
- Concrete Additive
- Animal Feed
- Resins
- Other Applications
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Europe held 33.55% of global value in 2025 because integrated forest industries and strict climate policies foster early lignin valorization. Pulp mills in Finland and Sweden retrofit extraction lines to capture new revenue, while German concrete and automotive sectors absorb steady volumes. REACH chemicals regulation nudges formulators toward bio-derived inputs, improving demand visibility. Horizon Europe research grants accelerate pilot deployments in vanillin and carbon-fibre, solidifying the region's innovation leadership.
North America posts the fastest 5.08% CAGR through 2031 as federal cellulosic fuel mandates widen lignin supply and automotive lightweighting efforts raise the bar on sustainable composites. The lignin products market size for concrete admixtures climbs in the United States on the back of the Bipartisan Infrastructure Law, which modernizes bridges and transit. Canadian forestry companies leverage abundant boreal resources to diversify beyond pulp into specialty lignin, supported by provincial carbon-pricing mechanisms that favor low-emission materials. Mexico's construction boom also creates room for admixture imports, rounding out continental demand.
Asia-Pacific stands at an earlier adoption curve yet offers vast upside. China's rapid urbanization elevates concrete consumption, and state standards begin to recognize lignin superplasticizers. India scales soda pulping for agri-residue, producing cost-competitive lignin for local feed and dye dispersants. Japan exploits lignin's aromatic backbone in electronics resins, while South Korea includes lignin-based chemicals in green-procurement lists. Ongoing ASEAN infrastructure initiatives and growing meat production foster multipronged demand, though standards harmonization will be critical for cross-border trade.
- Borregaard AS
- Burgo Group S.p.A.
- Domsjo Fabriker AB
- Ingevity
- Lignin Industries AB
- MetGen
- Metsa Group
- NIPPON PAPER INDUSTRIES CO., LTD.
- RYAM
- Sappi Ltd
- Stora Enso
- Suzano S/A
- UPM Biochemicals
- Valmet
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Demand for High-Performance Concrete Admixtures
- 4.2.2 Uptake of Lignin-Based Feed Binders in Animal Nutrition
- 4.2.3 Valorisation of Pulp-Mill Side-Streams for Circular Revenue
- 4.2.4 Breakthrough Lignin-To-Vanillin Bioconversion Routes
- 4.2.5 Automotive Push for Lignin-Derived Bio-Carbon Fibre
- 4.3 Market Restraints
- 4.3.1 Quality Variability Across Extraction Processes
- 4.3.2 Competition from Sugar-Derived Bio-Aromatics
- 4.3.3 Lack of International Lignin Product Standards
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitute Products
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Source
- 5.1.1 Sulfite Pulping
- 5.1.2 Cellulosic Ethanol
- 5.1.3 Kraft Pulping
- 5.1.4 Soda Pulping
- 5.2 By Product Type
- 5.2.1 Lignosulfonate
- 5.2.2 Kraft Lignin
- 5.2.3 High-Purity Lignin
- 5.2.4 Soda Lignin
- 5.2.5 Other Product Types
- 5.3 By Application
- 5.3.1 Dispersant
- 5.3.2 Concrete Additive
- 5.3.3 Animal Feed
- 5.3.4 Resins
- 5.3.5 Other Applications
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Russia
- 5.4.3.6 NORDIC Countries
- 5.4.3.7 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share/Ranking Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Borregaard AS
- 6.4.2 Burgo Group S.p.A.
- 6.4.3 Domsjo Fabriker AB
- 6.4.4 Ingevity
- 6.4.5 Lignin Industries AB
- 6.4.6 MetGen
- 6.4.7 Metsa Group
- 6.4.8 NIPPON PAPER INDUSTRIES CO., LTD.
- 6.4.9 RYAM
- 6.4.10 Sappi Ltd
- 6.4.11 Stora Enso
- 6.4.12 Suzano S/A
- 6.4.13 UPM Biochemicals
- 6.4.14 Valmet
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

 木質素基染料分散劑市場:全球市場預測,2026-2032年木質素基分散劑市場:全球市場預測(2026-2032年)
 木質素衍生石墨烯市場規模、佔有率和成長分析:按產品類型、生產方法、應用、最終用戶、形態和地區分類-產業預測,2026-2033年
 全球木質素市場(2027-2037)木質素市場:2026-2032年全球市場預測(依產品種類、原料、形態、純度及應用分類)硫酸鹽木質素市場:依原料、形態、等級及應用分類-2026-2032年全球市場預測
 阿魏酸市場規模、佔有率和成長分析:按原料、形態、應用、終端用戶產業、純度、分銷管道和地區分類-2026-2033年產業預測
 木質素市場規模、佔有率和成長分析:按產品類型、原料、木質素類型、最終用途、應用和地區分類-2026-2033年產業預測
 木質素產品市場報告:按產品、原料、應用和地區分類(2026-2034 年)
 木質素市場規模、佔有率和趨勢分析報告:按產品、應用、地區和細分市場預測(2026-2033 年)