


 |
市場調查報告書
商品編碼
2121277
技術陶瓷:市場佔有率分析、產業趨勢與統計、成長預測(2026-2031)Technical Ceramics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
根據 Mordor Intelligence 估計,到 2026 年,技術陶瓷市值將達到 100.9 億美元,高於 2025 年的 93.8 億美元,預計到 2031 年將達到 145.4 億美元。
預計從 2026 年到 2031 年,其複合年成長率將達到 7.58%。
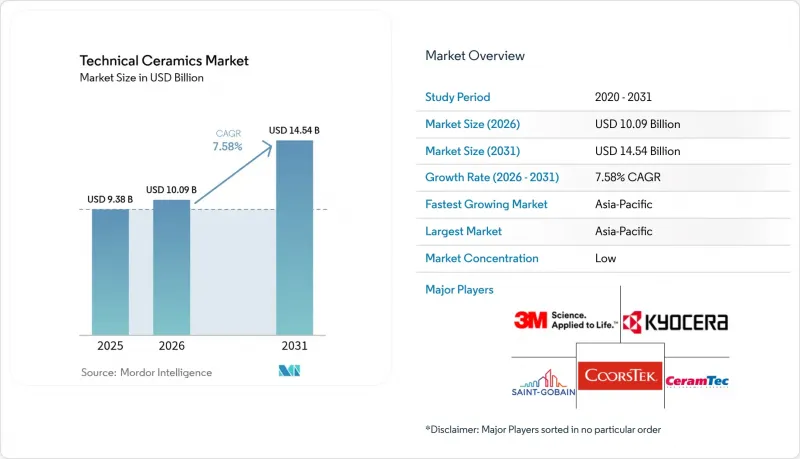
本報告按產品類型(單片陶瓷、陶瓷基質複合材料等)、材料分類(氧化物陶瓷、非氧化物陶瓷、其他)、最終用戶行業(電氣和電子、汽車、其他)、主要應用(絕緣體和基板、溫度控管組件、其他)以及地區(亞太地區、北美、歐洲、南美、中東和非洲)進行分類。
全球技術陶瓷市場趨勢與洞察
擴大亞太地區的半導體和家用電子電器生產
台灣、中國當地、日本和韓國晶圓廠的擴張正在重塑對氮化鋁和碳化矽基板的需求基準,這些基板能夠承受超過1000 度C的峰值結溫,同時確保介電完整性。採用氮化鎵架構的晶片設計人員正在迅速提高其熱預算,使其超出傳統金屬導線架的能力範圍,因此陶瓷封裝對於提高產能至關重要。京瓷正在日本投資4.7億美元建造一條專用生產線,以滿足下一代處理器節點對陶瓷基板的需求。雖然與半導體潔淨室相比,窯爐檢驗週期更長,這使得基板生長週期與光刻批量生產計劃的同步更具挑戰性,但一級裝置製造商目前正在簽署多年期的啟動協議以確保供應。同時,地方政府也支持先進材料叢集,以減少對海外原料的依賴。這項政策舉措可望縮短前置作業時間並緩解價格波動。
電動車動力傳動系統的溫度控管需求
到2024年,全球電動車出貨量將超過1500萬輛。如今,幾乎所有平台都在進行升級,目標是採用800V電氣架構,以更小的逆變器提供更大的功率。碳化矽(SiC)功率模組的散熱速度是矽元件的三倍,但其允許的結溫範圍仍然很窄,因此導熱係數超過200 W/mK的陶瓷散熱器是滿足此設計要求的理想選擇。 CeramTec的「晶片封裝散熱器」解決方案在降低熱阻的同時,保持了絕緣隔離。這種組合即使在高振動的汽車環境中也能延長模組壽命。汽車製造商對價格非常敏感,但考慮到因熱故障導致的保固責任,可靠的陶瓷產品,即使單價更高,也成為他們採購的決定性因素。隨著中國、歐洲和美國汽車電氣化進程的加速,對陶瓷基板、匯流排和凝膠塗層冷卻板的需求也隨之成長。
固有脆性和加工損耗問題
為了同時實現耐熱性和耐磨性,所需的硬度會增加燒結後研磨過程中斷裂的風險。 20-30%的產量下降會推高單位成本並延長前置作業時間。纖維增強陶瓷基質複合材料可以抑制裂紋擴展,但額外的層壓和浸漬過程使工藝變得過於複雜,以至於其帶來的耐久性提升被抵消。積層製造提供了一種近淨成形的替代方案,但其可用材料種類和生產能力仍落後於傳統的壓製成型工藝,限制了其在原型製造之外的應用。
細分市場分析
2025年,單片陶瓷在技術陶瓷市場中佔據46.10%的佔有率,這得益於成熟的壓制和燒結生產線能夠實現大規模、均勻的品質生產。隨著工業OEM廠商用壽命比鋼製零件更長的氧化鋁體替代幫浦、噴嘴和絕緣體,預計該細分市場仍將維持中等個位數的成長。同時,複合材料材料將以8.72%的複合年成長率推動整個技術陶瓷市場的發展,吸引航太和國防領域的預算,這些領域對減重30%以上和耐熱性超過1500 度C的要求極高。到2026年,光是引擎熱部件領域預計就將佔據技術陶瓷市場11.8億美元的佔有率。加工技術的突破,例如快速強制空氣燒結,已將緻密化過程從數小時縮短至數分鐘,從而降低了能源成本,並縮小了與整體式產品的價格差距。隨著這些效率的提高,複合材料有望蠶食整體式產品的市場佔有率,但它們不會完全取代整體式產品,因為可預測的收縮率和低廢品率在汽車和工業工廠領域仍然具有價值。
塗層產業正扮演著過渡的角色。原始設備製造商(OEM)可以透過在現有金屬部件上噴塗氧化鋯或碳化矽,逐步提高熱通量,而無需重新設計整個組件。這種改進方法廣泛應用於石油化學燃燒器和柴油顆粒過濾器,這些設備由於停產而預算有限。陶瓷纖維雖然用量較小,但在隔熱材料市場仍具有重要影響力。耐溫高達度C的填充氣凝膠的纖維氈正被應用於液化天然氣運輸船的貨艙中,這再次表明,高性能產品在小規模的細分市場中維持著高價。
由於原料供應充足且製程控制成熟,氧化鋁、氧化鋯和莫來石等氧化物材料在2025年佔據了62.80%的銷售額。這些材料是眾多產業電容器中介電層和耐磨極板的基礎材料。同時,碳化矽、氮化矽以及新興的碳化硼等非氧化物材料由於其低密度和接近銅的熱導率,訂單成長速度正在加快。預計到2031年,非氧化物材料的年成長率將達到7.76%,透過滿足氧化物玻璃相無法承受的尖端裝置的需求,擴大技術陶瓷市場。儘管成本壁壘依然存在,但隨著生產線良率的提高和缺陷率降至5%以下,非氧化物材料的價格溢價正在縮小。法規帶來的更嚴格的燃油效率標準以及資料中心熱通量的增加都表明,這些高性能材料將擁有持續的長期發展動力。
在複合材料和混合材料領域,將非氧化物晶鬚或纖維與氧化物基體融合,可以實現韌性和導電性的協同效應。人們對摻鑭氧化鋁混合物的興趣日益濃厚,這種混合物能夠在高壓下承受介電擊穿,這一特性在電網級固體變壓器計畫中至關重要。這些交叉配方支持了這樣一種理論:未來市場佔有率的競爭將是“混合材料與單相材料之爭”,而不是“氧化物與非氧化物之爭”,這雖然增加了複雜性,但也拓寬了解決方案的範圍。
區域分析
預計到2025年,亞太地區將以43.40%的市佔率主導技術陶瓷市場,並預計在2031年之前以7.84%的複合年成長率成長。中國當地承擔了大部分氧化鋁粉末燒結工作,並在勞動密集型精加工表面處理工程擁有成本優勢,但不斷上漲的電費和遵守環保法規的費用正在縮小傳統的成本差距。日本正根據其半導體產業振興政策,調整業務結構,轉向超潔淨、高附加價值的基板。京瓷位於長崎的工廠預計2026年投產,屆時將使日本國內精細陶瓷產量提高10%。韓國的記憶體晶片產業中心正在推動對低缺陷氮化矽基基板的需求,而印度則透過古吉拉突邦和泰米爾納德邦的免稅措施吸引電動車供應鏈領域的投資者。此外,地方政府正在開發回收走廊,以回收廢棄的氧化鋯和氧化釔,從長遠來看,這可以減少對原料進口的依賴。
北美市場雖然成熟,但創新活力仍旺盛,佔全球陶瓷基質複合材料研發支出的近30%。美國佔據了航太渦輪機和醫療植入訂單的大部分佔有率,因此,符合ISO標準的燒結爐和USP VI級無塵室標準至關重要,而這些標準在監管較少的地區往往被忽略。聖戈班在紐約投資4000萬美元建設的觸媒撐體工廠將創造100個就業崗位,並縮短東海岸煉油廠的交貨時間。加拿大礦業公司供應礬土和稀土元素精礦,但大部分原料仍銷往亞洲的提煉。墨西哥正在崛起為電動車逆變器的組裝中心,因此,基板供應商開始考慮近岸外包策略,以規避美墨加協定(USMCA)原產地規則下的關稅。
歐洲約佔全球整體銷售額的五分之一,正努力在商業性成功與永續性要求之間尋求平衡。一家德國工具機項目,預計不久將需要數千平方公尺的固體氧化物電解槽板。該地區的化學品安全框架REACH強制要求嚴格的可追溯性,雖然合規成本支持現有企業,但卻減緩了新業務的推出。英國脫歐後的政策重點是加速先進材料的研發,力求在三年內將大學實驗室的突破性成果轉化為中試生產線,但由於國內需求有限,全面規模化生產將依賴出口市場。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 擴大亞太地區的半導體和家用電子電器生產
- 電動車動力傳動系統的溫度控管要求
- 在高附加價值醫療植入和醫療設備的應用範圍擴大
- 氫電解堆的組成部分
- 航太和衛星硬體製造
- 市場限制因素
- 高昂的資本成本和加工成本
- 固有脆性和加工損耗問題
- 關鍵礦產供應鏈中的風險
- 價值鏈分析
- 波特五力分析
- 專利分析
- 價格分析
第5章 市場規模與成長預測
- 依產品類型
- 單片陶瓷
- 陶瓷基質複合材料
- 陶瓷塗層
- 其他產品
- 按材料分類
- 氧化物陶瓷
- 非氧化物陶瓷
- 其他
- 按最終用戶行業分類
- 電氣和電子設備
- 車
- 能源與電力
- 醫學領域
- 航太/國防
- 其他終端用戶產業
- 主要用途
- 絕緣體和基板
- 溫度控管元件
- 耐磨零件和軸承
- 生物醫學植入和牙科
- 防護衣及防護工具
- 按地區
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 其他亞太國家
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 其他歐洲國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 南非
- 其他中東和非洲國家
- 亞太地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率(%)/排名分析
- 公司簡介
- 3M
- CeramTec GmbH
- CoorsTek Inc.
- Dyson Technical Ceramics
- Kyocera Corporation
- Mantec Technical Ceramics Ltd
- McDanel Advanced Ceramic Technologies
- Morgan Advanced Materials
- NGK SPARK PLUG CO., LTD.
- Ortech, inc.
- Rauschert GmbH
- Saint-Gobain
- Schott AG
- STC Material Solutions
第7章 市場機會與未來展望
According to Mordor Intelligence, technical ceramics market size in 2026 is estimated at USD 10.09 billion, growing from 2025 value of USD 9.38 billion with 2031 projections showing USD 14.54 billion, growing at 7.58% CAGR over 2026-2031.
This report is Segmented by Product Type (Monolithic Ceramics, Ceramic Matrix Composites, and More), Material Class (Oxide Ceramics, Non-Oxide Ceramics, Others), End-User Industry (Electrical and Electronics, Automotive, and More), Key Application (Insulators & Substrates, Thermal Management Components, and More), and Geography (Asia-Pacific, North America, Europe, South America, Middle East and Africa).
Global Technical Ceramics Market Trends and Insights
Expanding Semiconductor & Consumer-Electronics Output in Asia Pacific
Fab build-outs across Taiwan, mainland China, Japan, and South Korea are resetting the demand baseline for aluminum nitride and silicon carbide substrates that can survive peak junction temperatures exceeding 1,000 °C while ensuring dielectric integrity. Chip designers pursuing gallium nitride architectures are widening thermal budgets faster than legacy metal lead-frames can handle, making ceramic packages an essential throughput enabler. Kyocera is funneling USD 470 million into a dedicated Japanese line to synchronize ceramic substrate availability with next-generation processor nodes. Synchronizing substrate growth cycles with lithography ramp-ups remains difficult because kilns require longer validation loops than semiconductor clean-rooms, but tier-one device makers are now signing multi-year offtake agreements to lock in supply. Regional governments are simultaneously underwriting advanced-materials clusters to reduce reliance on overseas feedstocks, a policy move that could compress lead times and moderate pricing volatility.
EV Power-Train Thermal-Management Needs
Global EV shipments surpassed 15 million units in 2024, and nearly every platform upgrade now targets 800 V electrical architectures that squeeze more power through smaller inverters. Silicon carbide power modules dissipate heat at triple the rate of silicon devices, yet the allowable junction temperature band remains tight, creating a design window ideally served by ceramic heat spreaders boasting greater than 200 W/mK conductivity. CeramTec's chip-on-heatsink solution lowers thermal resistance while maintaining dielectric separation, a combination that lengthens module life in high-vibration automotive environments. Automakers are price-sensitive, but warranty liabilities linked to thermal failures tip purchasing decisions toward high-reliability ceramics despite higher unit costs. As fleet electrification accelerates in China, Europe, and the United States, demand for ceramic substrates, busbars, and gel-coated cooling plates is scaling in parallel.
Intrinsic Brittleness & Machining Losses
Hardness that delivers heat and wear resistance simultaneously increases fracture risk during post-sinter grinding. Yield losses of 20-30% inflate unit costs and lengthen lead times. Fiber-reinforced ceramic-matrix composites mitigate crack propagation but add layer-up and infiltration steps that offset durability gains with higher process complexity. Additive manufacturing offers near-net-shape alternatives, yet material palettes and throughput still lag conventional presses, limiting adoption outside prototyping.
Other drivers and restraints analyzed in the detailed report include:
- Rising Use in High-Value Medical Implants & Devices
- Hydrogen-Electrolyzer Stack Components
- Critical-Minerals Supply-Chain Exposure
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Monolithic ceramics retained 46.10% technical ceramics market share in 2025 due to mature press-and-sinter lines that deliver uniform quality at scale. The segment should still post mid-single-digit gains as industrial OEMs retrofit pumps, nozzles, and insulators with alumina bodies that outlast steel equivalents. Composite grades, however, will lift the overall technical ceramics market as their 8.72% CAGR attracts aerospace and defense budgets chasing weight savings above 30% alongside thermal ceilings beyond 1,500 °C. In 2026, the engine hot-section segment alone accounts for a USD 1.18 billion slice of the technical ceramics market size. Processing breakthroughs such as rapid forced-air sintering are collapsing densification steps from hours to minutes, trimming energy cost curves, and narrowing price spreads with monolithics. As these efficiencies propagate, composites are expected to erode monolithic share, but not displace them outright, because automotive and industrial plants still prize predictable shrinkage and low scrap rates.
The coatings niche serves as a transitional pathway: OEMs can spray zirconia or silicon carbide onto legacy metal parts, achieving incremental heat-flux gains without redesigning the entire assembly. This retrofit approach is popular in petrochemical burners and diesel particulate filters where shutdown budgets are tight. Ceramic fibers remain small in tonnage yet influential in insulation markets; aerogel-filled fiber quilts rated to 1,100 °C are seeing uptake in LNG ship cargo holds, another indicator that specialized performance credentials sustain premium pricing in smaller sub-segments.
Oxide families such as alumina, zirconia, and mullite delivered 62.80% of 2025 revenue owing to abundant raw material availability and well-documented process controls. These grades form the baseline for capacitor dielectrics and wear plates across multiple industries. Yet silicon carbide, silicon nitride, and emerging boron carbide non-oxide formulations are booking faster order growth because they combine lower density with thermal conductivities approaching copper. The non-oxide cohort is on a 7.76% trajectory through 2031, expanding the technical ceramics market by servicing frontier devices where oxide glass phases cannot survive. Cost barriers persist, but as fab line yields improve and reject rates fall below 5%, non-oxide price premiums are narrowing. Regulatory fuel-economy mandates and data-center heat-flux escalation both point to sustained long-run tailwinds for these higher-performance grades.
Composite or hybrid material classes merge oxide matrices with non-oxide whiskers or fibers, delivering synergistic toughness and conductivity. Interest is building in lanthanum-doped alumina blends that resist dielectric breakdown at elevated voltages, a property valued by grid-scale solid-state transformer projects. These cross-over formulations validate the thesis that future share battles will not be oxide versus non-oxide but hybrid versus single-phase, adding complexity yet widening solution space.
Complete Report Scope:
- By Product Type
- Monolithic Ceramics
- Ceramic Matrix Composites
- Ceramic Coatings
- Other Products
- By Material Class
- Oxide Ceramics
- Non-Oxide Ceramics
- Others
- By End-user Industry
- Electrical and Electronics
- Automotive
- Energy and Power
- Medical
- Aerospace and Defense
- Other End-user Industries
- By Key Application
- Insulators and Substrates
- Thermal Management Components
- Wear-resistant Parts and Bearings
- Bio-implants and Dental
- Armor and Protection
- By Geography
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia Pacific dominated the technical ceramics market with 43.40% share in 2025 and is tracking a 7.84% CAGR to 2031. Mainland China hosts the majority of alumina powder calcination and offers cost arbitrage in labor-intensive finishing steps, yet rising electricity tariffs and environmental compliance fees are eroding the historic savings gap. Japan is repositioning toward ultra-clean, high-value substrates that align with national semiconductor revival incentives; Kyocera's Nagasaki site will lift domestic fine-ceramic output by 10% upon its 2026 start-up. South Korea's memory-chip epicenter drives demand for low-defect silicon nitride boards, while India is luring EV supply-chain investors with tax holidays in Gujarat and Tamil Nadu. Regional governments are also mapping recycling corridors to capture scrap zirconia and yttria, an initiative that may dilute raw-material import dependencies over the long term.
North America is mature yet innovation-heavy, claiming nearly 30% of global R&D outlays tied to ceramic matrix composites. The United States accounts for the bulk of aerospace turbine and medical implant orders, justifying ISO-class kilns and USP Class VI clean-room protocols that less regulated regions bypass. Saint-Gobain's USD 40 million catalyst-carrier plant in New York will add 100 jobs and shorten delivery cycles for East-Coast petro-refiners. Canadian mining houses supply bauxite and rare-earth concentrates, but still send most feedstock to Asian refineries. Mexico is emerging as an assembly hub for EV inverters, prompting substrate suppliers to weigh near-shoring steps that sidestep USMCA rules-of-origin tariffs.
Europe claims roughly one-fifth of global revenue and aligns commercial success with sustainability mandates. Germany's machine-tool builders specify wear-resistant alumina guides that cut lubrication demand by 60%, dovetailing with EU eco-design standards. France and Spain are piloting hydrogen hubs that will soon require thousands of square meters of solid-oxide electrolyzer plates. The region's REACH chemical-safety framework compels tight traceability, a compliance cost that props up incumbents but slows new venture launches. Post-Brexit United Kingdom policy leans toward advanced materials catapults, aiming to translate university lab breakthroughs into pilot lines within three years, yet significant scale will hinge on export markets, given limited domestic demand.
- 3M
- CeramTec GmbH
- CoorsTek Inc.
- Dyson Technical Ceramics
- Kyocera Corporation
- Mantec Technical Ceramics Ltd
- McDanel Advanced Ceramic Technologies
- Morgan Advanced Materials
- NGK SPARK PLUG CO., LTD.
- Ortech, inc.
- Rauschert GmbH
- Saint-Gobain
- Schott AG
- STC Material Solutions
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expanding semiconductor and consumer-electronics output in Asia Pacific
- 4.2.2 EV power-train thermal-management needs
- 4.2.3 Rising use in high-value medical implants and devices
- 4.2.4 Hydrogen-electrolyser stack components
- 4.2.5 In-space manufacturing and satellite hardware
- 4.3 Market Restraints
- 4.3.1 High capital and processing cost
- 4.3.2 Intrinsic brittleness and machining losses
- 4.3.3 Critical-minerals supply-chain exposure
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Rivalry
- 4.6 Patent Analysis
- 4.7 Price Analysis
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Monolithic Ceramics
- 5.1.2 Ceramic Matrix Composites
- 5.1.3 Ceramic Coatings
- 5.1.4 Other Products
- 5.2 By Material Class
- 5.2.1 Oxide Ceramics
- 5.2.2 Non-Oxide Ceramics
- 5.2.3 Others
- 5.3 By End-user Industry
- 5.3.1 Electrical and Electronics
- 5.3.2 Automotive
- 5.3.3 Energy and Power
- 5.3.4 Medical
- 5.3.5 Aerospace and Defense
- 5.3.6 Other End-user Industries
- 5.4 By Key Application
- 5.4.1 Insulators and Substrates
- 5.4.2 Thermal Management Components
- 5.4.3 Wear-resistant Parts and Bearings
- 5.4.4 Bio-implants and Dental
- 5.4.5 Armor and Protection
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 Japan
- 5.5.1.3 India
- 5.5.1.4 South Korea
- 5.5.1.5 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/ Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 3M
- 6.4.2 CeramTec GmbH
- 6.4.3 CoorsTek Inc.
- 6.4.4 Dyson Technical Ceramics
- 6.4.5 Kyocera Corporation
- 6.4.6 Mantec Technical Ceramics Ltd
- 6.4.7 McDanel Advanced Ceramic Technologies
- 6.4.8 Morgan Advanced Materials
- 6.4.9 NGK SPARK PLUG CO., LTD.
- 6.4.10 Ortech, inc.
- 6.4.11 Rauschert GmbH
- 6.4.12 Saint-Gobain
- 6.4.13 Schott AG
- 6.4.14 STC Material Solutions
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment
- 7.2 Increasing Usage in Nano Technology

 技術陶瓷市場:按材料類型、產品類型、應用、終端用戶產業、分銷管道和地區分類
 工業陶瓷市場預測至2034年-全球材料、產品類型、製造流程、功能、應用、最終用戶和地區分析
 工業陶瓷市場規模、佔有率、趨勢和預測:按材料類型、產品類型、最終用途行業和地區分類,2026-2034年
 2026-2034年全球技術陶瓷市場規模、佔有率、趨勢和成長分析報告
 技術陶瓷市場:依原料、產品類型和最終用戶分類-2026年至2032年全球預測
 2026年全球碳化矽技術陶瓷市場報告碳化矽技術陶瓷市場按產品類型、製造流程、純度等級、形態、應用和最終用途產業分類-2026年至2032年全球預測2026-2032 年技術陶瓷市場(按原始材料、產品、最終用戶產業和地區分類)