


 |
市場調查報告書
商品編碼
2120754
高密度聚苯乙烯(HDPE):市場佔有率分析、產業趨勢與統計數據、成長預測(2026-2031)High-density Polyethylene (HDPE) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
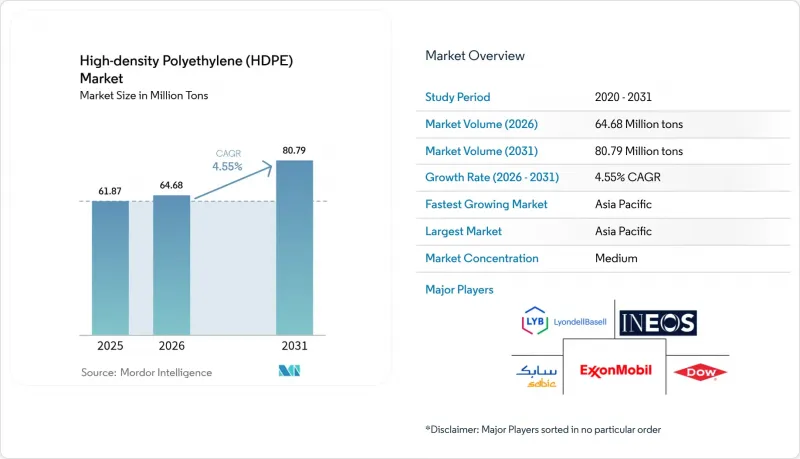
根據 Mordor Intelligence 預測,高密度聚苯乙烯(HDPE) 的市場規模預計將從 2025 年的 6,187 萬噸成長到 2026 年的 6,468 萬噸,並將從 2026 年到 2031 年以 4.55% 的複合年成長率,到 2031 萬噸。
本報告按應用(管道和管材、板材和薄膜、硬質產品及其他應用)、樹脂等級(PE-80、PE-100、PE-100-RC 等)、最終用戶行業(包裝、建築和施工、農業、運輸、電氣和電子等)以及地區(亞太地區、北美、歐洲、南美以及中東和非洲)進行分類。
全球高密度聚苯乙烯(HDPE)市場趨勢及洞察
水利基礎設施維修計畫中對承壓和非承壓塑膠管道的需求增加。
在供水管網現代化改造計畫中,高密度聚乙烯(HDPE)管道被優先考慮。這是因為,除了長達百年的使用壽命外,HDPE管路還可實現非開挖安裝,並可降低30%至40%的土建工程成本。美國土木工程師協會(ASCE)強調了HDPE管在老化供水管中的耐腐蝕性。此外,印度將於2024年起強制執行原生聚乙烯的品質標準,將進一步提升HDPE材料在關鍵供水應用中的可靠性。專案設計人員之所以青睞HDPE管線,是因為其柔軟性使其能夠適應地質條件的變化,並降低洩漏風險。公共部門的資金籌措週期跨越多個五年計劃,確保了管道需求的穩定,並鞏固了HDPE市場的可預測成長。非開挖施工方法的引入進一步降低了總安裝成本,使HDPE管道在與混凝土和球墨鑄鐵管道的競爭中脫穎而出。
吹塑成型食品包裝在新興電子商務通路的擴張
隨著電子商務的快速發展,市場對能夠在複雜的物流流程中保護食品品質的包裝需求日益成長。食品級高密度聚乙烯(HDPE)容器已通過嚴格的遷移測試並獲得美國食品藥物管理局(FDA)的批准,成為乳製品、調味品和常溫飲料的首選包裝。歐盟將於2025年3月生效的法規要求對食品接觸塑膠進行全面的可追溯性管理,而HDPE生產商目前已達到這些標準。透過薄壁吹塑成型實現輕量化,可減少樹脂用量,這不僅符合企業的減排目標,還能透過維持市場需求進一步增強HDPE市場的韌性。
加強對一次性塑膠的監管和課稅
在歐洲和北美部分地區,更嚴格的包裝法規對一次性高密度聚乙烯(HDPE)產品的需求造成了壓力。然而,HDPE的可再生降低了其在重複使用應用中的政策風險,而且與缺乏機械回收途徑的多層薄膜相比,其完善的回收系統使其更具吸引力。加工商正在重新設計瓶蓋和分配器系統,以控制重量並最大限度地減少體積損失。因此,這些法規既沒有抑制也沒有逆轉HDPE市場的成長。
細分市場分析
到2025年,片材和薄膜將佔高密度聚乙烯(HDPE)市場佔有率的40.65%,這主要得益於穩定的包裝需求以及下游加工商對吹膜製程日益成長的熟悉程度。永續包裝的目標正在推動單一材料薄膜的設計,而HDPE薄膜則優於混合聚合物薄膜。
儘管管道和管材在HDPE市場中所佔佔有率較小,但預計在2026年至2031年間,其複合年成長率將達到6.07%,成為市場成長最快的領域,這主要得益於水利基礎設施維修、氫氣天然氣管網建設以及非開挖施工技術的推廣應用。更嚴格的洩漏損失處罰措施迫使公共產業轉向使用HDPE管道,這種管道具有均質熔接接頭和長達100年的使用壽命。工業薄膜、地工止水膜和手提袋等產品構成了HDPE產品組合,即使在建築支出放緩的情況下,也能支撐對樹脂的基本需求。
區域分析
預計到2025年,亞太地區將佔據全球高密度聚乙烯(HDPE)市場42.30%的佔有率,並在2031年之前保持5.55%的複合年成長率,這主要得益於中國下游薄膜產品出口的成長和印度基礎設施建設的蓬勃發展。該地區的綜合生產商利用煤製烯烴製程和石腦油裂解裝置的柔軟性,有效緩解了乙烯價格波動的影響。然而,供應過剩時期會對全部區域的利潤率造成壓力,因此需要定期進行維護以調整庫存平衡。
北美高密度聚乙烯(HDPE)市場受益於乙烷基原料的優勢以及化學回收領域投資熱潮,這些因素增加了循環樹脂的供應。儘管其成長率低於亞太地區,但對高附加價值管道、薄膜和醫用級材料的需求支撐了其獲利能力。
歐洲仍以政策主導,氫能網路的發展正推動高密度聚乙烯(HDPE)應用於諸如PE-100-RC管道項目和化學品回收合作等項目中,以確保再生材料的供應。儘管由於一次性塑膠的禁令,對薄壁硬質包裝的需求有所下降,但HDPE憑藉其高回收性,在可重複使用可回收的包裝箱和化學品桶領域仍然佔據著重要地位。
其他好處:
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 水利基礎設施維修計畫中對承壓和非承壓塑膠管道的需求日益成長。
- 吹塑成型食品包裝在新興電子商務通路的擴張
- 東南亞國協和印度持續增加對公共住宅和大型基礎設施的投入
- 部署適用於氫氣的氣體管網,需要使用 PE-100-RC 管道
- 化學回收廠將混合廢棄物流轉化為原生級 RHDPE。
- 市場限制因素
- 加強對一次性塑膠的監管和課稅
- 乙烯原料價格波動與原油價格相關
- 消費品硬質包裝材料朝向無規聚丙烯共聚物的轉變正在加速。
- 價值鏈分析
- 波特五力模型
第5章 市場規模與成長預測
- 透過使用
- 管道和管材
- 片材和薄膜
- 硬產品
- 其他用途
- 依樹脂等級
- PE-80
- PE-100
- PE-100-RC
- 超高分子量HDPE
- 按最終用戶行業分類
- 包裝
- 建築/施工
- 農業
- 運輸
- 電氣和電子設備
- 工業機械
- 其他終端用戶產業
- 按地區
- 亞太地區
- 中國
- 印度
- 日本
- 韓國
- ASEAN
- 其他亞太國家
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 其他歐洲國家
- 南美洲
- 巴西
- 阿根廷
- 其他南美國家
- 中東和非洲
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 南非
- 其他中東和非洲國家
- 亞太地區
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- BASF
- Borealis AG
- Braskem
- Chevron Phillips Chemical
- Dow
- Exxon Mobil Corporation
- Formosa Plastics Corporation, USA
- Indian Oil Corporation
- INEOS
- LG Chem
- LyondellBasell Industries Holdings BV
- Mitsui Chemicals, Inc.
- NOVA Chemicals Corporate
- PTT Global Chemical Public Company Limited
- Qatar Chemical Company Ltd
- Reliance Industries Limited
- SABIC
- Sasol
- Sinopec
- TotalEnergies
- Westlake Corporation
第7章 市場機會與未來展望
According to Mordor Intelligence, the high-density polyethylene (HDPE) market size is expected to grow from 61.87 Million tons in 2025 to 64.68 Million tons in 2026 and is forecast to reach 80.79 Million tons by 2031 at 4.55% CAGR over 2026-2031.
This report is Segmented by Application (Pipes and Tubes, Sheets and Films, Rigid Articles, and Other Applications), Resin Grade (PE-80, PE-100, PE-100-RC, and More), End-User Industry (Packaging, Building and Construction, Agriculture, Transportation, Electrical and Electronics, and More), and Geography ( Asia-Pacific, North America, Europe, South America, and Middle-East and Africa).
Global High-density Polyethylene (HDPE) Market Trends and Insights
Rising Demand for Pressure and Non-Pressure Plastic Pipes in Water-Infrastructure Retrofit Programmes
Water-network modernisation projects prioritise HDPE pipes because they combine a 100-year service life with trenchless installation capability that cuts civil works costs by 30-40%. The American Society of Civil Engineers underscores HDPE's corrosion resistance for ageing distribution lines. India's 2024 quality-standard mandate for virgin polyethylene reinforces material integrity in critical water applications. Project designers favour HDPE because its flexibility accommodates ground movement, reducing leakage risk. Public-sector funding cycles spanning multiple five-year plans guarantee steady pipe volumes, ensuring predictable growth for the HDPE market. Integration of trenchless methods further differentiates HDPE from concrete and ductile-iron alternatives by lowering total installed costs.
Expansion of Food-Grade Blow-Molded Packaging in Emerging E-Commerce Channels
Rapid e-commerce penetration demands packaging that survives complex logistics while protecting food quality. Food-grade HDPE containers pass stringent migration tests and hold FDA clearance, making them default choices for dairy, condiments, and shelf-stable beverages. European Union regulations, effective March 2025, require extensive traceability for food-contact plastics, a standard that HDPE producers already meet. Weight-reduction via thin-wall blow-molding lowers resin usage, aligns with corporate emission targets, and sustains demand, reinforcing the HDPE market's resilience.
Escalating Anti-Single-Use-Plastic Regulations and Taxation
Tighter packaging rules compress demand for disposable HDPE articles in Europe and parts of North America. However, HDPE's recyclability mitigates policy risk in multi-use applications, and well-established collection streams preserve its appeal versus multi-layer films that lack mechanical-recycling pathways. Converters are redesigning closures and dispensing systems to remain within weight thresholds, limiting volume loss. Consequently, regulation restrains but does not reverse HDPE market growth.
Other drivers and restraints analyzed in the detailed report include:
- Sustained Public-Housing and Mega-Infrastructure Spend Across ASEAN and India
- Roll-out of Hydrogen-Ready Gas Grids Requiring PE-100-RC Pipes
- Volatile Crude-Oil-Linked Ethylene Feedstock Pricing
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Sheets and Films held 40.65% of the 2025 HDPE market share, underpinned by steady packaging demand and downstream converter familiarity with blown-film processes. Sustainable packaging targets stimulate mono-material film designs that favour HDPE over mixed polymers.
Pipes and Tubes, although a smaller slice of the HDPE market size, posted the sharpest 6.07% CAGR for 2026-2031 on the back of water-infrastructure retrofits, hydrogen-ready gas grids, and trenchless renewals. Rising leak-loss penalties push utilities toward HDPE piping thanks to its homogenous fusion joints and 100-year service life. Industrial films, geomembranes, and carrier bags round out the portfolio, sustaining baseline resin offtake when construction spending softens.
Complete Report Scope:
- By Application
- Pipes and Tubes
- Sheets and Films
- Rigid Articles
- Other Applications
- By Resin Grade
- PE-80
- PE-100
- PE-100-RC
- Ultra-High-Molecular-Weight HDPE
- By End-User Industry
- Packaging
- Building and Construction
- Agriculture
- Transportation
- Electrical and Electronics
- Industrial Machinery
- Other End-user Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific controlled 42.30% of the 2025 HDPE market share and is forecast to record a 5.55% CAGR to 2031, propelled by Chinese downstream film exports and India's infrastructure boom. Integrated producers in the region benefit from coal-to-olefins and naphtha-cracker flexibility, buffering ethylene volatility. However, oversupply periods have compressed regional margins, prompting scheduled maintenance to balance inventories.
North America's HDPE market benefits from ethane-advantaged feedstock and a wave of chemical-recycling investments that elevate circular-resin availability. While growth rates are lower than Asia-Pacific, value-added pipe, film, and medical-grade demand sustains profit pools.
Europe remains policy-driven; its hydrogen-network build-out channels HDPE into PE-100-RC pipe projects and chemical-recycling alliances that secure recycled feedstock. Anti-single-use-plastic mandates depress thin-wall rigid packaging volumes, yet high recyclability keeps HDPE firmly in multi-use, returnable crates and chemical drums.
- BASF
- Borealis AG
- Braskem
- Chevron Phillips Chemical
- Dow
- Exxon Mobil Corporation
- Formosa Plastics Corporation, U.S.A.
- Indian Oil Corporation
- INEOS
- LG Chem
- LyondellBasell Industries Holdings B.V.
- Mitsui Chemicals, Inc.
- NOVA Chemicals Corporate
- PTT Global Chemical Public Company Limited
- Qatar Chemical Company Ltd
- Reliance Industries Limited
- SABIC
- Sasol
- Sinopec
- TotalEnergies
- Westlake Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Demand for Pressure and Non-Pressure Plastic Pipes in Water-Infrastructure Retrofit Programmes
- 4.2.2 Expansion of Food?Grade Blow-Moulded Packaging in Emerging E-Commerce Channels
- 4.2.3 Sustained Public-Housing and Mega-Infrastructure Spend across ASEAN and India
- 4.2.4 Roll-Out of Hydrogen-Ready Gas Grids Requiring PE-100-RC Pipes
- 4.2.5 Chemical Recycling Plants Shifting Mixed-Waste Streams into Virgin-Grade RHDPE
- 4.3 Market Restraints
- 4.3.1 Escalating Anti-Single-Use-Plastic Regulations and Taxation
- 4.3.2 Volatile Crude-Oil-Linked Ethylene Feedstock Pricing
- 4.3.3 Accelerated Materials-Switch to PP Random Copolymers in Consumer Rigid Packaging
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Consumers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitute Products and Services
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Application
- 5.1.1 Pipes and Tubes
- 5.1.2 Sheets and Films
- 5.1.3 Rigid Articles
- 5.1.4 Other Applications
- 5.2 By Resin Grade
- 5.2.1 PE-80
- 5.2.2 PE-100
- 5.2.3 PE-100-RC
- 5.2.4 Ultra-High-Molecular-Weight HDPE
- 5.3 By End-User Industry
- 5.3.1 Packaging
- 5.3.2 Building and Construction
- 5.3.3 Agriculture
- 5.3.4 Transportation
- 5.3.5 Electrical and Electronics
- 5.3.6 Industrial Machinery
- 5.3.7 Other End-user Industries
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Russia
- 5.4.3.7 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 South Africa
- 5.4.5.4 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 BASF
- 6.4.2 Borealis AG
- 6.4.3 Braskem
- 6.4.4 Chevron Phillips Chemical
- 6.4.5 Dow
- 6.4.6 Exxon Mobil Corporation
- 6.4.7 Formosa Plastics Corporation, U.S.A.
- 6.4.8 Indian Oil Corporation
- 6.4.9 INEOS
- 6.4.10 LG Chem
- 6.4.11 LyondellBasell Industries Holdings B.V.
- 6.4.12 Mitsui Chemicals, Inc.
- 6.4.13 NOVA Chemicals Corporate
- 6.4.14 PTT Global Chemical Public Company Limited
- 6.4.15 Qatar Chemical Company Ltd
- 6.4.16 Reliance Industries Limited
- 6.4.17 SABIC
- 6.4.18 Sasol
- 6.4.19 Sinopec
- 6.4.20 TotalEnergies
- 6.4.21 Westlake Corporation
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

 全球高密度聚苯乙烯(HDPE)管材市場(2026-2030 年)
 2026年全球光滑壁高密度聚苯乙烯(HDPE)導管市場報告
 高密度聚苯乙烯市場:依形態、等級、分子量、應用及分銷通路分類-2026-2032年全球市場預測
 高密度聚苯乙烯(HDPE)樹脂市場規模、佔有率和成長分析:按產品類型、應用、加工方法、分銷管道和地區分類-2026-2033年產業預測
 高密度聚苯乙烯(HDPE)市場規模、佔有率、趨勢和預測:按原料、應用、製造流程和地區分類,2026-2034年
 高密度聚苯乙烯(HDPE)市場:按技術、應用、最終用戶和地區分類。2026年全球高密度聚苯乙烯(HDPE)管道市場報告(公用事業用)交聯高密度聚苯乙烯市場:依產品類型、交聯方法、形態和應用分類-全球預測,2026-2032年
 HDPE管材市場規模、佔有率和成長分析:按產品類型、最終用途行業、應用、尺寸/直徑、製造方法、分銷管道、地區和行業預測,2026-2033年高密度均聚物市場:依通路、加工技術、應用類型、產品等級及最終用途產業分類-全球預測,2026-2032年