


 |
市場調查報告書
商品編碼
2120559
BPaaS(業務流程即服務):市場佔有率分析、產業趨勢與統計資料、成長預測(2026-2031 年)Business-Process-as-a-Service - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||

※ 本網頁內容可能與最新版本有所差異。詳細情況請與我們聯繫。
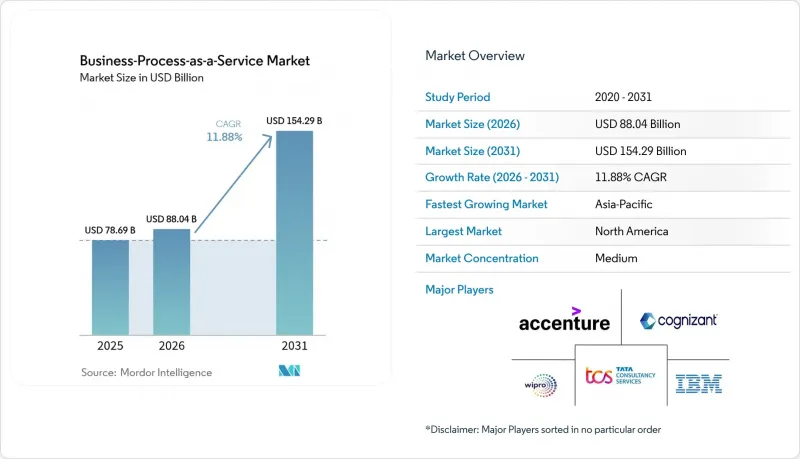
根據 Mordor Intelligence 預測,業務流程即服務 (BPaaS) 市場規模將從 2025 年的 786.9 億美元成長到 2026 年的 880.4 億美元,然後在 2031 年達到 1542.9 億美元,2026 年至 2031 年的複合年成長率為 11.8%。
本報告按組織規模(大型企業、中小企業)、流程(人力資源管理、會計和財務、其他)、部署模式(公共雲端流程即服務、私有雲端業務流程即服務、混合/多重雲端流程即服務)、最終用戶行業(銀行、金融服務和保險、IT和電信、其他)以及地區進行細分。市場預測以美元計價。
全球BPaaS市場趨勢與洞察
對雲端服務日益成長的需求以及流程的標準化
向雲端平台的普遍轉型正在推動大規模流程的標準化。目前,94% 的企業正在利用雲端解決方案來簡化工作流程、縮短引進週期並確保一致的管治。靈活的資源分配使他們能夠快速回應需求變化,而無需被迫做出新的資本投資決策。據 IBM 稱,77% 的企業已經實施了混合架構,這使他們能夠在多個雲端平台上整合核心流程,同時將策略性工作負載保留在優先管轄區內。標準化的雲端原生模組正在加速銀行和保險行業的合規運營,在這些行業中,統一的審計追蹤至關重要。因此,對於任何需要速度、彈性和全球覆蓋範圍的行業而言,BPaaS 市場都將在未來幾年保持持續成長勢頭。
降低營運成本和提高生產力的必要性
經濟逆風加劇了企業以計量收費模式取代固定成本的壓力。業務流程即服務 (BPaaS) 將多年期授權合約、資料中心折舊免稅額和人事費用(所有這些間接費用)轉化為基於實際使用量的變動價格。 DXC Technology 的一份報告顯示,企業透過從傳統外包遷移到 BPaaS 框架,實現了 20% 至 30% 的成本節約。這些服務內建的流程自動化進一步提高了生產力,一些公司報告稱其財務後勤部門營運效率提高了 40%。這些財務和營運方面的綜合優勢鞏固了 BPaaS 市場作為提高短期盈利和長期競爭力的有效途徑的地位。
人們越來越關注資料安全和隱私問題
採用業務流程即服務 (BPaaS) 涉及分散式基礎設施,這可能會擴大威脅目標的範圍。南非儲備銀行警告稱,如果控制不當,雲端運算可能會加劇營運和系統性風險。諸如歐洲的 GDPR 和加州的 CCPA 等法規對不合規行為處以嚴厲的處罰,迫使服務提供者實施高水準的加密、身分管理和異地資料架構。雖然加強監控暫時延緩了決策週期,且安全增強型平台正在湧現以重建人們對 BPaaS 市場的信心,但敏感產業的短期採用仍然有限。
細分市場分析
2025年,大型企業將主導BPaaS市場,佔63.55%的市佔率。這些企業正利用標準化的全球工作流程來簡化稽核並減少冗餘平台。通常,他們會先外包非核心的財務和人力資源職能,然後在確認其管治結構的穩健性後,再擴展到客戶體驗和供應鏈分析領域。整合仍然是重中之重,許多企業部署了中間件層,將本地ERP與公共雲端微服務整合,從而在保持戰略數據管理的同時,最大限度地發揮供應商的創新能力。同時,新成立的公司級管治委員會根據基本契約監控供應商的績效,以確保其與策略目標持續保持一致。
中小企業(SME)先前規模相對較小,如今卻展現出最強勁的成長勢頭,預計複合年成長率(CAGR)將達到12.97%。 「雲端優先」解決方案消除了資本投資、缺乏熟練人員和基礎設施維護等傳統障礙。據日本Kubel公司稱,截至2024年9月,其「Chatwork」平台已擁有60.5萬家中小企業客戶,凸顯了該領域龐大的潛在需求。中小企業通常從薪資核算、發票和客服自動化等單一流程模組入手,待可靠性得到驗證後,再擴展到端對端套件。靈活的定價模式對於確保企業在快速成長和景氣衰退時期的現金流柔軟性至關重要。因此,隨著供應商提供針對特定行業合規要求的預配置套餐,預計到2031年,由中小企業驅動的業務流程即服務(BPaaS)市場規模將顯著成長。
到2025年,人力資源管理(HR)將佔總收入的23.85%,這反映出全球日益認知到,標準化的招募、薪資核算和人才互動工作流程能夠降低合規風險並改善員工體驗。許多供應商目前正將預測分析功能(例如預測離職率、識別技能差距和推薦學習內容)整合到其人力資源模組中。在會計和財務流程方面,機器人發票匹配、自動匹配和人工智慧驅動的詐欺檢測正日益受到關注,因為它們能夠提高準確性並縮短處理時間。供應鏈和採購解決方案能夠增強供應商協作和庫存可見性,這在當今瞬息萬變的物流環境中至關重要。
客戶服務與支援領域預計將以每年 14.34% 的速度成長,品牌將重心轉向全通路客戶參與,推動了該領域的成長。人工智慧驅動的聊天機器人和語音分析技術能夠以遠低於傳統客服中心的成本,提供即時且個人化的回應。 Sutherland Global 的實施案例表明,平均回應時間縮短,首次回應解決率提高,淨推薦值 (NPS) 更高,升級次數更少。銷售和行銷業務流程即服務 (BPaaS) 進一步完善了這些技術,透過整合宣傳活動數據和前台分析,提升了銷售線索品質。營運模組則將工作流程引擎應用於現場服務部署、工廠維護計畫和品質保證。這些創新共同推動了 BPaaS 市場的持續擴張。
區域分析
由於早期雲端採用和強大的供應商生態系統,北美預計將在2025年佔據業務流程即服務 (BPaaS) 市場40.85%的佔有率。金融機構正在利用BPaaS整合跨司法管轄區的合規文檔,而零售集團則在推動人工智慧主導的客戶服務自動化。雲端基礎設施集中化趨勢明顯,英國競爭與市場管理局 (CMA) 估計,AWS佔據北美基礎設施市場40-50%的佔有率,微軟佔30-40%的佔有率。這種主導地位正促使BPaaS供應商尋求與超大規模資料中心業者服務商建立策略合作夥伴關係,以最佳化延遲並進行聯合市場部署專案。
預計亞太地區在2026年至2031年間將以12.62%的複合年成長率達到最高成長。印度、菲律賓和印尼政府正在推行「雲端優先」政策,以降低營運成本並改善公共服務。據印度資料安全委員會稱,到2022年,該國的雲端市場規模將達到77億美元,這表明其在基礎設施建設方面取得了進展。本地供應商正與全球公司合作,以滿足區域資料在地化的需求。面臨人手不足的日本企業正在利用業務流程即服務(BPaaS)來實現日常任務的自動化,從而刺激了製造業和零售業的需求。
在歐洲,隨著嚴格的隱私法規影響雲端技術的應用選擇,市場呈現穩定成長態勢。 GDPR合規性正在重新定義合約條款、資料儲存條款和責任共擔框架。預計到2029年,德國BPO市場規模將達到213.2億美元,其中81%的企業已經採用了雲端技術。金融機構傾向於採用混合模式,將本地主權雲與可擴展的公共資源結合,以滿足Eurofi的監管指南。該地區強勁的ESG(環境、社會和治理)運動正在推動對以永續發展為導向的BPaaS(業務流程即服務)解決方案的需求,這些解決方案能夠自動進行碳核算和社會影響報告。
其他福利
- Excel格式的市場預測(ME)表
- 3個月的分析師支持
目錄
第1章:引言
- 研究假設和市場定義
- 調查範圍
第2章:調查方法
第3章執行摘要
第4章 市場狀況
- 市場概覽
- 市場促進因素
- 對雲端服務日益成長的需求以及流程的標準化
- 降低營運成本和提高生產力的必要性
- 人工智慧和超自動化在業務流程即服務 (BPaaS) 領域的快速普及
- 擴展以績效為基礎的業務流程即服務 (BPaaS) 定價模式
- 由於環境、社會及公司治理 (ESG) 相關報告義務,對永續性業務流程即服務 (BPaaS) 的需求增加。
- 對產業特定 BPaaS 解決方案的需求
- 市場限制因素
- 人們越來越關注資料安全和隱私問題
- 與傳統核心系統整合的複雜性
- 供應商鎖定和互通性限制
- 主權雲端要求限制跨境即服務 (BPaaS)。
- 產業價值鏈分析
- 監理情勢
- 技術展望
- 產業吸引力—五力分析
- 供應商的議價能力
- 買方的議價能力
- 新進入者的威脅
- 替代品的威脅
- 競爭公司之間的競爭
- 宏觀經濟因素對市場的影響
第5章 市場規模與成長預測
- 按組織規模
- 大公司
- 中小企業
- 透過流程
- 人力資源管理(HRM)
- 會計與財務
- 客戶服務與支援
- 銷售與行銷
- 供應鏈與採購
- 營運和其他交叉流程
- 按部署模式
- 公共雲端BPaaS
- 私有雲端BPaaS
- 混合多重雲端BPaaS
- 按最終用戶行業分類
- BFSI
- IT/通訊
- 醫療保健和生命科學
- 零售與電子商務
- 製造業
- 政府/公共部門
- 其他
- 按地區
- 北美洲
- 美國
- 加拿大
- 墨西哥
- 南美洲
- 巴西
- 阿根廷
- 智利
- 其他南美國家
- 歐洲
- 德國
- 英國
- 法國
- 義大利
- 西班牙
- 俄羅斯
- 其他歐洲國家
- 亞太地區
- 中國
- 日本
- 印度
- 韓國
- 澳洲
- 新加坡
- 馬來西亞
- 其他亞太國家
- 中東和非洲
- 中東
- 沙烏地阿拉伯
- 阿拉伯聯合大公國
- 土耳其
- 其他中東國家
- 非洲
- 南非
- 奈及利亞
- 埃及
- 其他非洲地區
- 中東
- 北美洲
第6章 競爭情勢
- 市場集中度
- 策略趨勢
- 市佔率分析
- 公司簡介
- Accenture plc
- IBM Corporation
- Tata Consultancy Services(TCS)
- Cognizant Technology Solutions
- Wipro Limited
- HCL Technologies
- Capgemini SE
- Infosys Limited
- Genpact Ltd.
- Fujitsu Ltd.
- Oracle Corporation
- SAP SE
- Deloitte Touche Tohmatsu Limited
- NTT DATA
- CGI Inc.
- DXC Technology
- Tech Mahindra
- EXL Service Holdings
- ADP Inc.
- Alight Solutions
- Paychex Inc.
- UKG(Ultimate Kronos Group)
- TriNet Group
- Ceridian HCM
- WNS Global Services
- Sutherland Global Services
第7章 市場機會與未來趨勢
- 評估閒置頻段和未滿足的需求
According to Mordor Intelligence, the business-Process-as-a-Service market size is expected to grow from USD 78.69 billion in 2025 to USD 88.04 billion in 2026 and is forecast to reach USD 154.29 billion by 2031 at 11.88% CAGR over 2026-2031.
This report is Segmented by Organization Size (Large Enterprises and Small and Medium Enterprises), Process (Human Resource Management, Accounting and Finance, and More), Deployment Model (Public Cloud BPaaS, Private Cloud BPaaS, and Hybrid/Multi-Cloud BPaaS), End-User Industry (BFSI, IT and Telecommunications, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Business-Process-as-a-Service Market Trends and Insights
Growing Demand for Cloud Services and Standardized Processes
Universal migration toward cloud platforms underpins large-scale process standardization. Ninety-four percent of enterprises now leverage cloud solutions to streamline workflows, shorten deployment cycles, and ensure consistent governance. Elastic resource allocation supports rapid pivots in demand without forcing new capital decisions. IBM notes that 77% of firms already run hybrid architectures, enabling them to unify core processes over multiple clouds while keeping strategic workloads in preferred jurisdictions. Standardized, cloud-native modules accelerate compliance tasks in banking and insurance, where uniform audit trails are essential. As a result, the Business-Process-as-a-Service market experiences sustained multi-year momentum across sectors that demand speed, resilience, and global reach.
Need to Reduce Operational Cost and Boost Productivity
Economic headwinds intensify pressure to replace fixed costs with consumption-based models. BPaaS converts multi-year license contracts, data-center depreciation, and labor overhead into variable fees that align with actual usage. DXC Technology reports savings of 20-30% when organizations shift from traditional outsourcing to BPaaS frameworks. Process automation embedded in these services delivers additional productivity gains, with some enterprises citing 40% efficiency improvements in finance back-office tasks. These combined financial and operational benefits reinforce the Business-Process-as-a-Service market as a pragmatic lever for near-term profitability and long-term competitiveness.
Heightened Data-Security and Privacy Concerns
BPaaS deployments involve a distributed infrastructure that can enlarge the threat surface. The South African Reserve Bank cautions that cloud computing amplifies operational and systemic risks when controls are weak. European GDPR and California CCPA regulations impose severe penalties for non-compliance, compelling providers to implement sophisticated encryption, identity management, and regional data-residency architectures. Heightened scrutiny temporarily slows decision cycles, limiting short-term adoption in sensitive verticals even as security-enhanced platforms emerge to rebuild trust in the Business-Process-as-a-Service market.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Adoption of AI / Hyper-automation in BPaaS
- Expansion of Outcome-based (Gain-share) BPaaS Pricing Models
- Integration Complexity with Legacy Core Systems
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Large Enterprises dominated 2025 with 63.55% of the Business-Process-as-a-Service market share, leveraging standardized global workflows to simplify audits and cut duplicative platforms. They often start by outsourcing non-core finance and HR tasks, then extend coverage to customer experience and supply-chain analytics once governance structures prove resilient. Integration remains a priority; many deploy middleware layers that blend on-premise ERPs with public-cloud microservices, preserving strategic data control while maximizing vendor innovation. In parallel, fresh enterprise-wide governance councils monitor vendor performance under outcome-based contracts, ensuring continuous alignment with strategic objectives.
SMEs, though historically under-represented, now display the strongest momentum with a forecast 12.97% CAGR. Cloud-first solutions remove traditional barriers such as capital outlay, specialist talent shortages, and infrastructure maintenance. Japan's Kubell Co. reports that its Chatwork platform served 605,000 SME clients by September 2024, underscoring the segment's pent-up demand. SMEs typically begin with single-process modules-payroll, invoicing, or help-desk automation-before scaling to end-to-end suites as reliability is proven. The elastic fee model offers crucial cash-flow flexibility during growth spurts or economic contractions. Consequently, the Business-Process-as-a-Service market size attributable to SMEs is projected to widen substantially through 2031 as providers release pre-configured bundles tailored for industry-specific compliance.
Human Resource Management retained 23.85% of 2025 revenue, reflecting global recognition that standardized recruitment, payroll, and talent-engagement workflows lower compliance risk and enhance employee experience. Many providers now pair HR modules with predictive analytics that forecast attrition, identify skill gaps, and recommend learning content. Accounting and Finance processes also gain traction as robotic invoice matching, automated reconciliations, and AI-driven fraud checks boost accuracy while shrinking cycle times. Supply Chain and Procurement solutions improve vendor collaboration and inventory visibility, critical in volatile logistics environments.
Customer Service and Support, forecast to rise 14.34% annually, leads growth as brands pivot to omnichannel engagement. AI-driven chatbots and voice analytics deliver instant, personalized responses at far lower cost than traditional call centers. Sutherland Global's deployments cut average response time while raising first-contact resolution, enhancing NPS scores, and reducing escalations. Sales and Marketing BPaaS complements these advances, synchronizing campaign data with front-office analytics to sharpen lead quality. Operations modules apply workflow engines to field-service dispatch, plant-maintenance scheduling, and quality assurance. Together, these innovations anchor sustained expansion of the Business-Process-as-a-Service market.
Complete Report Scope:
- By Organization Size
- Large Enterprises
- Small and Medium Enterprises (SMEs)
- By Process
- Human Resource Management (HRM)
- Accounting and Finance
- Customer Service and Support
- Sales and Marketing
- Supply Chain and Procurement
- Operations and Other Horizontal Processes
- By Deployment Model
- Public Cloud BPaaS
- Private Cloud BPaaS
- Hybrid/Multi-Cloud BPaaS
- By End-user Industry
- BFSI
- IT and Telecommunications
- Healthcare and Life Sciences
- Retail and E-Commerce
- Manufacturing
- Government and Public Sector
- Other End-user Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Singapore
- Malaysia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America generated 40.85% of 2025 revenue for the Business-Process-as-a-Service market, buoyed by early cloud uptake and deep provider ecosystems. Financial institutions use BPaaS to consolidate compliance documentation across jurisdictions, while retail groups pursue AI-led customer-service automation. Cloud infrastructure concentration is notable; the UK Competition and Markets Authority estimates AWS and Microsoft hold 40-50% and 30-40% of North American infrastructure, respectively. This dominance encourages BPaaS vendors to forge strategic alliances with hyperscalers for latency optimization and joint go-to-market programs.
Asia-Pacific is projected to record the fastest 12.62% CAGR between 2026 and 2031. Governments in India, the Philippines, and Indonesia promote "cloud first" mandates to reduce operating costs and improve citizen services. The Data Security Council of India notes that the national cloud market reached USD 7.70 billion by 2022, underscoring the readiness of foundational infrastructure. Indigenous providers partner with global players to address regional data-localization requirements. Japanese enterprises, challenged by labor shortages, lean on BPaaS to automate routine functions, stimulating demand across manufacturing and retail sectors.
Europe exhibits measured growth as stringent privacy rules guide deployment choices. GDPR compliance shapes contract terms, data-residency clauses, and shared-responsibility frameworks. Germany's BPO market, forecast to hit USD 21.32 billion by 2029, already registers 81% cloud adoption among firms. Financial institutions prefer hybrid models, pairing local sovereign clouds with scalable public resources to satisfy supervisory guidance outlined by Eurofi. The region's strong ESG agenda fuels demand for sustainability-centric BPaaS solutions that automate carbon accounting and social-impact reporting.
- Accenture plc
- IBM Corporation
- Tata Consultancy Services (TCS)
- Cognizant Technology Solutions
- Wipro Limited
- HCL Technologies
- Capgemini SE
- Infosys Limited
- Genpact Ltd.
- Fujitsu Ltd.
- Oracle Corporation
- SAP SE
- Deloitte Touche Tohmatsu Limited
- NTT DATA
- CGI Inc.
- DXC Technology
- Tech Mahindra
- EXL Service Holdings
- ADP Inc.
- Alight Solutions
- Paychex Inc.
- UKG (Ultimate Kronos Group)
- TriNet Group
- Ceridian HCM
- WNS Global Services
- Sutherland Global Services
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing demand for cloud services and standardized processes
- 4.2.2 Need to reduce operational cost and boost productivity
- 4.2.3 Rapid adoption of AI/hyper-automation in BPaaS
- 4.2.4 Expansion of outcome-based BPaaS pricing models
- 4.2.5 ESG-linked reporting mandates driving sustainability BPaaS
- 4.2.6 Demand for industry-specific BPaaS solutions
- 4.3 Market Restraints
- 4.3.1 Heightened data-security and privacy concerns
- 4.3.2 Integration complexity with legacy core systems
- 4.3.3 Vendor lock-in and interoperability limitations
- 4.3.4 Sovereign-cloud requirements restricting cross-border BPaaS
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Industry Attractiveness - Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Organization Size
- 5.1.1 Large Enterprises
- 5.1.2 Small and Medium Enterprises (SMEs)
- 5.2 By Process
- 5.2.1 Human Resource Management (HRM)
- 5.2.2 Accounting and Finance
- 5.2.3 Customer Service and Support
- 5.2.4 Sales and Marketing
- 5.2.5 Supply Chain and Procurement
- 5.2.6 Operations and Other Horizontal Processes
- 5.3 By Deployment Model
- 5.3.1 Public Cloud BPaaS
- 5.3.2 Private Cloud BPaaS
- 5.3.3 Hybrid/Multi-Cloud BPaaS
- 5.4 By End-user Industry
- 5.4.1 BFSI
- 5.4.2 IT and Telecommunications
- 5.4.3 Healthcare and Life Sciences
- 5.4.4 Retail and E-Commerce
- 5.4.5 Manufacturing
- 5.4.6 Government and Public Sector
- 5.4.7 Other End-user Industries
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Chile
- 5.5.2.4 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia
- 5.5.4.6 Singapore
- 5.5.4.7 Malaysia
- 5.5.4.8 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Egypt
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Accenture plc
- 6.4.2 IBM Corporation
- 6.4.3 Tata Consultancy Services (TCS)
- 6.4.4 Cognizant Technology Solutions
- 6.4.5 Wipro Limited
- 6.4.6 HCL Technologies
- 6.4.7 Capgemini SE
- 6.4.8 Infosys Limited
- 6.4.9 Genpact Ltd.
- 6.4.10 Fujitsu Ltd.
- 6.4.11 Oracle Corporation
- 6.4.12 SAP SE
- 6.4.13 Deloitte Touche Tohmatsu Limited
- 6.4.14 NTT DATA
- 6.4.15 CGI Inc.
- 6.4.16 DXC Technology
- 6.4.17 Tech Mahindra
- 6.4.18 EXL Service Holdings
- 6.4.19 ADP Inc.
- 6.4.20 Alight Solutions
- 6.4.21 Paychex Inc.
- 6.4.22 UKG (Ultimate Kronos Group)
- 6.4.23 TriNet Group
- 6.4.24 Ceridian HCM
- 6.4.25 WNS Global Services
- 6.4.26 Sutherland Global Services
7 MARKET OPPORTUNITIES AND FUTURE TRENDS
- 7.1 White-Space and Unmet-Need Assessment

 BPaaS(業務流程即服務)市場:2026-2032年全球市場預測(依服務類型、部署模式、企業規模及產業分類)
 全球業務流程即服務 (BPaaS) 市場:機會與策略展望(至 2035 年)
 業務流程即服務 (BPaaS) 市場規模、佔有率和趨勢分析報告:按業務流程、組織規模、應用、地區和細分市場預測 (2026–2033)2026年全球業務流程管理(BPM)解決方案市場報告
 業務流程即服務 (BPaaS) 市場規模、佔有率和成長分析:按組件、流程類型、部署方式、組織規模、產業和地區分類-2026 年至 2033 年產業預測
 業務流程即服務 (BPaaS) 市場報告:按流程、部署類型、企業規模、產業和地區分類 (2026–2034)
 全球業務流程即服務 (BPaaS) 市場規模、佔有率、趨勢和成長分析報告(2026-2034 年)
 業務流程即服務市場分析及至2035年預測:依類型、產品類型、服務、技術、組件、應用、流程、部署類型、最終用戶及功能分類
 業務流程即服務 (BPaaS) 市場 - 全球產業規模、佔有率、趨勢、機會與預測:按應用、部署模式、公司規模、垂直產業、地區和競爭格局預測,2021-2031 年BPaaS(業務流程即服務)市場-2025-2030 年預測